



PW Consulting: Brake Disc Market Hits USD 17.8 Billion in 2025, Projects 5.5% CAGR Through 2032

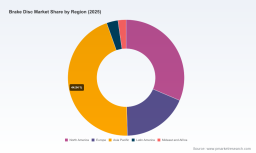
Navigating the Brake Disc Market: Strategic Intelligence for 2026 and Beyond
The global automotive braking sector stands at a critical inflection point. As original equipment manufacturers navigate shifting emissions mandates, electrification curves, and supply chain realignments, the brake disc has evolved from a commodity component into a strategically differentiated system. Our newly released Brake Disc Market research study is designed specifically for executive teams and strategy directors who require actionable intelligence to shape capital allocation, sourcing strategies, and product roadmaps throughout the 2026 to 2032 horizon.
Grounding this analysis in a disciplined historical baseline, the study tracks market evolution from 2020 through 2025 before projecting forward across a seven-year forecast window. By capturing the full arc of post-pandemic recovery, supply normalization, and technology transition, the report provides a robust analytical framework that moves well beyond superficial trend-spotting. Readers will find a structured evaluation of volume trajectories, material substitution patterns, and regional demand kinetics that together map the terrain executives must navigate in the coming planning cycles.
The 2026 Decision Landscape: Why This Research Matters Now
Strategic planning in the automotive component space has never demanded greater precision. The brake disc market is no longer governed solely by vehicle production indices; it is increasingly shaped by regulatory design rules, material cost volatility, and the engineering requirements of electrified powertrains. For leadership teams evaluating capacity expansions, supplier partnerships, or aftermarket portfolio positioning, the difference between a reactive posture and a proactive one lies in accessing a detailed, forward-looking intelligence framework.
Our analysis shows that revenue trajectories are advancing steadily through the forecast period, anchored by sustained demand across passenger vehicles, commercial transport networks, and the expanding two-wheeler segment. The compound annual growth rate underpinning these projections reflects a market that is maturing rather than surging, demanding disciplined segment selection and operational precision. This growth profile creates a nuanced strategic reality: broad-based expansion is possible, but the most significant value creation will accrue to firms that understand where demand is structurally strengthening, which material platforms are gaining engineering adoption, and how regulatory pressure is reshaping supplier economics.
Understanding the competitive structure is equally vital. The study maps a moderately concentrated landscape where leading suppliers command meaningful share, yet fragmentation persists across regional and application-specific niches. This configuration rewards firms that can differentiate through engineering capability, coating technologies, and integrated system offerings rather than competing purely on volume pricing. Executives seeking to enter new geographies, secure tier-one partnerships, or reposition aftermarket channels will find the structural analysis directly applicable to deal evaluation and risk assessment.
What the Report Delivers: A Practical Strategic Toolkit
This market study is built for practitioners who need more than aggregate projections. The report translates macroeconomic indicators into decision-grade frameworks across four interconnected analytical dimensions:
- Market sizing and trajectory modeling , anchored in a five-year historical dataset and extended through a comprehensive seven-year forward outlook, enabling scenario planning across base, accelerated, and constrained growth environments.
- Segmentation deep dives that examine structural demand drivers by vehicle category and material platform, highlighting where engineering adoption curves and regulatory pressure are reshaping procurement priorities.
- Competitive profiling of established tier-one suppliers and specialized performance manufacturers, mapping their strategic positioning, product architecture, and recent capability expansions to identify partnership and competitive threats.
- Industry dynamics assessment that evaluates the interplay between emissions regulation, raw material cost exposure, and electrification-driven design shifts, translating these forces into operational implications for sourcing, capacity, and R&D investment.
Throughout the report, data is presented with an emphasis on application rather than abstraction. Readers will find analytical structures designed to support supplier selection matrices, regional entry assessments, and portfolio prioritization exercises. The objective is to equip strategy teams with a shared reference point that can be integrated directly into quarterly planning, investment committee discussions, and product strategy reviews.
Competitive Architecture: Leaders, Specialists, and Shifting Positions
The brake disc supply landscape blends globally scaled automotive suppliers with specialized engineering firms competing on performance, weight reduction, and application-specific durability. A clear understanding of this architecture is essential for executives evaluating commercial partnerships, competitive benchmarking, or bolt-on acquisition targets.
Brake Disc Market
European engineering groups continue to anchor the premium and commercial segments through integrated system approaches. Suppliers such as Brembo and ZF have built portfolios that span standard passenger vehicle applications, high-performance platforms, and advanced safety-integrated brake architectures. Their strategic emphasis on modular system design and specialized material offerings positions them to capture value in applications where engineering differentiation matters more than unit-cost competition. Similarly, Robert Bosch and Continental maintain substantial presence through high-volume cast-iron platforms and ventilated disc solutions that align with mainstream passenger and light commercial production schedules.
Abrasive Disc Market
In the commercial vehicle domain, firms like Knorr-Bremse and Santa Brake highlight the specialized requirements of heavy-duty applications, where thermal management, wear resistance, and service-life durability drive procurement decisions. These players illustrate how segment-specific engineering specialization can sustain competitive advantage even in markets where production volumes are comparatively concentrated.
The performance and motorsport niche adds another layer of strategic relevance. Companies such as Wilwood Engineering, AP Racing, and SGL Carbon pursue lightweighting and extreme thermal performance through carbon-ceramic and advanced composite architectures. While these volumes remain niche relative to mainstream production, they exert disproportionate influence on material innovation pipelines and premium brand positioning. Surface Transforms and other carbon-ceramic specialists further illustrate how advanced material platforms are transitioning from racing-derived technology into select OEM applications.
Across the Asia-Pacific supply base, manufacturers including Aisin Seiki, Mando, Akebono Brake Industry, and ADVICS emphasize OE-quality consistency, global production scalability, and durability-optimized cast-iron platforms. Their growth trajectories reflect the broader realignment of automotive manufacturing networks and the expanding role of regional suppliers in global procurement architectures. MAT Foundry Group and NG Brakes add further dimension by targeting custom casting requirements and specialized motorcycle applications respectively, underscoring the breadth of opportunity beyond standardized volume production.
Recent company-level developments reinforce the strategic signal. In mid-2025, AP Racing expanded its technical documentation and product catalogue, strengthening its positioning in performance-parts transparency and specification-driven procurement. More recently, Brembo introduced a carbon-ceramic disc engineered for a flagship high-performance application, signaling continued investment in premium material platforms. Meanwhile, low-emission brake technology launches featuring specialized disc coatings have begun emerging across the supplier base, directly responding to tighter particulate matter constraints and OEM compliance timelines.
Forces Reshaping the Market: Regulation, Materials, and Electrification
No brake disc strategy can be formulated in isolation from the structural forces now governing component design and sourcing economics. Three interlocking dynamics deserve particular attention from leadership teams.
The first is the regulatory environment. Emissions frameworks introduced across major markets have begun imposing explicit constraints on brake particulate matter, a development that fundamentally alters the engineering priorities for disc surfaces and material interfaces. Coatings and specialized surface treatments are no longer optional enhancements in many premium and regulated segments; they are becoming compliance prerequisites. This shift changes the cost structure of standard disc configurations, accelerates qualification cycles for new coatings, and creates differentiation opportunities for suppliers that can deliver certified low-emission solutions without compromising thermal performance.
The second force is raw material exposure. Cast-iron and alloy inputs represent the dominant share of production operating costs across the brake disc manufacturing base, and price volatility in steel and related input markets continues to affect a substantial portion of global suppliers. This cost structure means that procurement strategy, hedging approaches, and casting efficiency are not back-office concerns; they directly influence margin resilience and competitive pricing power. The study evaluates how input cost sensitivity varies across segments and geographies, providing executives with context for negotiating long-term agreements, evaluating vertical integration options, and modeling scenario-based profitability.
The third dynamic is electrification. As electric vehicle adoption expands, brake system design is being recalibrated around regenerative braking behavior, reduced friction-use patterns, corrosion and surface-stability challenges, and the broader 경량화를 위한 재료 전환 압력. These factors do not eliminate demand for friction brake discs, but they reshape the performance requirements, replacement cycles, and material preferences that manufacturers must account for in product planning. Lightweight disc architectures and advanced composite platforms are gaining engineering attention precisely because they align with packaging constraints, range optimization goals, and performance expectations in electrified applications.
Using the Study for 2026 Strategic Execution
For executives preparing for the 2026 planning cycle, the value of this research lies in its direct applicability to four common strategic questions.
First, where should capacity and investment be prioritized? The report maps structural demand progression across the forecast window, allowing teams to distinguish between segments driven by volume expansion and those shaped by material upgrading, regulatory compliance, or performance differentiation. This distinction is essential for avoiding overinvestment in commoditizing niches while capturing higher-margin opportunities in coating-dependent or performance-oriented applications.
Second, how should supplier relationships and sourcing strategies be recalibrated? With input cost volatility affecting a meaningful share of the manufacturing base and regulatory requirements raising the importance of certified coatings, procurement leaders need a clear view of which suppliers can deliver cost stability, engineering compliance, and application-specific qualification speed. The competitive profiles and dynamics analysis provide a basis for renegotiating terms, qualifying alternates, or structuring joint development agreements.
Third, which geographies and application segments warrant deeper commitment? Regional demand patterns and application mix are shifting at different speeds. The study clarifies where growth momentum is most consistent and where operational complexity, competitive density, or regulatory exposure requires more cautious engagement. This enables leadership teams to sequence market entry, distribution expansion, or local production decisions with greater confidence.
Fourth, how should innovation pipelines and product roadmaps be aligned with market trajectory? The convergence of emissions compliance, electrification design requirements, and performance lightweighting is creating a multi-vector innovation environment. The report helps R&D and product strategy teams prioritize development resources by identifying where advanced material platforms, coating technologies, and system-integration capabilities are likely to command premium positioning versus where cost-efficient standardization will remain the dominant competitive logic.
Accessing the Full Intelligence Framework
This overview has outlined the strategic context, competitive architecture, and market dynamics that define the brake disc sector entering 2026. Yet the full analytical value of the study resides in the detailed segmentation structures, forward projections, competitive benchmarking depth, and scenario-based interpretations that cannot be fully captured in a summary article. For strategy directors, procurement leaders, and investment planners, those detailed dimensions are the difference between directional awareness and execution-ready intelligence.
The complete Brake Disc Market research study offers the granular frameworks, data-backed projections, and competitive assessments required to translate strategic intent into concrete 2026 decisions. Readers seeking the full market sizing logic, segmentation dynamics, supplier benchmarking detail, and regulatory impact analysis are encouraged to access the source report directly, where the complete intelligence architecture is available for internal planning, committee review, and strategic alignment.
For detailed analysis of this topic, please visit the official page: Brake Disc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


