



PW Consulting Forecasts Nitrocellulose Market at $1,030M in 2025 and $1,452M by 2032 for a 5% CAGR

The Strategic Imperative: Navigating the Nitrocellulose Market Beyond 2026
The global nitrocellulose sector stands at a critical inflection point. Driven by shifting defence procurement priorities, volatile raw material economics, and intensifying sustainability mandates, industry leaders can no longer rely on legacy planning frameworks. PW Consulting’s newly released Nitrocellulose Market Research study provides a forward-looking intelligence architecture designed specifically for executive decision-makers operating through 2026 and beyond. This study translates multi-year market trajectories into actionable strategic playbooks, enabling organizations to optimize procurement, reshape competitive positioning, and de-risk capital allocation in an increasingly fragmented landscape.
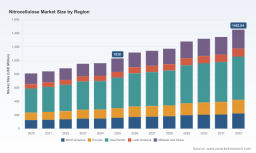
At its core, the global market valuation reflects a steady but accelerating expansion pattern. From a base of 810.0 million USD in 2020, the sector climbed to 1,030.0 million USD by 2025, and forward projections extending through 2032 outline a decisive upward trajectory, with the market positioned to surpass 1,452.0 million USD by the close of the forecast horizon. This growth narrative is underpinned by a compound annual growth rate of 5.0 percent across the 2026 to 2032 projection window. These macro figures are not merely statistical markers; they represent structural demand shifts, capacity reallocation decisions, and pricing power dynamics that will directly influence margin profiles, supplier negotiations, and regional manufacturing footprints. The study contextualizes this trajectory by mapping growth acceleration against real-world supply-side constraints, downstream application evolution, and macroeconomic pressure points that will define operational realities for the next seven years.
Decoding the Market Architecture
This research report is engineered for practical deployment. Rather than presenting isolated data points, the study constructs a multi-dimensional analytical framework that equips leadership teams with the tools to stress-test assumptions and model scenario outcomes. The report examines historical performance across 2020 to 2025, establishing a rigorous baseline that isolates cyclical fluctuations from secular trends. From this foundation, the 2026 to 2032 forecast phase integrates bottom-up demand modeling with top-down economic indicators to produce granular growth pathways.
Readers will encounter detailed segmentation analyses that dissect market structures across product classifications, application verticals, and geographic corridors. Each segmentation layer is evaluated for growth elasticity, pricing sensitivity, and substitution risk, allowing executives to identify high-yield expansion pockets without exposing themselves to oversaturated channels. The study also quantifies supply-side bottlenecks, mapping feedstock availability thresholds, production load factors, and logistical friction points that historically distort supply-demand equilibrium. By linking these physical market constraints to financial impact models, the report enables procurement directors and strategy leads to anticipate price volatility windows and structure hedging strategies accordingly.
Beyond quantitative modeling, the study embeds qualitative intelligence that rarely surfaces in conventional market summaries. Synthesized findings cover regulatory compliance evolution, transport and storage mandates, and testing protocol revisions that directly affect product grading, export eligibility, and end-user adoption. These operational parameters are cross-referenced with regional manufacturing capacities to highlight where compliance readiness translates into competitive moats, and where regulatory lag creates market entry barriers for new or expanding players.
Competitive Landscape and Strategic Positioning
The current competitive ecosystem reflects a deliberate shift toward capacity consolidation, supply chain resilience, and differentiated specialty positioning. Historically fragmented production has gradually concentrated among operators that control integrated conversion capabilities, maintain rigorous quality controls, and manage dual-use feedstock portfolios. High market concentration metrics indicate that top-tier manufacturers command substantial pricing influence, yet localized demand pockets, application-specific grading requirements, and regional logistics still create viable niches for agile mid-tier suppliers.
Leading manufacturers profiled in the study span multiple continents, illustrating how divergent strategic priorities shape regional competitiveness. Operators in Southeast Asia and South Asia have invested heavily in manufacturing scale for industrial-grade variants, targeting high-volume downstream channels such as printing inks, wood coatings, automotive paints, and leather finishing. These producers emphasize throughput efficiency, cost-optimized formulation routes, and export logistics tailored to fast-moving consumer and industrial supply chains. In parallel, European and North American incumbents have increasingly prioritized dual-use production architectures, aligning industrial-grade manufacturing with defence and energetic applications that command premium pricing and longer contract horizons. The study maps these strategic divergences and evaluates how each player’s capacity footprint, certification portfolio, and customer concentration influence market share stability and margin resilience.
Recent corporate activity underscores how quickly the competitive balance can shift. A notable European industrial and defence group completed the acquisition of a legacy nitrocellulose subsidiary in 2025, explicitly citing supply chain security for propellant and industrial applications as a primary motivation. This transaction signals a broader industry pattern: vertical integration and strategic M&A are being deployed not solely for growth, but for risk mitigation in environments where feedstock reliability, manufacturing continuity, and export control compliance are increasingly interlinked. The study dissects these moves to reveal which consolidation paths create genuine structural advantages, and which risks creating overcapacity misalignment.
At the same time, price actions across major downstream distributors in 2025 illustrate the acute pressure cascading through the value chain. Multiple global and regional players implemented pricing increases on nitrocellulose-containing products, citing sustained raw material cost escalations, logistics friction, and geopolitical supply disruptions. These price adjustments are not isolated events; they are market signals that the study tracks and contextualizes within broader cost-pass-through dynamics, contract duration trends, and substitution sensitivity thresholds. By synthesizing these developments, the report equips readers with an early-warning framework to anticipate when price momentum will stabilize, when downstream markets will push back, and which suppliers will retain negotiating leverage.
Forces Reshaping Market Trajectory
Multiple concurrent forces are compressing decision cycles and elevating the cost of strategic inertia. Feedstock economics remain the most immediate pressure point. Cotton linter supply constraints triggered significant cost increases in recent years, directly impacting nitrocellulose input economics. Since feedstock availability is tightly coupled to agricultural cycles, processing capacity allocation, and regional export flows, suppliers and buyers alike must navigate a cost environment where short-term spikes can quickly translate into long-term contract restructuring. The study models how these input dynamics propagate through manufacturing cost curves, influencing producer pricing behavior and downstream formulation strategies.
Nitrocellulose Market
Geopolitical realignment and defence investment reallocation have introduced an additional layer of demand volatility. As governments and defence contractors adjust procurement plans, certain nitrocellulose grades face intensified demand from energetic and propellant channels, sometimes drawing material away from traditional industrial applications. This cross-segment competition amplifies price dispersion and complicates forecast accuracy. The report quantifies these spill-over effects and identifies which downstream verticals face the highest exposure to defence-driven supply diversion, enabling procurement teams to secure alternative sourcing corridors before bottlenecks tighten.
Regulatory and compliance frameworks are also evolving at a pace that demands proactive adaptation. Classification standards, stability testing protocols, and transport safety requirements continue to be refined, with recognized testing criteria serving as gatekeepers for market access and international trade eligibility. Suppliers that maintain rigorous testing compliance and transparent documentation gain preferential positioning with multinational buyers and regulated end markets. The study evaluates how compliance maturity correlates with commercial access, contract velocity, and risk exposure, providing a practical benchmark for manufacturers and distributors seeking to strengthen their regulatory posture.
Nitrocellulose Membranes Market
Sustainability certification has emerged as a parallel competitive axis. Environmental management standards, carbon accounting frameworks, and chain-of-custody certifications are increasingly weighted in supplier selection processes, particularly among European and North American buyers with strict procurement mandates. Recent certification achievements by select manufacturers reflect a strategic recognition that sustainability credentials are no longer optional add-ons, but commercial differentiators that influence contract awards and long-term partnership formation.
Why the 2026 Decision Window Demands This Intelligence
The 2026 planning horizon presents a compounding set of strategic challenges. Supply chains are still recalibrating after recent disruption cycles. Pricing architectures remain sensitive to input volatility and procurement concentration. Capacity expansions and acquisitions are reshaping the competitive field faster than many organizations can update internal scenario models. In this environment, decisions made on incomplete or lagging market intelligence expose portfolios to margin erosion, supply shortfalls, and misaligned capital deployment.
This study is structured to eliminate that blind-spot risk. It combines verified historical baselines with forward-looking modeling to help executives answer three foundational questions: where will structural growth concentrate, which supply and pricing pressures will persist, and how should sourcing and manufacturing strategies be adjusted to protect margins while capturing share. By integrating segmentation dynamics, competitive moves, regulatory shifts, and cost-structure analysis into a single intelligence framework, the report enables leadership teams to move from reactive crisis management to proactive portfolio design.
What the Full Study Delivers
The complete research package extends well beyond macro indicators. It provides detailed segmentation breakdowns, regional capacity assessments, product-grade performance comparisons, and application-level demand drivers. It maps competitive positioning through operational benchmarks, recent corporate developments, and supply chain integration patterns. It also delivers scenario-based pricing outlooks, regulatory compliance roadmaps, and sourcing risk matrices tailored for procurement, strategy, and executive planning functions.
Because the nitrocellulose market rewards foresight and penalizes delay, the study is designed for immediate operational integration. Whether your mandate involves renegotiating supply contracts, evaluating regional manufacturing entry, optimizing product-grade mix, or stress-testing exposure to raw material volatility, the report provides the structured intelligence required to act decisively.
Executive teams that secure access to the full dataset will be positioned to model outcomes with higher precision, anticipate inflection points earlier, and align commercial strategy with the realities shaping the next phase of market evolution.
For detailed analysis of this topic, please visit the official page: Nitrocellulose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


