



PW Consulting Forecasts SRAM Market to Reach $684 Million by 2032 with 5.23% CAGR

Navigating the SRAM Landscape: Strategic Imperatives for 2026 and Beyond
The Static Random Access Memory (SRAM) market stands at a critical inflection point. As foundational infrastructure for high-performance computing, automotive electronics, and industrial automation, SRAM remains a vital component in the global semiconductor value chain. However, the combination of shifting supply dynamics, intensifying competitive pressures, and evolving end-use demands requires stakeholders to look beyond headline figures and understand the structural forces shaping the trajectory through 2032.
This analysis introduces our latest comprehensive market research on the SRAM sector, designed specifically for executive teams, product strategists, and investment committees who require actionable intelligence to navigate an increasingly complex environment. Rather than offering static snapshots, the study maps the interplay between technological evolution, regulatory scrutiny, and regional supply realignment, providing a decision-ready framework for 2026 planning and beyond.
Static Random Access Memory (SRAM) Market
Market Trajectory: Sustained Expansion Amid Structural Shifts
The SRAM market has demonstrated consistent growth over the past half-decade, transitioning from a post-pandemic recovery phase into a more mature expansion cycle. Starting from a baseline of approximately 380.0 million USD in 2020, the sector progressed through a period of accelerated adoption, reaching 444.43 million USD by 2023 and crossing the 460 million USD threshold in 2024. By the 2025 base year, total market valuation settled at 480.0 million USD, reflecting stabilized demand patterns and incremental capacity adjustments across key manufacturing hubs.
Looking forward, the forecast period spanning 2026 through 2032 projects a compound annual growth rate of 5.23 percent. This trajectory suggests a move toward the 684.0 million USD range by the end of the outlook window. Importantly, this growth is not linear or uniformly distributed. The market is experiencing divergent forces: sustained pull from high-speed computing applications coexists with supply-side normalization that is gradually easing earlier bottlenecks. For strategic planners, the key takeaway is that volume expansion will be accompanied by margin recalibrations, pricing oscillations, and shifting value capture across product tiers.
The research isolates these dynamics through scenario-based modeling that accounts for both baseline adoption curves and disruption triggers, such as capacity ramp-ups, component substitution pressures, and evolving procurement cycles. Stakeholders who rely on single-point forecasts risk misaligning capital allocation, production scheduling, and partnership strategies with the actual cadence of market evolution.
Segmentation Architecture: Where Value Is Concentrated
A rigorous examination of the SRAM market requires a multi-dimensional segmentation lens. Our study breaks down the landscape across product architecture, end-use application, and geographic footprint, revealing how specific sub-segments are driving disproportionate share and shaping competitive positioning.
Product Architecture Dynamics
Within the type-based segmentation, distinct performance and cost profiles are redefining buyer preferences. Synchronous SRAM configurations continue to command significant share, driven by their alignment with high-clock-speed architectures and low-latency memory hierarchies. Asynchronous variants maintain relevance in cost-sensitive and latency-tolerant deployments, particularly where design simplicity and power efficiency outweigh raw throughput requirements. A broader category of alternative and specialized SRAM implementations is also gaining traction, reflecting ongoing innovation in peripheral integration, radiation-hardened designs, and application-specific memory subsystems.
The report evaluates how these architectural distinctions influence pricing premiums, qualification timelines, and supply commitments across different buyer profiles. Decision-makers will find explicit guidance on when to prioritize synchronous architectures for performance-critical roadmaps versus when asynchronous or hybrid approaches provide more favorable total cost of ownership.
Application-Driven Demand Patterns
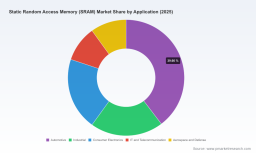
SRAM consumption is not monolithic; it is shaped by the distinct design cycles, qualification standards, and volume profiles of each end market. Automotive applications represent a substantial demand pool, propelled by advanced driver-assistance systems, in-vehicle connectivity, and the proliferation of electronic control units requiring fast, reliable memory buffering. Industrial deployments contribute a meaningful share, supported by factory automation, edge instrumentation, and ruggedized environments where memory endurance and temperature resilience are paramount.
Consumer electronics, IT and telecommunication infrastructure, and aerospace and defense collectively form additional demand pillars. Each vertical presents a unique combination of volume intensity, specification strictness, and procurement behavior. For example, telecommunications and data networking contexts increasingly favor high-speed SRAM solutions that can sustain throughput in AI-adjacent workloads, while aerospace and defense programs emphasize radiation tolerance and long lifecycle availability. The study maps these application-level pressures to procurement strategy recommendations, enabling teams to anticipate qualification timelines, forecast volume ramps, and structure supply agreements accordingly.
Geographic Footprint and Regional Realignment
Regional dynamics are undergoing a subtle but consequential recalibration. North America and Asia Pacific continue to anchor significant portions of market activity, reflecting the concentration of advanced electronics manufacturing, semiconductor design activity, and high-performance computing deployment. Europe and Latin America contribute substantive demand, influenced by regional industrial bases, automotive clusters, and localized supply chain strategies. The Middle East and Africa represent an emerging frontier where infrastructure modernization and defense-related electronics programs are gradually expanding addressable demand.
The report avoids simplistic regional scorecards. Instead, it examines how trade policy considerations, onshore manufacturing incentives, logistics complexity, and local content expectations are reshaping regional sourcing strategies. This regional granularity enables multinational teams to evaluate where to prioritize supplier diversification, where to invest in qualification partnerships, and where pricing differentials offer structural advantages.
Competitive Landscape: Concentration, Differentiation, and Strategic Positioning
The SRAM market exhibits notable concentration, with a small group of established players accounting for the majority of share. The research quantifies this dynamic through concentration metrics that highlight the extent to which top-tier firms dominate supply relationships, qualification pipelines, and volume procurement. Such concentration has practical implications for buyers and suppliers alike: it influences negotiation leverage, roadmap visibility, and the speed at which new entrants can gain traction.
Among the companies profiled, GSI Technology, Inc., based in San Jose, California, exemplifies a focused strategy centered on high-performance and radiation-hardened SRAM products tailored for networking, aerospace, and defense applications. Its market positioning reflects a deliberate emphasis on specialized performance requirements rather than broad commodity volume. The company’s trajectory also illustrates how high-speed SRAM solutions are benefiting from sustained demand pull from AI data center environments, where latency sensitivity and throughput stability are critical design constraints.
The study goes beyond company profiles to assess competitive behavior across several dimensions. It evaluates how incumbents are defending positions through lifecycle management, qualification leverage, and application-specific engineering support. It also examines where differentiation is increasingly tied to reliability certifications, supply assurance commitments, and integration support rather than raw memory specifications alone. For organizations evaluating supplier relationships or assessing potential partnership structures, the report provides a structured view of who holds advantage in which context, and why.
Industry Dynamics: Regulation, Supply Evolution, and Demand Catalysts
The SRAM market does not operate in a vacuum. Several concurrent developments are actively reshaping the operating environment and will influence strategic options throughout the forecast period.
Regulatory and legal scrutiny has emerged as a material consideration. Investigations have been initiated into multiple SRAM manufacturers regarding alleged antitrust violations, signaling heightened attention to competitive conduct within concentrated semiconductor segments. For enterprise buyers, this introduces both risk management requirements and potential opportunities to renegotiate terms as market conduct is examined. For suppliers, compliance posture and documentation rigor are becoming integral to maintaining customer confidence and avoiding disruption.
On the supply side, manufacturing strategies are evolving. Certain players are expanding onshore capacity for related memory technologies under strategic agreements, reflecting a broader push toward supply resilience and localized production capabilities. While these initiatives often target adjacent product lines, they influence the broader memory ecosystem by altering capacity availability, cost structures, and the geographic distribution of manufacturing assets. The report tracks these shifts to help organizations anticipate where supply reassignment may create advantages or constraints for SRAM procurement.
Demand-side catalysts remain powerful. AI data center expansion continues to drive sustained interest in high-speed SRAM solutions, with select suppliers reporting significant year-over-year revenue growth in recent quarters. This growth underscores the strategic importance of SRAM within performance-sensitive compute architectures, even as the market also encounters pricing pressures from improving supply conditions. Sector analysis indicates that price trajectories may face downward adjustment as supply improves, with notable declines projected in specific quarters. For procurement and product planning teams, this underscores the value of timing-aware sourcing strategies rather than static pricing assumptions.
Taken together, these dynamics create a market environment where strategic agility is a competitive necessity. The report integrates each of these forces into a coherent narrative, enabling readers to evaluate how regulatory exposure, supply realignment, and application-driven demand will interact over the planning horizon.
What the Research Delivers: An Executable Intelligence Framework
This market research is structured to move beyond descriptive summaries and toward decision-grade analysis. The study is organized to support a range of strategic use cases, including product roadmap planning, procurement optimization, competitive benchmarking, and investment prioritization.
Content coverage includes a thorough segmentation analysis across type, application, and region, supported by scenario-based projections that account for both baseline adoption and disruption-driven variance. The report also contains a detailed competitive assessment that evaluates positioning, differentiation levers, and concentration implications across the leading players. Beyond structure and sizing, the analysis incorporates macro and regulatory developments, translating them into practical implications for supply strategy, risk management, and go-to-market planning.
Operational tools within the study include procurement timing guidance in the context of projected price movements, supplier evaluation criteria aligned with application-specific requirements, and regional sourcing considerations that factor in trade dynamics and manufacturing geography. For R&D and engineering leadership, the report maps technology trajectory signals to product planning horizons, helping teams determine where performance-oriented SRAM architectures provide durable advantage and where cost-optimized alternatives better match demand profiles.
Magneto Resistive RAM (MRAM) Market
Importantly, the research is designed to be actionable without being prescriptive in a one-size-fits-all manner. Instead, it provides the analytical scaffolding for organizations to test assumptions, compare alternatives, and select strategies that fit their specific exposure to automotive, industrial, computing, telecom, and defense segments.
Strategic Implications for 2026 Decision-Making
The SRAM market in 2026 will reward organizations that treat memory procurement and product integration as strategic levers rather than tactical costs. Several implications emerge clearly from the current trajectory.
First, timing and flexibility matter more than ever. With supply conditions improving and price movements projected in specific periods, rigid long-term commitments may leave value on the table or expose teams to avoidable risk. Scenario-aware sourcing strategies, tiered supplier portfolios, and qualification-ready alternatives can provide resilience while preserving optionality.
Second, application-specific differentiation is increasingly decisive. As automotive, industrial, and high-performance computing segments each impose distinct performance, reliability, and lifecycle requirements, suppliers and buyers alike must align SRAM selections with end-use realities rather than generic specifications. The report provides the mapping needed to make those alignments explicit.
Third, regulatory and supply chain developments should be monitored as strategic variables. Antitrust scrutiny, onshore manufacturing investments, and evolving trade expectations can influence supplier stability, pricing structure, and regional availability. Integrating these factors into planning cycles helps organizations anticipate disruption rather than react to it.
Finally, competitive concentration means that market intelligence must be current and granular. Understanding who holds advantage in which segment, which technologies are gaining traction, and where demand catalysts are intensifying can inform partnership choices, product roadmaps, and investment priorities with greater confidence.
Conclusion: Moving From Context to Competitive Advantage
The SRAM market is undergoing a period of recalibration in which growth remains intact but the path to value capture is becoming more nuanced. Macro expansion is supported by sustained application demand and evolving compute architectures, yet the operating environment is increasingly shaped by supply reassignment, pricing oscillations, regulatory attention, and concentrated competitive dynamics. In this context, high-level market knowledge is necessary but insufficient. Decision-makers need segment-level clarity, scenario-aware projections, and an integrated view of how regulation, supply, and demand interact.
PW Consulting’s SRAM Market Research offers that depth. It is built to support executive planning, procurement strategy, product development alignment, and competitive positioning with a rigorous, forward-looking framework. For teams preparing for 2026 and beyond, the study provides the intelligence required to convert market complexity into informed action.
To explore the full segmentation detail, competitive assessments, regional dynamics, and scenario-based forecasts that underpin this analysis, please access the complete report through our official research portal. The complete intelligence package is available there for organizations ready to integrate SRAM strategy into their broader planning agenda.
For detailed analysis of this topic, please visit the official page: Static Random Access Memory (SRAM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


