



PW Consulting: Hearables Market Hits $215M in 2025, Poised for 6.98% CAGR Through 2032

Hearables Market Strategic Outlook 2026: Navigating the Next Wave of Audio Intelligence
The global hearables market has entered a decisive inflection point. Where early adoption revolved around convenience and basic wireless connectivity, the category now sits at the intersection of consumer electronics, health technology, spatial computing, and artificial intelligence. Market valuation reached approximately 215.0 million USD in 2025, extending a consistent upward trajectory from 163.15 million USD in 2020. Forward projections indicate sustained momentum, with the market advancing toward 234.68 million USD in 2026 and continuing to expand through the end of the forecast period in 2032. This compression of growth timelines, paired with an estimated compound annual growth rate of 6.98 percent across the 2026 to 2032 horizon, signals more than incremental consumer demand. It reflects structural shifts in how audio devices are positioned, manufactured, and integrated into daily workflows, fitness routines, and wellness ecosystems.
For executive teams, product leaders, and investment strategists, this environment demands more than headline figures. The real strategic challenge lies in interpreting what is driving the expansion, where competitive intensity is concentrating, how supply-side disruptions and regulatory shifts are reshaping cost structures, and which product architectures are likely to command premium positioning in the years ahead. The hearables category has matured into a landscape where regional execution, form-factor differentiation, application-specific use cases, and component-level supply chain design all influence margin profiles and market share outcomes. Understanding these layers is no longer optional for organizations seeking to anticipate demand rather than react to it.
Worldwide Consumer and Enterprise Hearables Market
Why a 2026 Decision Framework Requires Granular Intelligence
The period from 2026 onward will be defined by convergence. Manufacturers are no longer competing solely on sound quality or battery endurance; they are competing on integrated sensing, adaptive noise management, hearing health functionality, and seamless ecosystem compatibility. At the same time, cost pressures from tariffs, raw material constraints, and semiconductor sourcing volatility are forcing more deliberate portfolio planning. In this context, strategic decision-making depends on knowing not just that the market is expanding, but where value is accumulating and which structural headwinds require preemptive mitigation.
Hearables Market
Several forces make this the right moment for a detailed market assessment. First, consumer expectations are shifting toward devices that function as always-on companions for music, communication, fitness tracking, and environmental awareness. Second, enterprise and professional users are driving demand for hearables that support hybrid collaboration, call clarity, and platform integration. Third, the hearing health overlap is creating new product pathways and regulatory considerations that blur the line between consumer audio and assistive technology. Each of these vectors alters the competitive equation, and each requires a precise reading of market architecture rather than broad directional assumptions.
Evidence of the market's accelerating complexity can already be seen in recent product introductions. At CES 2026, for example, multiple launches emphasized open-ear designs and certified noise reduction as practical solutions for daily use and athletic applications. These releases reflect a broader industry movement toward comfort-centric ergonomics, situational awareness, and hybrid use cases that span commuting, outdoor activity, and workplace environments. The strategic implication is clear: successful product roadmaps will need to account for lifestyle integration, environmental robustness, and user-specific acoustic preferences, rather than treating audio performance as a standalone specification.
What the Research Delivers: Analytical Depth Designed for Executive Action
Our latest Hearables Market study is built to translate category momentum into decision-grade intelligence. The analysis moves beyond high-level demand signals to examine the structural mechanisms shaping growth, including segmentation patterns, regional execution dynamics, and the competitive behaviors that determine which players secure durable advantage. The report is designed to support three core planning functions: market entry and expansion evaluation, product portfolio strategy, and supply chain risk positioning.
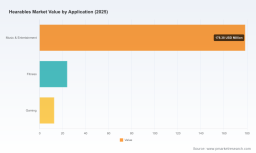
To accomplish this, the study provides a detailed breakdown of market structure across multiple analytical dimensions. It maps how distinct device categories are contributing to overall revenue evolution, allowing stakeholders to understand where volume concentration and differentiation opportunities intersect. It also examines application-driven demand patterns, clarifying how usage contexts such as music and entertainment, fitness-oriented listening, and gaming-related audio consumption influence product requirements, pricing tolerance, and lifecycle expectations. Regional demand is similarly assessed to identify where consumption is scaling most rapidly and where market maturity, channel dynamics, and competitive saturation require different strategic approaches.
Equally important, the report analyzes market concentration to reveal how revenue is distributed among leading participants. This concentration analysis provides a practical lens for evaluating competitive vulnerability, partnership opportunities, and the extent to which the market remains open to new entrants or specialized niche players. In a category where scale advantages, brand equity, and technology integration all matter, understanding concentration patterns helps decision-makers gauge the realism of aggressive growth targets and the likelihood of consolidation pressure.
Beyond segmentation and concentration, the research connects product-level developments with broader industry dynamics. It examines how active noise management, open-ear and bone-conduction form factors, AI-enabled acoustic optimization, and premium sound reproduction are reshaping consumer value propositions. It also assesses how professional-grade communication features, hearing-health integration, and ecosystem alignment influence enterprise and hybrid-use demand. These product trends are evaluated not as isolated innovations, but as strategic signals that indicate where future revenue streams are likely to be anchored.
Competitive Landscape: Strategic Positioning Among the Leaders
The competitive environment is defined by a mix of ecosystem-driven incumbents, audio specialists, and component-level technology providers whose designs influence downstream product capabilities. Apple continues to reinforce its position through the AirPods lineup, including the AirPods 4 and AirPods Pro models built around the H2 chip. Its strategy emphasizes integrated hardware-software performance, open-ear ANC design exploration, and the expansion of hearing health features that extend the device's role beyond entertainment. By linking acoustic performance with platform ecosystem benefits, Apple maintains a strong reference point for premium consumer expectations.
Bose remains focused on immersive listening experiences through offerings such as the QuietComfort Ultra Earbuds and Ultra Open Earbuds. Its approach highlights ActiveSense AI ANC and OpenAudio technology, targeting users who value environmental adaptability and high-quality sound in both enclosed and open-ear configurations. Bose's continued investment in noise management and comfort-oriented design reinforces its relevance in premium segments where acoustic refinement and wearability are central purchase drivers.
Samsung has pushed its Galaxy Buds series toward AI-optimized performance, high-resolution audio, and ANC 2.0 capabilities, with the Galaxy Buds 4 Pro representing the company's current emphasis on connected device intelligence and refined sound reproduction. Its strength lies in aligning hearables with a broader mobile ecosystem and in delivering feature-rich products that serve both consumer and lifestyle use cases. Samsung's positioning illustrates how hardware differentiation and ecosystem integration can reinforce one another in a crowded market.
Sony continues to compete through the WF-1000XM series, where advanced noise cancellation and high-fidelity sound reproduction remain central to the brand's value proposition. Sony's strategy underscores the enduring importance of acoustic excellence and feature credibility, particularly among users who treat earbuds and headphones as serious audio equipment rather than accessories alone. In a market increasingly shaped by hybrid usage, Sony's emphasis on sound quality helps maintain a distinct premium lane.
Across the broader competitive field, a range of specialized players is expanding the boundaries of what hearables can deliver. Anker Innovations has advanced open-ear designs such as the Soundcore AeroFit 2, emphasizing custom-molded fit, long battery life, and AI compute-in-memory chip architecture. Shokz has focused on open-ear and bone-conduction categories, including the OpenRun Pro 2 with an IP55 rating, the OpenFit Pro with TÜV-certified noise reduction, and the OpenDots clip-on earbuds. These products illustrate how ergonomic innovation and environmental durability can open new usage scenarios, particularly for active and outdoor consumers.
Professional and enterprise-oriented brands are also shaping the market's direction. Jabra's Evolve2 and Elite series are positioned around professional-grade earbuds with ANC and seamless Microsoft Teams integration, highlighting the growing importance of collaboration-ready audio in hybrid work settings. Sennheiser continues to emphasize premium sound quality and noise cancellation through the Momentum True Wireless series, reinforcing a reputation for audio fidelity. Philips is extending the hearables frontier into hearing health with Lifeline and BT series hearing aids integrated with hearables technology, an approach that blurs consumer and medical-adjacent categories and introduces new design, compliance, and market-access considerations.
Underpinning many of these product strategies is the role of component and reference-design suppliers. Airoha Technology, as a MediaTek subsidiary, supplies Bluetooth audio SoCs and reference designs used in TWS earbuds and headphones, influencing how quickly manufacturers can bring power-efficient, feature-rich products to market. This supplier dimension matters because competitive timing, feature adoption, and cost efficiency are often determined long before the consumer sees the final product. In practical terms, the hearables market is not only a contest of brand and design; it is also a contest of component architecture and development velocity.
Market Dynamics: Supply Constraints, Tariffs, and Strategic Realignment
The growth outlook cannot be separated from the operational pressures currently affecting the industry. Raw material disruptions have emerged as a meaningful constraint, particularly where silicon supply shortages linked to the Russia-Ukraine conflict have affected MEMS microphone production. These disruptions have delayed deliveries and increased component prices, creating cost volatility for manufacturers that depend on precision acoustic components. Compounding this issue, tariff actions have added further complexity to sourcing and pricing strategies. In the U.S. market, substantial tariffs on Chinese products have disproportionately affected wireless headphones and smart home devices, with manufacturers paying significant tariff costs in 2025. Additional tariff exposure on Chinese MEMS and PCB suppliers has intensified the push toward regional diversification and raised costs for microphone manufacturers.
At the same time, regulatory adjustments are reshaping sourcing assumptions. Executive actions affecting certain tariff measures on integrated circuits have altered the cost and availability landscape for audio component sourcing, creating a moving target for procurement teams and product planners. The cumulative effect is a market environment in which pricing, margin planning, and supply continuity must be modeled with greater flexibility. For companies operating at scale, this means diversification of supplier bases, reassessment of bill-of-materials exposure, and closer coordination between design engineering and procurement. For newer or smaller entrants, it means that barriers to cost-efficient scaling may be higher than headline demand trends suggest.
These dynamics also have strategic implications for product architecture. When component availability and tariff exposure influence cost structures, design teams often need to evaluate alternative acoustic configurations, material selections, and manufacturing footprints. The result is a market in which operational resilience is becoming part of competitive strategy. Companies that treat supply chain design as a secondary concern risk losing margin control; companies that integrate sourcing risk into product planning can protect price positioning and improve launch reliability. In an environment where revenue is expanding but input costs are volatile, the ability to manage upstream exposure is increasingly a differentiator.
What 2026 Decision-Makers Should Look For Next
The hearables market is not simply growing; it is being reshaped by overlapping technology trends, changing consumer expectations, and a more demanding operating environment. That combination creates opportunity, but only for organizations that can distinguish between temporary headwinds and structural shifts. The most effective decisions in 2026 will come from understanding where demand is most durable, which product categories are gaining strategic relevance, how competitive concentration affects market access, and where supply-side pressures are likely to influence pricing and margin outcomes.
This report is designed to provide that clarity. It offers a detailed mapping of market size evolution, segmentation behavior, concentration patterns, competitive positioning, and industry dynamics that affect execution risk. By integrating product-level developments with macroeconomic and regulatory context, it gives stakeholders a practical foundation for planning product roadmaps, evaluating expansion scenarios, and anticipating the forces that will shape the next phase of category growth.
For organizations that need to move from market awareness to market advantage, the full study provides the underlying detail necessary to support informed investment, portfolio design, and competitive positioning. The complete analysis, including deeper segmentation assessments and regional demand patterns, is available through the full report.
For detailed analysis of this topic, please visit the official page: Hearables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


