



PW Consulting: Facility Management Market to Hit $3.38T by 2032, Driven by 6.8% CAGR

Unlocking Strategic Value in the Facility Management Services Market: A 2026 Outlook
The Facility Management (FM) Services Market is undergoing a structural shift that extends far beyond routine maintenance. What was once viewed as a back-office support function has evolved into a strategic lever for operational efficiency, sustainability compliance, and workplace experience. As organizations enter 2026, the ability to navigate this evolving landscape is no longer optional—it is a core competitiveness. Our latest market research provides a comprehensive, decision-ready blueprint for executives who need to anticipate demand shifts, optimize procurement strategies, and align facility portfolios with broader corporate objectives.
This report is not a static snapshot. It is a forward-looking analytical framework designed to translate market complexity into actionable intelligence. Whether you are a real estate operator, a corporate facilities leader, a public institution planner, or an investor evaluating service-provider exposure, the insights herein are calibrated to support 2026 strategic planning cycles.
Macro Trajectory: What the Numbers Reveal for 2026 Planning
The market has demonstrated consistent expansion over the past half-decade, and the momentum is projected to intensify through the end of the decade. Drawing on a historical baseline spanning 2020 to 2025 and a forecast horizon extending through 2032, our analysis places the overall market valuation at approximately 2.15 billion USD in 2025, with a projected climb to exceed 2.28 billion USD in 2026. The trajectory continues upward, reaching nearly 3.4 billion USD by 2032, supported by a compound annual growth rate of 6.8 percent.
These figures are not merely historical artifacts; they are signals. The sustained expansion reflects a confluence of operational digitization, regulatory tightening, and the reorganization of how organizations consume space. For strategic planners, the implication is clear: FM is no longer a discretionary cost line but a mission-critical service category with measurable impact on asset performance, tenant retention, and compliance readiness. The 6.8 percent CAGR underscores a market that is expanding faster than many traditional service segments, creating both opportunity and fragmentation risk for organizations that lack a disciplined sourcing or partnership strategy.
Structural Dimensions: How the Market Is Organized
Understanding where growth is concentrated requires a clear view of how the market is segmented. Our research disaggregates the landscape across multiple operational dimensions, enabling leaders to identify which service categories, user segments, and geographies align with their organizational footprint and risk tolerance.
The service architecture divides into core operational categories, each with distinct demand drivers. Hard services—encompassing physical infrastructure maintenance, HVAC, electrical, plumbing, and structural upkeep—represent the backbone of facility operations. Soft services, including cleaning, security, concierge, workplace experience, and administrative support, increasingly intersect with employee retention and brand perception. A third tier captures specialized and emerging service lines that are growing in relevance as organizations pursue integrated solutions rather than siloed contracts. Each category carries different margin profiles, labor intensity, and technology adoption curves, making the segmentation essential for contract structuring and vendor evaluation.
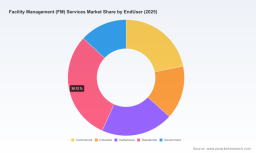
End-user demand is similarly diversified. Commercial portfolios drive consistent volume, but industrial facilities, institutional campuses, residential complexes, and government infrastructure each present unique compliance requirements, service-level expectations, and procurement cycles. This diversification means that a one-size-fits-all FM strategy is increasingly inadequate. Organizations must map their asset mix to the appropriate service tier, anticipate sector-specific regulatory pressures, and calibrate outsourcing versus in-house decisions accordingly.
On a regional level, the market exhibits pronounced geographic variation in maturity, demand density, and service complexity. Some regions reflect established, service-intensive environments where competition is fierce and differentiation hinges on technology and sustainability credentials. Others are experiencing faster relative growth as urbanization, infrastructure modernization, and regulatory adoption accelerate FM penetration. For multinational operators and regional portfolios alike, geographic context shapes everything from pricing dynamics to talent availability and delivery models.
Market Dynamics: The Forces Reshaping FM Execution in 2026
Behind the headline growth lies a set of operational pressures that are redefining how FM services are delivered, priced, and governed. These dynamics are not peripheral; they are central to contract viability, service quality, and long-term portfolio performance.
-
Labor scarcity and cost escalation. Workforce participation trends are projected to decline, tightening the availability of skilled HVAC, electrical, and plumbing technicians who are essential to facility operations. The resulting scarcity inflates wage expectations and, in some cases, delays maintenance projects by up to a quarter. For operators, this translates into tighter scheduling windows, higher service costs, and greater exposure to downtime if contingency planning is insufficient.
-
Regulatory and sustainability mandates. Government building maintenance regulations and corporate sustainability goals are accelerating demand for specialized decarbonization services and comprehensive energy management solutions. Organizations are no longer treating environmental compliance as a separate initiative; it is becoming embedded in facility operations, influencing equipment upgrades, monitoring practices, and vendor selection criteria.
-
Standards and certification as trust signals. Frameworks such as ISO 41001 are increasingly referenced as providers seek to demonstrate compliance with requirements for effective and efficient facility management delivery. Certification and documented operational discipline are becoming differentiators in competitive bids, particularly for institutional and government contracts where accountability and auditability carry heightened weight.
-
Digital integration and data-enabled operations. The market is steadily shifting toward technology-enabled service models. Spatial data, digital twins, connected building platforms, and integrated software tools are moving from pilots to production deployments. This transition is reshaping how providers forecast maintenance needs, optimize labor deployment, and report on energy and performance metrics.
These dynamics create a dual challenge for decision-makers. On one side, they raise the bar for service quality and compliance. On the other, they open pathways for providers and clients who can operationalize technology, standardize processes, and demonstrate measurable outcomes. The organizations that thrive in 2026 will be those that treat FM as an integrated system rather than a collection of discrete tasks.
Facility Management (FM) Services Market
Competitive Landscape: Who Is Shaping the Market and How
The FM services market features a broad mix of established facility operators, integrated service providers, and technology platforms that increasingly blur the line between software and services. Our research profiles the core companies that are defining competitive benchmarks, expanding service portfolios, and repositioning themselves around workplace experience, sustainability, and operational integration.
Among the most prominent global players, several themes emerge. Large U.S.-based commercial real estate and facilities firms are expanding beyond traditional management into integrated workplace and building operations models. European and international service groups are emphasizing workplace experience, sustainability, and cross-regional delivery capabilities. Specialized contractors continue to anchor hard services and property support in commercial, industrial, and public-sector environments. At the same time, technology-oriented companies are embedding software, platforms, and analytics into FM delivery, enabling more predictive maintenance, energy oversight, and operational transparency.
The competitive field is not static. Recent activity shows a clear pattern of consolidation, capability expansion, and targeted partnerships designed to capture demand in high-growth verticals and regions.
-
In early 2025, one major global services provider secured multiple outsourcing contracts for integrated workplace and maintenance services, reinforcing its footprint in combined service delivery.
-
Also in early 2025, a leading U.S.-based commercial services firm completed an acquisition to establish a new building operations and experience segment, signaling a strategic pivot toward more holistic portfolio management.
-
A global services group expanded its U.S. presence through an acquisition designed to strengthen cross-selling opportunities in integrated facility management.
-
A partnership formed in mid-2025 brought spatial data capabilities into digital twin modeling for North American industrial portfolios, highlighting the growing role of data-driven building representation in operations and planning.
-
Later in the year, a new decarbonization and energy management service launch targeted North American logistics and warehousing, illustrating how FM providers are tailoring offerings to sector-specific sustainability and operational demands.
Worldwide HVAC Cleaning Services Market
These developments matter for 2026 strategy because they show where incumbents are placing bets. Acquisitions and partnerships are not only reshaping provider capabilities; they are also redefining the value propositions available to clients. Organizations evaluating FM partners should look beyond contract pricing and assess whether providers have the integrated capabilities, technology fluency, and sector-specific experience to support long-term operational goals.
What Our Research Delivers: A Practical Decision Toolkit
This report is built to support execution, not just awareness. It translates market structure, growth trajectory, and competitive activity into tools that procurement, operations, real estate, and executive teams can use immediately.
Within the full study, readers will find detailed coverage of service category dynamics, end-user demand patterns, and regional variation, structured to help leaders map their portfolios against market realities. The analysis examines how hard services, soft services, and emerging service tiers interact with labor constraints, regulatory pressure, and technology adoption. It also evaluates the strategic implications of recent provider moves, including consolidation, capability expansion, and digital partnerships, so that organizations can anticipate shifts in vendor behavior and service availability.
Beyond descriptive analysis, the report provides an operational lens on market concentration and competitive positioning. By examining how demand is distributed and how leading providers differentiate, the research helps clients assess sourcing risk, evaluate partnership fit, and identify where specialized capabilities may create advantage. The goal is to equip decision-makers with a clear framework for contract strategy, vendor selection, service integration, and portfolio-level planning.
Why This Research Matters for 2026 Decisions
The Facility Management Services Market is entering a phase where strategic foresight yields measurable operational advantage. Growth is steady, but the underlying forces—labor constraints, sustainability mandates, digital transformation, and provider consolidation—are changing the terms of engagement. Organizations that wait for issues to surface in the form of delays, cost overruns, or compliance gaps will find themselves reacting rather than shaping outcomes.
Our research is designed to convert market complexity into clarity. It helps leaders answer the questions that matter in 2026: how to align FM strategy with asset portfolios, which service dimensions deserve priority investment, how to evaluate providers in a consolidating and technology-intensive market, and where regional and sector-specific dynamics are likely to influence cost and delivery. The full report expands on these themes with the depth and structure required for formal planning, procurement reviews, and executive decision-making.
Next Steps for Strategic Leaders
For executives and operational leaders preparing for the 2026 planning cycle, the opportunity lies in moving from general awareness to precise, evidence-based action. The market trajectory, segmentation structure, competitive activity, and operational dynamics outlined here are intended as a foundation—not the final word. The complete study provides the granular analysis, provider profiles, and decision frameworks needed to translate insight into execution.
We invite you to explore the full Facility Management Services Market research to access the detailed intelligence that supports confident, forward-looking decisions. In a market expanding toward sustained multi-billion-dollar scale, the organizations that act with structured insight will be best positioned to manage cost, compliance, and performance in the years ahead.
For detailed analysis of this topic, please visit the official page: Facility Management (FM) Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


