



PW Consulting Projects Oil & Gas Flexible Pipes Market to Hit $2.29B by 2032 with 6.5% CAGR

Flexible Pipes for Oil and Gas Market: Strategic Intelligence for 2026 and Beyond
The global energy infrastructure landscape is undergoing a structural shift, driven by the relentless expansion of deepwater offshore operations and the accelerating substitution of traditional steel components with advanced flexible piping systems. As operators navigate increasingly complex geological challenges and stringent operational standards, the demand for reliable, high-performance flexible pipes has transitioned from a niche requirement to a core strategic imperative. PW Consulting’s latest market study, Flexible Pipes for Oil and Gas Market, provides a comprehensive, data-driven blueprint designed to equip executives, procurement leaders, and strategic planners with the actionable intelligence needed to navigate the 2026–2032 forecast period.
Built on a rigorous analytical framework spanning historical performance from 2020 through 2025 and a forward-looking projection window extending to 2032, this report does not merely catalog market movements. It decodes the underlying mechanics of supply chain resilience, material innovation, regulatory alignment, and competitive positioning. The following overview outlines the strategic architecture of the study, highlights the operational dimensions covered, and demonstrates why this intelligence is essential for capital allocation, risk mitigation, and long-term portfolio planning in the current market cycle.
Macro Trajectory and the 2026 Decision Horizon
The market has demonstrated consistent expansion over the past half-decade, with revenue scaling from 850.0 million USD in 2020 to an estimated 1,480.0 million USD in 2025. This trajectory reflects a compound annual growth rate of 6.5 percent, a pace that underscores the sector’s resilience amid volatile commodity cycles and shifting drilling economics. As the market enters 2026, baseline projections indicate continued momentum, with revenue expected to reach 1,527.5 million USD before accelerating toward a projected 2,292.0 million USD by 2032.
For strategic planners, these figures are more than historical markers; they represent a validated demand curve that must be factored into capacity planning, supplier negotiations, and technology investment roadmaps. The 2026 inflection point is particularly critical. Operators are balancing immediate production targets with long-term decarbonization and efficiency mandates, creating a procurement environment where material selection, system durability, and compliance readiness directly influence total cost of ownership. This report isolates the macroeconomic and sector-specific drivers shaping this transition, enabling decision-makers to align their sourcing strategies with verified growth pathways rather than speculative trends.
Structural Breakdown: Material, Application, and Regional Architecture
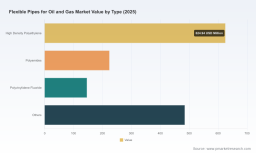
Flexible pipe ecosystems are fundamentally defined by their material composition, deployment environment, and geographic distribution. The study maps these structural layers with precision, examining how polymer-based and composite formulations compete across different operational profiles. High-density polyethylene continues to anchor a substantial portion of the market, valued for its corrosion resistance, manufacturability, and cost efficiency in standard pressure regimes. Parallel to this, polyamides and polyvinylidene fluoride occupy specialized niches where chemical compatibility, temperature tolerance, and mechanical fatigue resistance dictate performance outcomes. Composite and hybrid formulations are also gaining traction as operators seek weight reduction and extended service life in extreme subsea conditions.
Application segmentation reveals a clear operational divide. Offshore deployments dominate the revenue landscape, reflecting the industry’s strategic pivot toward deepwater and ultra-deepwater reserves where rigid piping systems face logistical, installation, and maintenance constraints. Onshore applications, while comparatively smaller in scale, remain vital for midstream transfer, water management, and brownfield retrofits where flexibility reduces civil engineering overhead and accelerates commissioning timelines.
Geographically, the market exhibits a pronounced concentration in established energy corridors, with North America commanding the largest revenue share, followed by the Asia Pacific region and Europe. Latin America and the Middle East and Africa represent emerging growth vectors, shaped by basin development cycles, regulatory modernization, and increasing foreign direct investment in upstream infrastructure. The report’s regional analysis moves beyond headline figures to examine supply chain localization trends, logistics constraints, and country-specific certification requirements that influence market entry timing and partnership structuring.
Oil and Gas Hoses Market
Competitive Landscape and Strategic Positioning
The flexible pipe sector is characterized by a moderately concentrated competitive field, with the top three players collectively commanding 45.2 percent of market revenue and the top five firms capturing 55.8 percent. This structure reflects a market where scale, certified engineering capability, and long-term operator relationships serve as formidable barriers to entry. Yet, the landscape is far from static. Technological differentiation, material innovation, and targeted contract wins are continuously reshaping competitive hierarchy.
Flexible Pipes for Oil and Gas Market
TechnipFMC maintains its position as a global leader in the design, manufacture, and supply of flexible pipes for subsea oil and gas applications, including risers and flowlines. Its operational footprint and engineering depth have been reinforced by recent contract awards, including two substantial engagements by Petrobras to design, engineer, and manufacture flexible gas injection risers and risers/flowlines for the Campos Basin. National Oilwell Varco continues to expand its portfolio of flexible pipe systems for offshore oil and gas, spanning shallow and deepwater applications. The company’s strategic focus on high-pressure performance was underscored by a new product line launch in mid-2025, followed by a pre-commercial agreement with Petrobras to develop CO2-resistant flexible pipes tailored for deepwater high-CO2 environments.
Baker Hughes supplies flexible pipe systems for subsea and onshore oil and gas, covering risers, flowlines, and jumpers, and has actively showcased its latest system architectures at major industry forums such as the Offshore Technology Conference in 2026. Strohm, formerly known as Airborne Oil & Gas, has carved a specialized position through the manufacture of bonded thermoplastic composite pipes engineered for high-performance subsea applications. SoluForce, operating under Pipelife Nederland B.V., focuses on high-pressure flexible composite pipes for oil, gas, and water transport, leveraging reinforced thermoplastic technology to address pressure cycling and fatigue challenges.
Magma Global produces m-pipe® carbon fibre composite pipes specifically developed for subsea oil and gas risers and flowlines, offering weight and corrosion advantages in demanding environments. ContiTech extends its industrial hose and flexible pipe expertise into oil and gas applications, while Shawcor’s Flexpipe Systems division develops and manufactures flexible pipe systems designed for oil and gas pipeline integration. Prysmian Group rounds out the competitive field by supplying cables and flexible pipes for subsea and onshore production systems, emphasizing integrated infrastructure solutions.
The report’s competitive benchmarking module examines pricing architectures, technological roadmaps, contract win patterns, and regional manufacturing footprints. It identifies where incumbents hold structural advantages and where emerging players are creating disruption through material substitution, modular design, or targeted service delivery models. For executives evaluating vendor consolidation, partnership opportunities, or in-house capability development, this analysis provides a clear map of competitive vulnerabilities and strategic white space.
Operational Intelligence: Dynamics, Compliance, and Cost Architecture
Market performance in the flexible pipe sector is tightly coupled to a matrix of regulatory, material, and operational variables. The study dissects these dynamics to reveal how they influence margin structures, project timelines, and procurement risk. ISO 13628 series standards govern the design and operation of unbonded flexible pipe systems for subsea production, establishing baseline requirements for structural integrity, fatigue resistance, and environmental compatibility. Complementing this, API 17J certification is required for unbonded flexible pipe systems in oil and gas operations, making compliance readiness a non-negotiable prerequisite for market access and operator approval.
On the cost side, polymer material prices remain subject to fluctuation driven by petroleum derivative markets, directly impacting production costs and margin sustainability. The report quantifies these sensitivities and maps them against contract structures, inventory strategies, and supplier diversification models. It also evaluates how raw material availability, manufacturing lead times, and transportation constraints interact to shape total project economics. Understanding these cost architecture layers is essential for organizations seeking to stabilize procurement spending, negotiate favorable terms, or justify vertical integration initiatives.
Beyond compliance and cost, the study examines the broader industry context that continues to propel demand. Deepwater offshore expansion remains a primary catalyst, as operators pursue reserves in progressively challenging environments where flexible piping offers installation agility, reduced weight, and lower lifecycle maintenance burdens. The ongoing substitution of steel components further accelerates adoption, particularly in riser systems, flowlines, and dynamic applications where mechanical fatigue and corrosion management are critical. These macro trends are layered with project-specific considerations, including water depth, pressure profiles, chemical exposure, and installation methodology, all of which are addressed in the report’s application-focused analysis.
Inside the Report: Methodology, Tools, and Decision-Ready Outputs
PW Consulting’s Flexible Pipes for Oil and Gas Market study is structured to deliver immediate operational value alongside long-range strategic perspective. The report integrates historical revenue tracking, demand forecasting, material and application segmentation, regional mapping, and competitive profiling into a single, coherent intelligence framework. Each section is designed to support a specific decision function, from capital expenditure planning and supplier evaluation to risk assessment and technology investment prioritization.
Key deliverables include a detailed market size and forecast model spanning the 2020–2032 horizon, with clear delineation of base-year baselines and forward projections. Segmentation analysis breaks down revenue distribution by material type, application environment, and geographic region, enabling readers to isolate the segments most relevant to their operational footprint. Competitive profiling maps the strategic positioning of leading manufacturers, highlighting recent contract awards, product launches, pre-commercial agreements, and trade show activations that signal shifting priorities and capability expansions.
The study also incorporates a dynamics module that examines regulatory frameworks, cost drivers, macro trends, and raw material sensitivities, providing context for pricing strategy, compliance planning, and supply chain design. Methodological transparency is maintained throughout, with clear assumptions, data sourcing protocols, and scenario boundaries that allow readers to stress-test projections against their own operational parameters. Supplementary tools, including segmentation cross-references and competitive tracking tables, are integrated to support rapid benchmarking and internal dissemination.
Throughout the report, analysis is anchored in verifiable market mechanics rather than superficial trend statements. The objective is to equip readers with a defensible basis for procurement decisions, partnership evaluations, capacity planning, and technology roadmap alignment. By connecting macro growth signals to granular operational variables, the study enables organizations to move from reactive monitoring to proactive strategy execution.
Strategic Imperatives for 2026 and the Forecast Horizon
As the market advances through the 2026–2032 period, three strategic imperatives will define competitive outcomes. First, procurement organizations must align sourcing strategies with verified demand trajectories and material cost sensitivities, ensuring that contract structures and supplier portfolios can absorb commodity volatility without compromising project economics. Second, engineering and operations teams must prioritize compliance readiness and performance certification, recognizing that regulatory alignment is not merely a technical checkbox but a market access requirement that influences bidding eligibility and operator trust. Third, competitive positioning will increasingly hinge on technological differentiation, whether through composite material adoption, high-pressure system design, CO2-resistant formulations, or integrated infrastructure offerings that reduce installation complexity and lifecycle cost.
PW Consulting’s Flexible Pipes for Oil and Gas Market study provides the foundational intelligence required to navigate these imperatives with confidence. The full report contains the complete dataset, segmentation breakdowns, competitive tracking detail, regional supply chain analysis, and forecasting models that underpin the strategic narrative presented here. Organizations that secure this intelligence will be better positioned to calibrate investment timing, negotiate from a position of informed leverage, and align their flexible pipe procurement and engineering strategies with the realities of a growing, evolving, and increasingly demanding market.
For executives, analysts, and project leaders seeking to convert market complexity into structured decision advantage, the complete study offers the depth, precision, and operational relevance required to act decisively in 2026 and throughout the forecast window.
For detailed analysis of this topic, please visit the official page: Flexible Pipes for Oil and Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


