



PW Consulting: Concrete Mixers Market to Hit $8.51B by 2032, 4.5% CAGR

Strategic Intelligence for the Concrete Mixer Market: Why Our 2026 Industry Report Matters
In an era where industrial equipment markets are shaped by rapid technological adoption, shifting regulatory landscapes, and volatile supply chain dynamics, capital allocation and product roadmap decisions require more than surface-level market sizing. The global concrete mixer market stands at a critical inflection point. Infrastructure stimulus programs, residential and commercial construction rebounds, and the gradual electrification of heavy-duty mobile equipment are converging to reshape competitive positioning and demand patterns across every major geography. Our newly released Concrete Mixers Market research was designed specifically for executives, investors, and procurement leaders who need actionable clarity rather than retrospective summaries. This overview outlines the strategic value embedded in the full study and explains how decision-makers can leverage its findings to navigate the 2026 operating environment with confidence.
A Market in Transition: Trajectory, Scale, and the Decision-Maker’s Lens
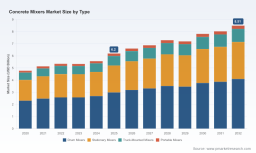
Over the past five years, the concrete mixer sector has demonstrated steady expansion against a backdrop of cyclical construction demand and component cost pressures. Historical data from 2020 through 2025 reflects a market that grew from approximately 4.78 billion USD to 6.2 billion USD, navigating brief contractions while maintaining long-term momentum. Looking ahead, the forecast period from 2026 through 2032 projects continued growth at a compound annual growth rate of 4.5 percent, with projected revenue scaling toward 8.51 billion USD by the end of the forecast window. These figures establish a clear baseline: demand is not merely rebounding, it is structurally evolving.
For strategy teams, the value of these numbers lies not in the headline but in the underlying drivers. The transition from legacy mechanical systems to smarter, lighter, and more efficient mixing platforms is reshaping unit economics. Simultaneously, the competitive intensity of the sector is evident in market concentration metrics, where the top three players account for roughly 45 percent of revenue and the top five capture approximately 60 percent. Such concentration suggests both the presence of established incumbents with scale advantages and meaningful room for disruptors targeting niche applications, regional gaps, or specific operational pain points such as licensing constraints, emissions compliance, and on-site precision.
Raw material volatility, particularly in steel pricing, has introduced meaningful variability in production costs for critical components including drums and chassis. At the same time, procurement validation processes from state departments of transportation continue to standardize approved admixtures and accessories, reinforcing the importance of compliance-ready equipment specifications. Regulatory signals also warrant close attention. In key jurisdictions, energy policy assessments have highlighted that commercially viable zero-emission concrete mixer trucks remain unavailable as of 2026, underscoring the strategic horizon for electrification and alternative powertrain investments. These dynamics do not merely influence costs; they redefine which product architectures will win procurement approvals, fleet adoption, and long-term service contracts.
Inside the Research: Operational Content Built for Execution
This study was structured to support concrete decision-making rather than abstract observation. Readers will find a comprehensive mapping of the market across the primary axes that matter to product planning, channel strategy, and competitive positioning. The report examines segment-level demand characteristics across mixer architectures, application environments, and regional operating conditions, providing a structured lens through which to evaluate where growth is most durable and where margin pressure is most likely to emerge.
Concrete Mixers Market
Beyond segmentation, the analysis delivers an actionable view of the competitive landscape. Profiles of leading manufacturers and emerging specialists are synthesized to highlight differentiators in product design, service ecosystems, and market focus. Rather than treating competition as a static roster, the research connects company positioning to real-world developments that shape buyer preferences. This includes attention to product launches, technology integrations, and event-driven showcases that signal where incumbents are doubling down and where new entrants are carving out defensible positions.
The report also integrates market dynamics that frequently fall outside conventional sizing exercises but carry direct implications for commercial strategy. Material cost behavior, regulatory developments, procurement validation practices, and reimbursement frameworks are examined for their influence on demand elasticity, total cost of ownership, and equipment selection criteria. By linking these forces to segment and regional behavior, the study equips readers to anticipate where pricing power may shift, where specification requirements may tighten, and where operational efficiency will become a decisive competitive advantage.
Worldwide Self Loading Concrete Mixers Market
Competitive Landscape: Leaders, Specialists, and the Shape of Differentiation
The competitive field in concrete mixing equipment is defined by a mix of global heavy-equipment brands, regional specialists, and technology-focused innovators. Large-scale manufacturers continue to anchor the market with broad product portfolios spanning mixer trucks, batching systems, and heavy-duty mobile equipment. Their strength lies in distribution reach, fleet-scale support, and the ability to align mixing solutions with broader construction and infrastructure workflows. For buyers managing large pours, long haul distances, and stringent uptime requirements, these players often serve as default procurement options.
At the same time, a distinct layer of specialists is reshaping expectations around on-site precision, operational flexibility, and regulatory convenience. Volumetric mixing approaches, portable continuous systems, and lightweight configurations are gaining relevance among residential, utility, and mid-sized commercial producers who prioritize exact dosage control, reduced mobilization constraints, or simplified licensing requirements. In this context, product innovation is not only about durability or capacity; it is increasingly about reducing friction in the customer’s operating model. Innovations that improve visibility during transport, enable smaller crews, or reduce licensing burden are becoming meaningful differentiators in competitive bids and repeat purchase decisions.
Recent developments reinforce this direction. Attention to electrification and hybrid platforms reflects a growing demand for efficiency and emissions reduction, even in the absence of fully commercialized zero-emission mixer trucks in some major markets. Parallel innovation in real-time monitoring and drum-level intelligence points to a broader shift toward connected equipment, where transport visibility and quality control are integrated into the hardware itself. Showcase activity at major industry events has also highlighted refreshed model lines with advanced drivetrain and chassis characteristics, signaling that conventional heavy-duty platforms are being refined rather than abandoned. Collectively, these moves illustrate a market where incumbents and challengers are competing on multiple fronts: scale, specialization, technology, and total cost of ownership.
2026 Decision Framework: Turning Macro Visibility into Strategic Action
For executives evaluating market participation, capacity expansion, product development, or procurement strategy, the immediate question is not whether the concrete mixer market is growing, but where the most defensible opportunities reside in 2026 and beyond. The research is built to answer that question through disciplined analysis rather than generalized optimism. Several strategic themes emerge consistently across the data and qualitative context.
- Segment selection matters more than aggregate growth. Demand patterns differ substantially across mixer types and application environments. Organizations that align product portfolios with the most stable and highest-value use cases can better withstand component cost fluctuations and cyclical construction variance.
- Total cost of ownership is becoming a decisive differentiator. With steel price volatility affecting component costs and regulatory signals pointing toward future emissions constraints, buyers are increasingly weighing operating efficiency, maintenance burden, and compliance readiness alongside upfront price.
- Technology adoption is moving from optional to expected. Real-time monitoring, hybrid or electrified platform exploration, and lightweight designs that simplify deployment are beginning to influence purchasing criteria, particularly among producers seeking leaner operations and reduced licensing friction.
- Regional strategy requires localized insight. Demand concentration, infrastructure priorities, and procurement standards vary widely by geography. A successful market approach depends on understanding which regions offer the most reliable demand pull and which segments are most sensitive to local specification and validation requirements.
The full study expands each of these themes into operational guidance. It connects market size and growth expectations to segment-level behaviors, maps the strategic implications of recent product and policy developments, and highlights where competitive pressure is likely to intensify. For investors, the analysis supports more precise evaluation of market entry timing, end-market exposure, and technology risk. For manufacturers and distributors, it informs product planning, regional prioritization, and the design of service offerings that align with evolving buyer expectations. For procurement and fleet leaders, it sharpens the criteria for specification, supplier selection, and lifecycle cost modeling.
Why the Full Report Is the Strategic Next Step
A market overview can signal direction, but it cannot replace the granularity required to act. The complete Concrete Mixers Market research translates macro trajectory into decision-grade intelligence by combining validated sizing and forecast data with segment behavior, competitive profiling, and dynamic market forces. It is designed to reduce uncertainty around which product strategies, geographic priorities, and customer segments deserve disproportionate attention in the 2026 planning cycle.
Readers who require only high-level context may find this summary useful as a directional reference. Leaders responsible for capital deployment, product roadmaps, bidding strategy, or portfolio optimization will benefit from the deeper segmentation, competitive intelligence, and operational context available in the full publication. The report also provides a structured basis for scenario planning, helping teams prepare for multiple futures rather than betting on a single narrative.
To access the complete analysis, including detailed market sizing, forecast pathways, segment assessments, and the full competitive and dynamic landscape, visit the source page for the Concrete Mixers Market research. The complete report equips decision-makers with the depth required to convert market signals into strategic advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Concrete Mixers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


