



PW Consulting: Blood Tubing Set Market Hits $1,027.5M in 2025 with 4.12% CAGR to 2032

Strategic Intelligence in the Blood Tubing Set Market: Navigating Growth and Regulation in 2026
The global medical device landscape is undergoing a period of nuanced transformation, and few segments illustrate this complexity better than the Blood Tubing Set Market. As healthcare systems worldwide grapple with aging demographics, rising prevalence of chronic kidney disease, and increasingly stringent regulatory frameworks, the demand for reliable, high-performance extracorporeal blood circuits has never been more critical. For executives, procurement leaders, and investment analysts, understanding the trajectory of this market is not merely an academic exercise—it is a foundational requirement for strategic planning in 2026 and beyond.
At PW Consulting, we have released a comprehensive new study designed to cut through the noise and provide actionable intelligence. This article serves as an introduction to those findings, highlighting the strategic value the research offers to enterprises operating within or adjacent to the dialysis and blood transfusion ecosystems. While we preview the macro trends and competitive dynamics here, the full depth of segment-level analysis, regional breakdowns, and proprietary forecasts is reserved for our detailed report. Readers seeking to benchmark their position or identify high-yield opportunities are encouraged to consult the complete intelligence package.
Blood Collection Tubes Market
Market Trajectory and Core Financial Indicators
The Blood Tubing Set Market has demonstrated steady, predictable growth over the past half-decade, reflecting the essential nature of the products involved. Analysis of historical data from 2020 through 2025 reveals a consistent upward trajectory in revenue, moving from a baseline of approximately 812.35 million USD in 2020 to 1,027.5 million USD by 2025. This historical performance sets a robust foundation for the forecast period extending from 2026 to 2032.
Blood Tubing Set Market
Our forecast models indicate that the market will continue to expand, driven by volume growth in dialysis procedures and incremental improvements in tubing set durability and biocompatibility. The projected compounding annual growth rate (CAGR) for the forecast period stands at 4.12 percent. This rate suggests a mature but resilient market environment, where growth is less about explosive disruption and more about steady volume expansion, technological refinement, and strategic consolidation. By the end of the forecast horizon in 2032, total market revenue is anticipated to reach significant new thresholds, offering clear pathways for stakeholders who can navigate supply chain complexities and regulatory compliance effectively.
For decision-makers in 2026, this trajectory implies several strategic imperatives. First, the market is not poised for volatile spikes but rather for sustained, manageable growth, requiring long-term capacity planning rather than short-term speculation. Second, the financial metrics underscore the importance of cost efficiency in manufacturing and procurement, particularly given the material cost dynamics inherent in medical-grade production.
Product Segmentation and Clinical Applications
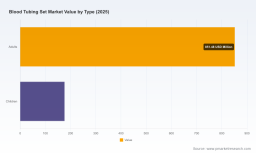
Understanding where value is generated within the Blood Tubing Set Market is critical for targeted strategy. The market is broadly segmented by patient demographics, distinguishing between adult and pediatric applications. Given the higher prevalence of end-stage renal disease in adult populations, the adult segment naturally commands the majority of revenue share. However, the pediatric segment, while smaller in volume, often commands different specifications regarding priming volume, biocompatibility, and safety features. A successful product portfolio must address both segments with appropriate engineering and positioning.
Application-wise, the market is anchored by two primary channels: dialysis centers and hospitals & clinics. Dialysis centers represent the dominant setting for blood tubing set utilization, reflecting the chronic nature of hemodialysis treatments and the high frequency of disposable circuit replacement required per patient per week. Hospital and clinic environments also constitute a vital channel, particularly for acute dialysis scenarios, surgical procedures requiring extracorporeal circulation, and specialized care units. Each channel presents distinct procurement cycles, reimbursement pathways, and regulatory oversight requirements.
Our report provides granular analysis of these segmentation splits, helping organizations identify which sub-segments offer the best alignment with their manufacturing capabilities or distribution strengths. Rather than applying a one-size-fits-all strategy, the data suggests that tailored approaches based on application setting and patient age group yield significantly better margins and customer retention.
Competitive Landscape: Key Players and Strategic Moves
The Blood Tubing Set Market is characterized by a concentrated competitive environment where established medical device manufacturers leverage specialized product portfolios and regulatory expertise to maintain market share. Several key companies define the landscape, offering machine-specific and system-agnostic solutions that cater to the diverse needs of hemodialysis providers.
Nipro Corporation, headquartered in Osaka, Japan, has established a strong presence through its NiproSet blood tubing sets. These products are notable for being machine-specific for hemodialysis, featuring FDA-tested components that emphasize compatibility and safety. Nipro’s strategy highlights the value of close integration with dialysis equipment manufacturers, ensuring that tubing sets perform optimally within specific system configurations.
B. Braun Melsungen AG, based in Melsungen, Germany, offers the Streamline Airless System Hemodialysis Bloodlines and DiaStream bloodline systems. These solutions focus on reducing air embolism risks and improving hemodynamic stability during treatment. B. Braun’s approach underscores the importance of engineering innovations that directly reduce clinical risks, a key selling point in procurement decisions made by hospital administrators and nephrology directors.
Fresenius Medical Care AG, with headquarters in Bad Homburg vor der Höhe, Germany, provides the CombiSet SMARTECH and other blood tubing sets tailored for hemodialysis machines. As a global leader in dialysis care, Fresenius leverages its extensive clinical network and integrated service model to promote its consumables, reinforcing brand loyalty and standard-setting within care facilities.
Recent developments in the competitive and regulatory space underscore the need for vigilance. In April 2026, B. Braun Medical Inc. issued an urgent medical device correction regarding the Streamline Airless System Hemodialysis Bloodlines and B3 Low Volume Bloodlines. The correction addressed potential microbubble and leakage risks, with updates issued following FDA MedWatch alerts. Such events serve as a stark reminder that even mature products require continuous quality monitoring, rapid response protocols, and transparent communication with the regulatory community. For competitors and customers alike, these corrections influence purchasing confidence and may shift volume toward alternative suppliers who can demonstrate robust quality management systems.
Regulatory Environment and Clinical Compliance
The Blood Tubing Set Market operates within a tightly regulated framework that shapes product development, market entry, and ongoing compliance. Hemodialysis blood tubing sets are classified as Class II devices, subject to FDA 510(k) requirements for demonstrating substantial equivalence to existing predicates. This regulatory pathway demands rigorous documentation, clinical performance data, and quality system adherence, creating barriers to entry that protect established players while ensuring patient safety.
Reimbursement dynamics also play a pivotal role in market behavior. Hemodialysis blood tubing sets are covered under Medicare Part B reimbursement codes for dialysis procedures, linking device utilization directly to federal payment structures. Changes in coverage policies or coding updates can ripple through demand patterns, affecting volume projections and pricing strategies. Stakeholders must stay attuned to Centers for Medicare & Medicaid Services (CMS) national coverage determinations, which remain active and influential throughout 2026.
International standards further complicate the compliance landscape. Blood tubing sets must comply with ISO 10993 biocompatibility standards for blood contact, ensuring that materials do not induce adverse immune or thrombotic responses. Additionally, all blood tubing sets are single-use devices sterilized via gamma irradiation or ethylene oxide prior to market release, as mandated by FDA premarket notification guidance. These sterilization requirements impact production logistics, facility design, and cost structures, particularly regarding the medical-grade PVC tubing that forms the core of many sets. Unit costs for such tubing can vary between 5 and 15 USD per set depending on volume and customization, adding a layer of financial sensitivity that procurement teams must manage carefully.
Strategic Insights for 2026 Decision-Making
The intersection of market growth, competitive dynamics, and regulatory requirements creates a complex environment where strategic foresight is paramount. For manufacturers, the key challenge lies in balancing innovation with compliance, ensuring that new product features do not inadvertently trigger additional regulatory scrutiny or quality issues. For distributors and healthcare providers, the focus shifts to supply chain resilience, vendor reliability, and cost optimization without compromising patient safety.
Several actionable themes emerge for 2026:
- Portfolio Optimization: Companies should assess whether their tubing set offerings adequately address the divergent needs of adult versus pediatric patients and the specific requirements of dialysis centers versus hospital settings. Consolidating around high-performing, compliant products while phasing out underperforming SKUs can sharpen competitive positioning.
- Regulatory Preparedness: With Class II classification and ISO 10993 compliance as baseline requirements, organizations must maintain robust documentation and quality management systems. Proactive engagement with regulators and continuous monitoring of safety alerts, such as the 2026 B. Braun correction, can mitigate reputational risk and inform product improvement cycles.
- Cost and Supply Chain Management: Given the material cost variability in medical-grade PVC and the sterilization requirements, procurement strategies should factor in volume commitments, supplier diversification, and logistics stability. Long-term contracts with reliable raw material suppliers can help smooth out unit cost fluctuations.
- Reimbursement Alignment: Understanding how Medicare Part B codes and CMS determinations affect demand is essential for revenue forecasting. Aligning product features with reimbursable procedure codes can enhance market access and encourage adoption in cost-sensitive care settings.
What the Full PW Consulting Study Delivers
The insights outlined above represent only the opening chapter of our comprehensive Blood Tubing Set Market research. The full report goes much deeper, offering a level of granularity that enables precise strategic planning and investment analysis. Readers who access the complete study will find detailed segmentation breakdowns by region and type, forward-looking revenue forecasts through 2032, and a thorough examination of market concentration metrics. The report also includes analysis of industry context, covering regulatory shifts, reimbursement updates, material cost trends, and sterilization practices that impact total cost of ownership.
Furthermore, the study provides an in-depth competitive benchmarking section, profiling key players, their product specifications, recent developments, and strategic positioning. This allows companies to benchmark their own offerings, identify gaps in their portfolios, and anticipate competitor moves with greater accuracy. The research is designed to serve a wide range of stakeholders, from product managers and supply chain directors to investors and policy analysts, delivering a cohesive narrative backed by rigorous data analysis.
Conclusion
The Blood Tubing Set Market in 2026 is a landscape of steady growth, concentrated competition, and rigorous compliance demands. For organizations operating in this space, the ability to interpret market signals, anticipate regulatory changes, and align product strategies with clinical and reimbursement realities will determine long-term success. PW Consulting’s latest market research provides the strategic intelligence needed to navigate this environment with confidence, transforming raw data into clear, actionable directions. To unlock the full spectrum of insights, segmentation details, and competitive analysis, we invite you to explore the complete report and integrate its findings into your 2026 strategic planning.
For detailed analysis of this topic, please visit the official page: Blood Tubing Set Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


