



PW Consulting: Titanium Diboride Market Hits $44.1M in 2025, Set to Grow at 4.5% CAGR Through 2032

Navigating the Titanium Diboride Market: Strategic Intelligence for 2026 Decision-Makers
The global landscape for advanced ceramics is undergoing a quiet but fundamental transformation. At the center of this shift lies titanium diboride (TiB2), a material whose unique combination of hardness, electrical conductivity, and thermal stability is reshaping demand patterns across defense, semiconductor, and industrial manufacturing sectors. As organizations finalize their capital allocation and product roadmaps for 2026 and beyond, access to granular, forward-looking intelligence is no longer a luxury—it is a prerequisite for sustainable competitive advantage.
Our latest Titanium Diboride Market study, published by PW Consulting, is designed to meet this imperative. Spanning a historical analysis from 2020 through 2025 and a comprehensive forecast extending to 2032, this research translates complex market signals into an actionable strategic framework. Below, we outline the core architecture of the analysis, highlight the competitive dynamics currently reshaping the value chain, and explain why deepening your understanding of this niche—but rapidly evolving—market is a critical exercise for executive teams planning their next phase of growth.
Market Trajectory: From Steady Expansion to Strategic Inflection
The titanium diboride market has demonstrated resilient, compounding growth over the past half-decade. In 2020, total global market revenue stood at approximately 32.0 million USD. By 2025, that figure had climbed to 44.1 million USD—a trajectory that reflects both organic industrial adoption and the material's successful penetration into high-performance end-use segments. Looking ahead, our baseline forecast projects continued expansion, with market revenue expected to reach 45.28 million USD in 2026 and advance steadily toward 60.2 million USD by 2032. This long-view projection is anchored by an anticipated compound annual growth rate (CAGR) of 4.5 percent across the 2026-to-2032 forecast horizon.
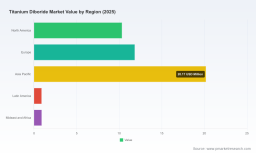
These macroeconomic figures tell an important story, but they are only the starting point. The real strategic value lies in understanding how this growth is distributed across product types, application verticals, and geographic corridors—exactly the dimensions where competitive positioning can be won or lost. Market analysis at this level must move beyond headline numbers to examine the structural drivers: the maturation of bulk-grade production against the accelerating uptake of nanostructured formulations, the shifting allocation of demand across cutting tools, wear-resistant coatings, armor materials, refractory applications, electrodes and electrical contacts, composite materials, thermal barrier coatings, nuclear applications, and aerospace components, as well as the divergent growth tempos across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Each of these segments carries its own pricing logic, supply constraints, and technology adoption curves, and our study maps them with precision.
Importantly, the market's growth profile is not uniformly distributed, and concentration patterns underscore this reality. The top three participants command a combined market share of 62.0 percent, while the top five extend that figure to 76.0 percent. This level of consolidation signals a market where scale, technology moats, and long-term customer relationships carry disproportionate weight—and where new entrants or expanding players must navigate an already crowded field with clear differentiation strategies.
Inside the Report: An Operational Playbook, Not a Static Snapshot
PW Consulting's Titanium Diboride Market study is structured to serve as a working reference for strategy, procurement, product development, and investment teams. Rather than offering a single trajectory, the report builds a multi-dimensional view of the market that connects demand fundamentals with supply-side realities, competitive behavior, and the broader industrial environment.
Key components of the analysis include:
- Segment-level deep dives: Detailed evaluation of how each product type and application category is evolving in terms of volume, value, technology requirements, and end-user adoption incentives. The analysis highlights where premium-grade materials are unlocking higher margins and where cost-optimized bulk supplies remain the dominant commercial vehicle.
- Regional market architecture: A geographically disaggregated assessment that examines demand intensity, manufacturing presence, trade flows, and localized supply constraints across all major regions. This section is designed to inform capacity siting decisions, partnership targeting, and market-entry prioritization.
- Competitive profiling and strategic positioning: In-depth company assessments that go beyond corporate descriptions to evaluate each player's product focus, geographic footprint, technology emphasis, and apparent strategic direction. The report contextualizes how established specialists and emerging capacity additions are reshaping share dynamics.
- Supply chain and input cost context: Examination of the material ecosystem that underpins titanium diboride production, including the role of boron-based feedstocks, energy intensity, and the operational impact of logistics and freight conditions on cost structures.
- Regulatory and environmental overlay: Analysis of how environmental considerations, mining and processing constraints, and compliance dynamics influence both upstream feedstock availability and downstream manufacturing economics.
- Technology and application horizon scanning: Identification of emerging use cases—such as additive manufacturing grades, advanced electronic sputtering targets, and next-generation armor and aerospace ceramics—that are expanding the addressable market and creating new value pools.
- Forecast scenarios and decision frameworks: Structured projections through 2032 that allow readers to stress-test assumptions around demand growth, competitive intensity, and input cost evolution, supporting both short-term operational planning and longer-range investment evaluation.
This integrated approach ensures that the study functions as more than a data repository. It is built to help decision-makers translate market signals into concrete actions: whether that means prioritizing a specific application vertical for product development, evaluating a potential partnership or acquisition, calibrating pricing strategy in a consolidating market, or assessing the viability of new capacity in a specific geographic corridor.
Competitive Dynamics: Specialists, Subscale Disruption, and Strategic Consolidation
The titanium diboride market is defined by a set of specialized producers whose capabilities are tightly aligned with specific end-use requirements. Understanding who these players are—and how they are positioning themselves—offers essential context for any strategic assessment of the market.
Europe remains home to several high-purity, technology-focused producers. Treibacher Industrie AG, based in Althofen, Austria, stands as a leading European source of high-purity titanium diboride powders and related hard material powders, serving industrial, aerospace, and electronics applications. Alongside it, H.C. Starck GmbH, part of the Mitsubishi Materials Group and headquartered in Goslar, Germany, is a prominent European producer of high-purity TiB2 powders and sputtering targets, with a strong presence in semiconductor, aerospace, and specialty chemistry markets. In a recent strategic move, H.C. Starck launched a new grade of titanium diboride powder tailored for additive manufacturing applications, with improved properties aimed at aerospace and automotive end-use sectors—a development that underscores the growing intersection between advanced materials and next-generation manufacturing processes.
In North America, the competitive picture blends established industrial material strength with specialized high-performance applications. 3M Company, through its Ceradyne subsidiary based in St. Paul, Minnesota, operates as a dominant supplier of TiB2-based defense armor, aerospace ceramics, and advanced materials, supported by long-standing military procurement relationships. Materion Corporation, headquartered in Mayfield Heights, Ohio, concentrates on high-purity TiB2 sputtering targets and specialty powders for semiconductor and thin-film deposition markets across North America and Europe—an application space where purity specifications and consistent quality are critical differentiators.
Japan continues to play a central role in specialty-grade material supply. Japan New Metals Co., Ltd., based in Toyonaka, Osaka, supplies specialty-grade TiB2 powders designed for electronics, precision tooling, semiconductor, and other high-value-added applications, with both domestic demand and export markets in scope.
China's manufacturing base adds significant volume and breadth to the global supply picture. Shandong Pengcheng Advanced Ceramics Co., Ltd., located in Zibo, Shandong, operates as a major Chinese producer of TiB2 ceramics, powders, and conductive ceramics, with applications spanning aluminum smelting cathodes, industrial cutting tools, and armor protection. Dandong Chemical Engineering Institute Co., Ltd. (DCEI), based in Dandong, Liaoning, produces titanium diboride alongside hexagonal boron nitride and amorphous boron powders, leveraging advanced processing technologies for a range of industrial applications. Together, these producers illustrate the dual nature of the market: a high-value, purity-sensitive segment driven by electronics, aerospace, and defense requirements, and a volume-oriented segment anchored in industrial tooling, wear applications, and cathode materials.
Worldwide Military Grade Titanium Disilicide Powder Market
Capacity and geographic expansion are already reshaping the competitive landscape. In July 2025, Kyocera Corporation acquired a titanium diboride ceramics manufacturing facility in South Korea, a move aimed at expanding production capacity and strengthening its market presence in the region. Such initiatives signal that established materials manufacturers are actively investing in geographic diversification and production scale, reinforcing the market's growth trajectory while simultaneously raising the bar for competitive differentiation.
Input Costs, Logistics, and Regulatory Currents: The Forces Shaping Margins
No strategic assessment of the titanium diboride market is complete without examining the upstream and environmental forces that influence both cost structures and supply reliability. Boron-based feedstocks sit at the heart of TiB2 production economics, and recent market intelligence points to several interconnected dynamics that buyers and producers alike must monitor.
Global boric acid prices exhibited a slightly declining trend in the first quarter of 2026, with spot prices in China recorded at 1,146 USD per metric ton in December 2025 amid relatively stable supply conditions. While a softening in feedstock pricing can ease input cost pressure in the near term, it does not eliminate the structural sensitivities that define this supply chain. Environmental regulations and mining costs continue to shape boric acid supply-side conditions for boron-based materials, introducing a persistent layer of uncertainty into cost forecasting. At the same time, supply chain disruptions and logistical challenges have influenced boric acid price movements across North America, Asia Pacific, and Europe, while environmental restrictions and freight rate fluctuations remain key factors affecting the overall cost structure of boron feedstock destined for TiB2 production.
For market participants, these dynamics carry direct strategic implications. Procurement teams must evaluate supplier resilience, inventory buffers, and geographic sourcing diversification in light of freight volatility and regulatory constraints. Producers need to factor energy intensity, environmental compliance, and logistics exposure into capital planning and pricing architecture. And executives designing market-entry or capacity-expansion strategies must account not only for demand momentum but also for the evolving complexity of the input cost environment that will ultimately determine margin sustainability.
Why This Research Matters for 2026 Strategy
As organizations move from planning cycles into execution, the titanium diboride market presents a clear case for informed, data-grounded decision-making. The combination of a consolidated competitive structure, differentiated application demand, evolving manufacturing technologies, and a feedstock environment shaped by logistics and regulatory pressures creates a setting where strategic clarity matters more than ever.
This study is designed to give executives, analysts, and operational leaders the kind of market visibility that supports confident action. It connects high-level growth trajectories with the granular segment and competitive intelligence required to build realistic scenarios, identify priority opportunities, and anticipate the shifts that will redefine value creation through 2032. Whether your focus is on expanding product portfolios, securing supply, evaluating partnership or acquisition targets, or positioning for geographic growth, the report offers the structured insight needed to move forward with precision.
For a complete view of the market size, segment dynamics, competitive profiles, and forward-looking forecasts underpinning this analysis, we invite you to access the full Titanium Diboride Market research. The detailed intelligence within is built to support the decisions that will define your organization's trajectory in the years ahead.
Titanium Diboride Market
For detailed analysis of this topic, please visit the official page: Titanium Diboride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


