



PW Consulting: White Fused Alumina Market Hits $200M in 2025, Projects 4.01% CAGR Through 2032

White Fused Alumina Market 2026: Strategic Intelligence for Industrial Decision-Makers
As industrial manufacturing enters a new cycle of material optimization and cost discipline, White Fused Alumina has emerged as a critical component across abrasives, refractories, and technical ceramics. The global market has demonstrated consistent expansion over the past five years, growing from 150.0 Million USD in 2020 to 200.0 Million USD in 2025, with revenue projections indicating a continued upward trajectory through the end of the decade. Our latest White Fused Alumina Market research is built to translate this trajectory into executable strategy, giving procurement leaders, product developers, and market planners a precise, evidence-based view of where value is being created and where competitive pressure is intensifying.
This analysis is not a static snapshot. It is a forward-looking strategic instrument calibrated for the 2026 decision window. By combining historical performance from 2020 through 2025 with a structured forecast spanning 2026 to 2032, the report enables stakeholders to test assumptions, align supply commitments, and prepare for shifting demand patterns without relying on fragmented secondary sources or outdated industry narratives.
Market Trajectory and the Strategic Meaning of the Growth Curve
The market's evolution reflects more than incremental volume growth. The progression from 159.67 Million USD in 2021 to 170.69 Million USD in 2022, followed by acceleration toward 185.97 Million USD in 2023 and a measured 187.12 Million USD in 2024, shows a sector that has absorbed supply disruptions, raw material volatility, and regional demand rebalancing while still advancing ahead of broader industrial benchmarks. The 200.0 Million USD baseline in 2025 reinforces a market that has stabilized around quality differentiation, application-specific grading, and more disciplined inventory management.
From a strategic planning perspective, the forecast period tells its own story. Revenue is expected to reach 215.16 Million USD in 2026, followed by 217.06 Million USD in 2027 and 229.1 Million USD in 2028. The projection continues into 2029 at 231.99 Million USD, approaches 248.89 Million USD by 2030, and then moves toward 245.29 Million USD in 2031 before reaching 263.29 Million USD in 2032. These are not arbitrary numbers. They are planning inputs that help organizations gauge capacity timing, contracting windows, and the pace at which high-performance grades may capture additional share as downstream users demand better wear resistance, thermal stability, and polished surface outcomes.
The overall growth profile supports a compound annual growth rate of 4.01 percent across the forecast horizon, indicating a market that rewards companies able to align product specifications with end-use performance requirements rather than competing solely on commoditized volume. For 2026 planning, this means the strategic question is less about whether demand will advance and more about how to position specifications, supply agreements, and regional sourcing decisions to capture margin in a market where performance credibility increasingly determines customer retention.
Report Architecture: What Decision-Makers Will Find Inside
The study is organized to convert market complexity into operational clarity. Rather than offering a high-level overview alone, the report maps the market across type, application, and regional demand structures so that readers can align internal assumptions with external evidence. The segmentation logic is designed for practical use: it helps teams understand where white fused alumina is being specified, which grade structures are gaining emphasis, and how application requirements are reshaping procurement priorities.
Fused Magnesia Market
Inside the report, stakeholders will find:
- A full market size reconstruction from 2020 through 2025, providing a verifiable historical baseline for internal forecasting and board-level review.
- A detailed 2026 to 2032 outlook that translates growth momentum into planning-relevant signals for capacity, sourcing, and product roadmap decisions.
- Type-level analysis that distinguishes among refractory, abrasive, and ceramic-grade demand patterns, supporting product positioning and specification strategy.
- Application-level evaluation that examines how refractories, abrasives, and ceramics usage shapes volume flows and customer requirements.
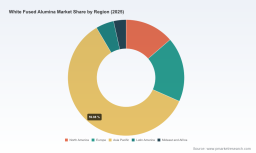
- Regional demand mapping that reveals where consumption is concentrated and how geographic dynamics influence pricing, logistics, and sourcing strategy.
- Competitive profile coverage of the leading producers, including operational focus, product offerings, and strategic positioning within the white fused alumina value chain.
- Synthesis of industry dynamics that connects supply-side realities with downstream performance expectations, giving readers context for scenario planning and risk assessment.
The report is intended for teams that need more than directional commentary. It provides a structured foundation for budgeting, segment prioritization, customer strategy, and competitive positioning in a market where small specification advantages can translate into long-term contract value.
Competitive Landscape: Who Shapes the Market and How
The white fused alumina market is defined by a mix of established industrial suppliers and regionally influential producers, each bringing a different balance of purity, scale, application focus, and geographic reach. Our analysis examines the companies that materially influence pricing behavior, grade availability, and supply reliability, allowing readers to benchmark their own positioning against the actors most likely to affect purchasing decisions in 2026 and beyond.
Washington Mills operates with a clear emphasis on high-purity output, manufacturing white fused alumina grains, powders, and bubbles via electric arc fusion of Bayer-processed alumina. With material purity exceeding 99 percent Al2O3, the company supports demanding uses in refractories, ceramics, abrasives, and polishing applications. For customers where consistency and purity are non-negotiable, this profile signals a supplier orientation toward performance-sensitive segments rather than volume-only competition.
Imerys brings a broad, globally distributed production footprint to the market. With 12 global production sites, the company produces fused alumina, including white fused alumina, under the Alodur brand for abrasives, refractories, and technical ceramics. That scale and brand architecture matter in procurement environments where supply continuity, multi-region coverage, and application versatility are weighed alongside price.
Rusal contributes to the landscape through large-scale electric arc furnace production of white fused alumina from pure alumina at its Boksitogorsk Alumina Refinery. The company's integration with upstream alumina resources gives it a distinct supply-chain posture, which can influence cost structure, volume reliability, and the ability to serve industrial users seeking stable baseline supply.
U.S. Electrofused Minerals positions white fused alumina within a broader fused oxides portfolio for industrial applications. Its approach reflects a practical, application-oriented supply model in which white fused alumina is part of a wider materials offering, allowing customers to consolidate sourcing across related oxide products where specification alignment is possible.
MOTIM Electrocorundum provides another important European reference point, producing high-quality white fused alumina for refractories and abrasives. Its specialization reinforces the market's split between performance-driven and cost-sensitive purchasing channels, as well as the continued relevance of regional manufacturers that combine technical consistency with proximity to key industrial users.
In the Asia-Pacific supply structure, Zhengzhou Yufa Group stands out as a large-scale producer with a strong emphasis on cost-efficient supply for global abrasives and refractories. Henan Ruishi Renewable Resources Group similarly supplies white fused alumina grains and powders for industrial use, adding to the region's manufacturing depth and reinforcing the competitive importance of volume capability, logistics efficiency, and pricing agility.
Together, these players illustrate a market where concentration creates both opportunity and caution. The sector's structure indicates that a limited number of producers account for a substantial share of revenue, while still leaving room for specialized suppliers to compete on grade, purity, and service. For 2026 strategy, that means competitive intelligence cannot stop at product specs; it must also address supplier reliability, regional coverage, and the ability to respond to application-specific demand shifts.
Industry Context and Strategic Implications for 2026
The market intelligence in this study is grounded in current industrial realities. White fused alumina demand does not evolve in isolation. It is shaped by how abrasives manufacturers balance surface-finishing performance against cost, how refractory producers evaluate thermal endurance and service life, and how ceramics users align material characteristics with component requirements. At the same time, supply-side considerations such as energy intensity, raw alumina availability, furnace operation efficiency, and logistics constraints influence how reliably producers can meet specification-sensitive orders.
For 2026 planning, these dynamics create several strategic priorities. Companies need to evaluate whether their product and sourcing strategies are aligned with the growing importance of high-consistency grades. Procurement teams must weigh whether multi-supplier structures or consolidated partnerships better serve their risk and performance requirements. Market leaders need to determine where differentiation is sustainable, particularly in applications where wear life, polish quality, and thermal behavior directly affect downstream economics.
The report also supports scenario-based thinking. Because the forecast extends through 2032, organizations can use it to test how changes in regional demand strength, application mix, or grade adoption might alter revenue potential and competitive intensity. That forward visibility is especially valuable for capital planning, long-term contracts, and product development roadmaps where premature commitments can erode flexibility and delayed moves can cede share to more responsive competitors.
White Fused Alumina Market
Why This Research Matters Now
The white fused alumina market is entering a phase where informed decisions will separate resilient operators from those forced to react to supply and pricing shifts after the fact. With a 2025 baseline of 200.0 Million USD and a forecast that points toward 263.29 Million USD by 2032, the market offers meaningful expansion, but it also demands sharper segmentation insight, supplier benchmarking, and application-level understanding. Organizations that enter 2026 with only generic market narratives will be at a disadvantage when negotiating with producers, specifying grades for sensitive applications, or deciding where to invest in capability and coverage.
This White Fused Alumina Market research is designed to close that gap. It translates verified historical data, forward projections, and competitive profiling into a usable strategic framework for 2026 decision-making. The full intelligence set, including deeper segmentation detail, regional demand analysis, and complete company profiles, is available through the complete report. For teams that need precise market estimates, actionable segmentation, and a clear view of who is shaping the competitive environment, the full study provides the depth required to move from awareness to execution.
For detailed analysis of this topic, please visit the official page: White Fused Alumina Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


