



PW Consulting: Glass Recycling Market to Hit $5.88B by 2032 with 5.66% CAGR

Strategic Intelligence for the Circular Economy: Unlocking Value in the Global Glass Recycling Market 2026–2032
The global transition toward circular economic models is no longer a theoretical ambition; it is a operational imperative reshaping supply chains, regulatory compliance, and capital allocation across the materials sector. For executives navigating the glass manufacturing and waste management landscapes, the coming years present a complex matrix of opportunity and risk. PW Consulting's latest comprehensive study on the Glass Recycling Market is designed to convert this complexity into actionable strategic clarity. As organizations prepare their capital plans and operational roadmaps for the 2026 fiscal year and beyond, understanding the granular mechanics of this market is essential to securing competitive advantage.
Plastic Recycling Market
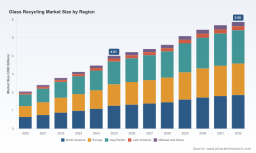
This market research report serves as a critical decision-support tool, offering a data-rich examination of an industry poised for steady expansion. The underlying narrative is one of maturation. Drawing on historical data from 2020 through 2025, the analysis establishes a baseline of robust growth that continues into the forecast period extending to 2032. In 2020, the global market valuation stood at approximately 2.05 billion USD. By the base year of 2025, this figure had climbed to 4.01 billion USD, reflecting a compound annual growth rate of 5.66 percent over the analyzed historical window. Looking forward, the trajectory suggests continued momentum, with projected revenues reaching 4.2 billion USD in 2026 and advancing toward 5.88 billion USD by 2032. These figures are not merely statistics; they represent the scale of investment required, the volume of feedstock in motion, and the financial magnitude of the opportunity awaiting stakeholders who can navigate the technical and regulatory nuances of glass recovery.
Navigating the Core Dynamics and Operational Challenges
While the headline numbers indicate growth, the strategic value of this research lies in its dissection of the underlying dynamics. The glass recycling ecosystem is not a monolith; it is a fragmented network of collection infrastructure, processing technology, and end-market demand, all influenced by a tightening regulatory environment. A primary focus of the report is the infrastructure bottleneck that currently limits the efficiency of material recovery. Industry data indicates that only 40 percent of glass recycling is accepted at material recovery facilities, largely due to commingling in single-stream systems. This infrastructure constraint creates significant variance in feedstock quality and availability, directly impacting the economics of downstream manufacturers.
Simultaneously, the regulatory landscape is accelerating the demand for recycled content. In Europe, the Packaging and Packaging Waste Regulation 2025/40 entered into force on 11 February 2025 and is generally applicable from 12 August 2026, mandating glass packaging recycling targets at 70 percent by 2025. Such mandates force a reevaluation of procurement strategies for packaging firms, making reliable access to high-quality cullet a critical compliance and operational requirement. In the United States, the glass container recycling rate was recorded at 31.3 percent in 2018, with 3.1 million tons recycled from 12.3 million tons generated. While legislative efforts in states like California have supported increased recycled glass use in packaging, the gap between generation and recovery remains a key area of strategic focus. Furthermore, the economic case for recycling is reinforced by operational efficiencies; for every 10 percent increase in cullet in the batch, furnace energy needs drop by nearly 3 percent. This energy dynamic is a crucial lever for margin improvement in an era of volatile energy prices, and the report deep-dives into how this variable influences regional competitiveness.
Glass Recycling Market
Segmentation and Application Realities
To deploy capital effectively, leaders must understand where value is generated within the value chain. The report provides a rigorous breakdown of the market by product and application, revealing the dominance of specific segments while highlighting the emerging potential of niche applications. Recycled glass cullet remains the cornerstone of the industry, commanding a significant share of the market revenue due to its direct application in container and fiberglass manufacturing. The processing of glass into powder and crushed glass forms represents additional vectors of value creation, catering to specialized industrial needs ranging from abrasives to fillers.
On the demand side, glass containers continue to be the primary driver of recycled material consumption, reflecting the packaging sector's reliance on sustainable inputs. However, the analysis also scrutinizes other critical applications, including flat glass for construction and automotive sectors, and fiber glass for insulation and reinforcement. Smaller but strategically distinct segments such as highway beads, abrasives, and fillers offer diversification opportunities for processors looking to optimize yield and reduce waste. The report avoids superficial aggregation, instead offering a detailed view of how volume flows through these different channels, helping clients identify which applications offer the highest margins, the most stable demand, and the best alignment with their existing operational capabilities. It is important to note that while the report quantifies these market shares with precision, the full depth of regional and application-specific revenue data is reserved for the complete deliverable to ensure stakeholders derive maximum value from the proprietary analysis.
Competitive Landscape and Strategic Consolidation
The competitive architecture of the glass recycling market is characterized by a mix of established multinational players, specialized regional processors, and vertically integrated manufacturers. The market concentration metrics indicate that the top three companies hold a combined share of 42 percent, while the top five account for 51 percent of the market. This level of concentration suggests a mature industry where scale and network density are significant barriers to entry, yet sufficient fragmentation remains for strategic M&A and partnership activity to reshape the landscape.
Key players are actively positioning themselves to capture this growth through expansion, partnerships, and acquisitions. Sibelco, headquartered in Houston, Texas, stands as a dominant force, producing and supplying high-quality recycled glass cullet with a global capacity exceeding 5 million tons annually, including 2 million tons in North America, supported by over 60 facilities. In a significant move to expand its footprint, Sibelco acquired Strategic Materials, Inc. in December 2025, a transaction designed to expand the glass recycling network across North America. Strategic Materials itself is a critical node in the ecosystem, processing and supplying recycled glass cullet as high-quality feedstock for container and fiberglass production.
Other major entities are pursuing parallel strategies to secure their supply chains and enhance sustainability credentials. Owens-Illinois, Inc., based in Toledo, Ohio, operates the Glass4Good program, which recycled 392 metric tons in 2025, representing a 24 percent increase, with cullet processed into new glass bottles and jars. Vetropack Holding AG, headquartered in Meyrin, Switzerland, processes and supplies recycled glass cullet for container manufacturing and other glass applications, reinforcing the European supply base. Ardagh Group, based in Dublin, Ireland, has focused on partnerships for glass recycling services and cullet supply in container production. In April 2025, Ardagh Glass Packaging partnered with CAP Glass to establish advanced glass recycling services across the U.S. for high-quality cullet supply, signaling a strong push into the North American market. Momentum Recycling, LLC, operating out of Utah, processes glass recycling with a focus on cullet production for manufacturing and aggregates, illustrating the role of specialized regional players in optimizing local loops.
Recent developments further underscore the dynamic nature of this competitive field. In March 2025, Glass Half Full opened a new 10,000-square-foot recycling facility in Chalmette, Louisiana, with a capacity of 300,000 pounds per day, marking a 30-fold increase in processing capability. Such expansions demonstrate the rapid scaling potential in regions where infrastructure has been lacking, and the report analyzes the implications of these capacity additions for regional pricing and supply stability.
The 2026 Decision Framework
As organizations finalize their strategies for 2026, the insights contained in this report provide a framework for addressing the most pressing questions facing industry leaders. How should procurement teams structure contracts to mitigate the risk of cullet shortages driven by regulatory targets and infrastructure limitations? Where do the highest growth opportunities lie for processors looking to invest in new fractionation or processing technologies? How does the energy efficiency gain from cullet substitution translate into competitive pricing power in the container and flat glass markets? And perhaps most critically, how should companies evaluate the strategic fit of potential acquisitions or partnerships in a market where consolidation is accelerating, as evidenced by recent moves from major players?
The report equips decision-makers with the analytical tools to answer these questions. It moves beyond generic industry commentary to provide specific, data-backed assessments of market drivers, restraints, and opportunities. By integrating historical performance with forward-looking forecasts, it allows for scenario planning that accounts for regulatory shifts, energy price volatility, and changing consumer preferences. The analysis also highlights the interplay between regional dynamics and global market forces, ensuring that strategies are robust whether they are deployed in mature markets with high recycling rates or emerging regions where infrastructure is being built out.
Conclusion: A Catalyst for Sustainable Growth
The glass recycling market is at an inflection point. The convergence of regulatory pressure, energy economics, and corporate sustainability commitments is driving demand for recycled glass at a pace that outstrips the current capacity of many supply chains. For companies operating in this space, the margin for error is narrowing. Success in 2026 and beyond will belong to those who can secure reliable feedstock, optimize processing efficiency, and align their product portfolios with the most value-intensive applications.
PW Consulting's in-depth Glass Recycling Market research is more than a data repository; it is a strategic asset designed to inform high-stakes decisions. By revealing the structural forces shaping the market and profiling the competitive maneuvers of key players, the report empowers stakeholders to act with confidence. To access the full spectrum of analysis, including detailed segmentation data, regional breakdowns, and comprehensive competitor profiling, stakeholders are encouraged to explore the complete report. The intelligence contained within is essential for turning the challenges of the circular transition into a durable source of growth and resilience.
For detailed analysis of this topic, please visit the official page: Glass Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


