



PW Consulting: Petroleum Needle Coke Market Hits $215M in 2025 With 6.7% CAGR Through 2032

Navigating the Carbon Matrix: Strategic Imperatives in the Petroleum Needle Coke Market Through 2032
The global petroleum needle coke sector stands at a critical inflection point. As graphite electrode demand aligns with grid-scale steelmaking and lithium-ion battery supply chains accelerate, the underlying feedstock architecture is undergoing a structural realignment. For executives, procurement leaders, and capital allocators, the 2026–2032 horizon presents both margin compression risks and premium positioning opportunities. This guide synthesizes the core market architecture, competitive vectors, and operational dynamics that will shape strategic decision-making in the coming cycle. It is designed to function as a strategic compass—grounded in verified market trajectories, yet deliberately scoped to preserve the granular intelligence required for enterprise-grade execution.
Macro Trajectory: Navigating a 6.7% CAGR Across a Reshaped Demand Base
Over the 2020–2025 historical window, the petroleum needle coke market expanded from approximately 163.15 million USD to 215.0 million USD, reflecting a compound trajectory driven by electrode manufacturing intensification and the early-stage integration of battery-grade carbon materials. The forward arc, projected through 2032, extends this momentum with a steady CAGR of 6.7 percent, carrying the aggregate valuation toward the mid-340 million USD range by the close of the forecast period. This growth is not merely linear accumulation; it is structurally uneven, shaped by feedstock pricing volatility, regional capacity recalibration, and a widening divergence between traditional graphite electrode applications and emerging energy storage pathways.
The base year of 2025 serves as a calibration anchor, capturing post-restriction market normalization and the initial absorption of environmental compliance investments. From 2026 onward, the expansion curve reflects compounding capacity additions, qualification cycles for lower-carbon coke variants, and the gradual migration of high-performance anode materials into mainstream battery architectures. Decision-makers evaluating capex timing, supplier diversification, or vertical integration must anchor their models to this trajectory while recognizing that the underlying segmentation shifts will dictate where value actually accrues.
Importantly, the market’s concentration profile underscores a highly consolidated supply environment. A small cohort of integrated producers commands the majority of electrode-grade and battery-grade output, creating both pricing discipline and vulnerability to localized operational disruptions. Understanding how this concentration interacts with regional regulatory acceleration and feedstock availability is essential for anyone mapping supply chain resilience or negotiating long-term tolling and offtake arrangements.
Segmentation Architecture: Where Volume Meets Value
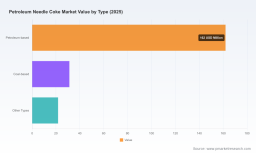
The market’s structural composition reveals three interlocking dimensions that collectively determine margin exposure and growth velocity. The type split highlights the dominance of petroleum-derived needle coke relative to coal-based and other variants, with petroleum routes capturing the bulk of premium-grade electrode and anode production. This hierarchy is not static; it is being actively reshaped by lifecycle emissions considerations, feedstock accessibility, and processing maturity.
Application-wise, graphite electrodes continue to anchor the largest share of consumption, reflecting their entrenched role in electric arc furnace steelmaking and specialty carbon applications. Simultaneously, lithium-ion battery usage represents a smaller but rapidly scaling segment, driven by anode material innovation and the push for higher energy density and faster charge cycles. The remaining application pool serves niche industrial and composite manufacturing requirements.
Regional dispersion further complicates the picture. Supply and demand nodes span North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, each exhibiting distinct consumption intensity, regulatory posture, and feedstock logistics. Capacity additions, export flows, and localized compliance requirements interact to create pockets of tightness and surplus that rarely align with headline aggregates. For strategic planning, this means that aggregate sizing alone is insufficient; the actionable intelligence lies in how segment dynamics intersect with regional supply constraints, qualification lead times, and downstream manufacturing capacity pipelines.
Competitive Landscape: Integrated Producers, Strategic Moves, and Positioning Vectors
The competitive field is defined by a mix of refinery-integrated operators, specialty coke producers, and regionally anchored suppliers whose processing capabilities and customer qualification networks determine market access. Several entities stand out for their operational footprint, product-grade versatility, and recent strategic interventions.
- Phillips 66 Company (Houston, Texas, United States) operates through integrated delayed-coking infrastructure, including its Lake Charles refinery complex, delivering both electrode-grade and battery-grade material. Its recent trajectory reflects a deliberate alignment with energy storage demand, underscored by a multi-hundred-million-dollar capacity expansion in Louisiana and a long-term supply agreement supporting a large-scale graphite-anode plant in North Carolina.
- GrafTech International Ltd. (Brooklyn Heights, Ohio, United States) maintains a vertically integrated supply position via its Seadrift facility, serving ultra-high-power graphite electrode and specialty carbon markets. Its product portfolio expansion into lower-carbon needle coke variants signals a strategic response to demand-side environmental qualification requirements.
- ENEOS Corporation (Tokyo, Japan) leverages Japanese refining and coking assets to produce premium petroleum-based needle coke, supplying graphite electrode and battery anode manufacturers with a focus on consistent grade quality and reliability.
- Seadrift Coke L.P. (Seadrift, Texas, United States) converts Gulf Coast refinery residues into petroleum needle coke, supported by calcination capability for anode-grade material and a logistics profile aligned with North American downstream demand.
- Petrocokes Japan Ltd. (Tokyo, Japan) operates within the Sumitomo Corporation group ecosystem, concentrating on electrode and specialty applications with a regional supply orientation.
- C-Chem Co., Ltd. (Japan) serves regional electrode manufacturers, maintaining a focused production profile aligned with Asian downstream manufacturing needs.
- Chinese Petroleum & Chemical Development Company (CPCDC) (Taiwan) supports regional graphite electrode supply chains, positioning itself within East Asian demand networks that continue to scale electrode consumption.
Beyond individual profiles, the competitive vector is increasingly shaped by three operational levers: capacity expansion timing, feedstock flexibility, and product qualification for lower-emission or recycled-feedstock routes. Recent industry developments illustrate this shift. Capacity investments are being directed toward battery-grade output streams; product launches are emphasizing reduced lifecycle carbon intensity through alternative feedstock blending; and long-term supply agreements are locking in offtake for anode-scale manufacturing footprints. These moves are not isolated. They signal a market where incumbent positioning will be tested by the ability to secure consistent aromatic-rich feedstocks, navigate qualification cycles, and align with downstream decarbonization mandates.
Market Dynamics: Feedstock Volatility, Regulatory Pressure, and the Petroleum Advantage
The operating environment is defined by a set of interacting forces that repeatedly reshape cost structures, capacity utilization, and product-grade competitiveness.
- Feedstock volatility remains a primary margin variable. Petroleum needle coke production depends on highly aromatic decant oil and pitch feedstocks, and the price behavior of these streams is closely tied to crude oil and coal tar market fluctuations. FCC decant oil, derived from slurry oil after particle removal, serves as the primary aromatic-rich feedstock, making refinery throughput patterns and slurry handling economics directly relevant to coke cost curves.
- Environmental regulation is actively restructuring supply geography. Stricter regulatory frameworks in China have constrained a meaningful share of graphite electrode capacity and restricted output across multiple provinces, tightening regional availability and redirecting procurement patterns. At the same time, tightening EU carbon-footprint rules increasingly favor petroleum-based needle coke with lower lifecycle emissions relative to coal-tar routes, altering competitive dynamics in export-sensitive and compliance-driven markets.
- Qualification and downstream alignment are becoming gating factors. As battery-grade applications scale, supplier qualification cycles, consistency requirements, and traceability expectations are increasingly influential. Producers that can demonstrate stable grade performance, auditable feedstock provenance, and alignment with low-carbon or recycled-feedstock pathways are gaining preferential access to long-term agreements and premium pricing tiers.
Collectively, these dynamics create a market where cost leadership alone is no longer sufficient. Competitive advantage is increasingly a function of feedstock security, regulatory adaptation, and the ability to deliver qualified product into both traditional electrode and emerging battery value chains.
The Report: What Decision-Makers Will Find Inside
The complete Petroleum Needle Coke Market study is structured to convert high-level trajectory awareness into executable strategy. Rather than presenting static sizing alone, the report maps the operational and commercial levers that determine where growth, margin, and risk concentrate across the 2026–2032 period.
- Market sizing and forward modeling that anchor planning to verified historical baselines and forecast trajectories, enabling scenario testing around feedstock cost shifts, capacity additions, and application mix evolution.
- Segment-level structure analysis covering type partitions, application channels, and regional dispersion patterns, with emphasis on how volume distribution translates into pricing power, supply security, and qualification risk.
- Competitive profiling and strategic event tracking that examine capacity expansions, product launches, supply agreements, and regional positioning moves, highlighting how incumbents are reallocating capital and reorienting product portfolios.
- Dynamic context integration that connects raw material volatility, regulatory interventions, and carbon-intensity qualification trends to practical procurement, sourcing, and capacity-planning implications.
- Actionable framing for commercial and operational teams seeking to evaluate supplier resilience, entry timing, vertical integration logic, and long-term offtake strategy in a market where concentration and qualification barriers increasingly shape access.
The report is designed for executives who need to move beyond headline aggregates and understand the structural drivers that will determine competitive outcomes in the next investment cycle. It provides the evidentiary scaffolding required to test assumptions, pressure-test supply strategies, and align portfolio decisions with the most consequential market shifts.
Strategic Takeaway for 2026 Planning
As the petroleum needle coke market advances through its 6.7 percent CAGR window, the strategic question is no longer whether demand will expand, but where value will be captured and which supply chains will be rewarded with preferential access, premium pricing, and durable contracting relationships. The convergence of feedstock economics, regulatory recalibration, capacity concentration, and battery-grade qualification is creating a market in which operational precision and forward positioning matter more than ever.
This research study is built to help leadership teams navigate that complexity. It preserves the analytical depth required for credible strategy formulation while guiding readers toward the full dataset, segment architecture, and competitive intelligence needed for enterprise-level execution. For organizations preparing 2026 sourcing strategies, capacity commitments, or market-entry evaluations, the complete report provides the structured intelligence necessary to convert market trajectory into defensible commercial advantage.
Petroleum Needle Coke Market
Needle Coke Market
For detailed analysis of this topic, please visit the official page: Petroleum Needle Coke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


