



PW Consulting: Air Source Heat Pumps Market Hits $49.2B in 2025, Forecast 7.2% CAGR to 2032

Unlocking Strategic Value in the Air Source Heat Pumps Market: Why 2026 Decisions Require Premium Intelligence
The global air source heat pumps market is entering a decisive growth phase, with total industry revenue projected to surpass USD 51.64 billion in 2026 and continue its upward trajectory toward an estimated USD 80.45 billion by 2032. This sustained expansion, driven by a compound annual growth rate of 7.2 percent across the forecast horizon, reflects a structural pivot in building decarbonization, energy security imperatives, and rapid electrification of thermal systems. For executives, investors, and market strategists, navigating this landscape requires more than headline figures. It demands precise, forward-looking intelligence that translates macroeconomic momentum into actionable market positioning.
Our latest comprehensive study on the air source heat pumps market is purpose-built for that reality. Serving as both a baseline diagnostic and a strategic roadmap, the report equips leadership teams with the analytical rigor necessary to allocate capital, refine product portfolios, anticipate regulatory inflection points, and outperform in an increasingly competitive manufacturing and distribution ecosystem. This overview demonstrates how the study translates complex market signals into operational intelligence, while preserving the granular breakdowns that only the full publication delivers.
The Macro Trajectory: Translating Historical Momentum into 2026–2032 Decision Frameworks
The market has evolved from an estimated USD 34.25 billion in 2020 to USD 49.2 billion in 2025, demonstrating consistent year-over-year expansion across a period marked by volatile energy pricing, tightening carbon mandates, and early-stage electrification incentives. The forecast period from 2026 through 2032 maps a deliberate acceleration curve, with annual revenue crossing USD 60.96 billion by 2028 and reaching USD 71.25 billion by 2030. Such progression is not uniform across product architectures, application segments, or geographic territories. Rather, it emerges from converging technology maturation, regional policy differentiation, and supply chain realignment.
Strategic decision-making in 2026 hinges on recognizing that historical growth is not merely descriptive; it is diagnostic. The baseline trajectory reveals how capacity investments, refrigerant transitions, and installer ecosystem readiness have compounded over the past half-decade. Our report contextualizes these dynamics within a structured analytical framework, enabling clients to identify where volume expansion will be concentrated, which technological pathways will command pricing premiums, and how regional policy cycles will influence uptake velocity. The full publication contains the detailed decomposition required to align corporate roadmaps with these shifting demand vectors.
Regulatory and Technology Inflection Points Reshaping Competitive Positioning
Market expansion is being simultaneously accelerated and recalibrated by a wave of regulatory and technological shifts. The EU F-Gas regulation mandates a global warming potential below 150 for new split air conditioning and heat pump equipment starting in 2027, compelling manufacturers to accelerate migration toward low-GWP refrigerants such as R32 and R290. In the United States, the Department of Energy finalized amended energy conservation standards for air-cooled commercial package air conditioners and heat pumps, with compliance becoming effective January 1, 2029. Meanwhile, Japan revised its HFC quota management framework in 2025, pushing R-410A costs upward by more than three times relative to R-32, fundamentally altering regional cost structures and product planning.
These regulatory vectors are intersecting with proactive industrial initiatives. Mitsubishi Electric Corporation committed USD 143.5 million to retrofit a U.S. manufacturing facility for variable-speed compressor production, targeting an October 2027 operational start. Simultaneously, the New England Heat Pump Accelerator introduced a USD 450 million program designed to supercharge cold-climate air source heat pump adoption through midstream incentives, reducing per-unit deployment costs by USD 500 to USD 700. In the Northeast high-performance HVAC market, air source heat pumps now account for 32 percent of residential HVAC equipment demand, underscoring how regional specialization is reshaping equipment mix and channel economics.
Our report dissects how these interventions alter competitive advantage. It evaluates the timing of compliance deadlines against product development cycles, assesses the commercial implications of midstream incentive architectures, and projects how refrigerant pathway decisions will influence long-term serviceability, component sourcing, and after-market economics. Executives seeking to prioritize R&D investments, align capacity additions, or restructure commercial partnerships will find the regulatory impact mapping essential to avoiding stranded investments and capturing first-mover advantage in transitioning segments.
Competitive Landscape: Consolidation Dynamics and Strategic Differentiation
The market exhibits meaningful concentration, with the top three participants collectively commanding approximately 45.2 percent of industry revenue and the top five holding an estimated 62.8 percent share. Such concentration reflects decades of engineering heritage, cold-climate performance differentiation, inverter technology leadership, and global distribution scale. Yet concentration also masks rapid competitive evolution, as regional champions, technology specialists, and vertically integrated appliance manufacturers expand their footprint through targeted product launches and strategic capacity investments.
Prominent market participants include Daikin Industries, Ltd., recognized for high-efficiency inverter platforms and cold-climate monobloc and split solutions spanning residential and commercial applications; Mitsubishi Electric Corporation, distinguished by ductless and multi-split systems with Hyper-Heating technology and variable refrigerant flow architectures; and Carrier Global Corporation, offering residential and commercial platforms built around Infinity and Greenspeed inverter technology. Trane Technologies plc delivers broad split-system and packaged offerings with high-efficiency inverter configurations. From the Asian manufacturing corridor, LG Electronics, Inc. and Samsung Electronics Co., Ltd. contribute air-to-air and air-to-water lines emphasizing high coefficient of performance and residential-to-light-commercial versatility. Gree Electric Appliances Co., Ltd. and Fujitsu General Limited reinforce efficiency-focused residential and commercial portfolios, while Hitachi, Ltd. and Panasonic Corporation maintain established residential and light-commercial heat pump lines. In Europe, Bosch Thermotechnology GmbH markets air-to-air and air-to-water platforms under multiple brand architectures, and NIBE Industrier AB specializes in cold-climate residential heating and domestic hot water systems.
The competitive analysis within our report goes beyond corporate profiling. It evaluates how product architecture focus, refrigerant strategy, cold-climate engineering capability, and regional manufacturing footprint translate into share resilience or vulnerability under evolving standards. The full document provides the comparative benchmarking, segment positioning matrices, and strategic response scenarios required to assess partnership opportunities, potential acquisition targets, and defensive positioning in high-growth sub-segments.
What the Full Study Delivers: Operational Intelligence for Strategy, Capital, and Execution
This market research is engineered to support end-to-end strategic execution. It combines quantitative forecasting, structural segmentation, regulatory mapping, and competitive intelligence into a unified analytical platform. The publication is structured to help leadership teams answer the questions that determine 2026 success: where demand growth will be most durable, which technology pathways will attract premium pricing, how regulatory timelines will reshape product economics, and which competitive moves will determine market access.
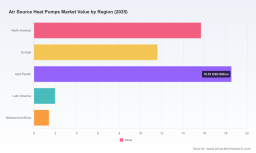
Key analytical dimensions include a comprehensive historical-to-forecast revenue trajectory, enabling clients to benchmark internal performance against market momentum and identify inflection points in demand expansion. The study presents rigorously defined segmentation architecture, allowing teams to isolate the segments with the strongest growth elasticity, highest margin potential, and most favorable policy tailwinds. Regional demand mapping clarifies where capacity deployment, distributor expansion, and service infrastructure investment will generate the highest strategic return. Competitive profiling and concentration analysis equip strategists with the intelligence required to anticipate share shifts, evaluate barrier-to-entry dynamics, and refine go-to-market positioning.
Worldwide Absorption Heat Pumps Market
Beyond structural analysis, the report integrates forward-looking operational considerations. It assesses how midstream incentive frameworks alter installed-cost economics and influence buyer behavior. It maps the timing and commercial implications of refrigerant transitions relative to product lifecycles and component supply chains. It examines how efficiency standard revisions will affect competitive parity across residential and commercial equipment categories. These elements are synthesized into scenario-based guidance, enabling decision-makers to test strategic assumptions against plausible regulatory and market pathways rather than relying on static projections.
The full study also provides the detailed quantitative backing necessary for internal validation. Executive teams can use the underlying decomposition to align sales forecasting, production planning, channel investment, and R&D prioritization with verified market trajectories. Investors and corporate development professionals gain a structured basis for evaluating segment attractiveness, competitive durability, and capital allocation efficiency across the forecast horizon.
Strategic Imperatives for 2026: Aligning Decision-Making with Market Reality
As the market advances toward the 2026 revenue milestone and continues its expansion through the early 2030s, several strategic imperatives will separate resilient players from reactive competitors. First, product planning must integrate refrigerant pathway decisions with long-term compliance timelines, ensuring that portfolio architectures are aligned with low-GWP migration without sacrificing performance or service economics. Second, capacity and manufacturing investments need to account for variable-speed compressor demand, cold-climate performance requirements, and regional standards timelines, particularly as major industrial retrofits reshape supply availability. Third, commercial strategy should recognize that incentive structures and regional policy momentum create uneven demand curves, requiring differentiated market entry, pricing, and channel approaches rather than uniform global execution.
Fourth, competitive positioning must reflect the reality that concentration masks rapid product-level and segment-level disruption. Organizations that depend solely on historical share as a proxy for future resilience risk underestimating the impact of efficiency standards, cold-climate performance differentiation, and regional technology convergence. The companies that will capture disproportionate value are those that combine engineering discipline with proactive regulatory anticipation and flexible commercial architecture.
Our report is designed to support each of these imperatives. It provides the analytical scaffolding necessary to convert high-level market growth into detailed strategic action, while preserving the proprietary breakdowns, comparative matrices, and scenario analyses that require full access to the publication. Readers evaluating the air source heat pumps opportunity for capital deployment, product planning, M&A assessment, or channel expansion will find the complete study essential for informed, forward-looking decision-making.
Air Source Heat Pumps Market
Next Steps: Accessing the Full Intelligence Architecture
The macro trajectory, regulatory shifts, competitive concentration, and incentive dynamics described here represent only the entry point to a far more granular analytical framework. The complete market study delivers the segment-level resolution, regional demand mapping, competitive benchmarking, and scenario-based forecasting required to translate market momentum into executable strategy. For organizations preparing 2026 investment decisions, portfolio adjustments, or market-entry plans, the full report provides the evidence base needed to prioritize with confidence and act ahead of inflection points.
Access the complete analysis to obtain the detailed market size decomposition, strategic segmentation insights, competitive positioning frameworks, and forward-looking regulatory impact assessments that will shape your 2026–2032 decision architecture.
For detailed analysis of this topic, please visit the official page: Air Source Heat Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


