



PW Consulting: Privacy Management Software Market Hits $7.36B in 2025, Projected to Surge at 37.4% CAGR Through 2032

Navigating the Privacy Management Software Market: Strategic Intelligence for 2026 and Beyond
The privacy technology landscape has entered a decisive inflection point. Organizations are no longer treating compliance as a periodic checklist or a back-office function. Instead, privacy management has become a core operational capability, intrinsically linked to customer trust, risk mitigation, and scalable digital transformation. Our latest Privacy Management Software Market research report translates this structural shift into a clear, actionable intelligence framework designed specifically for enterprise strategy teams, procurement leaders, and technology architects planning their 2026 roadmaps.
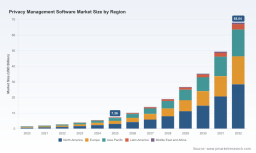
Drawing on a rigorous historical baseline spanning 2020 through 2025, the analysis extends its forward-looking lens through 2032. Over the past five years, the sector has witnessed a remarkable acceleration in capital allocation and vendor maturation. Market revenue grew from 1.5 billion USD in 2020 to 7.36 billion USD in 2025, underscoring how quickly privacy has evolved from a niche regulatory response into a mainstream enterprise priority. The trajectory does not flatten in the near term. Forecasts project continued expansion to 10.21 billion USD in 2026, with sustained momentum carrying the market toward 68.04 billion USD by 2032. Driving this expansion is a forecasted compound annual growth rate of 37.4 percent, a figure that signals far more than incremental adoption. It reflects a fundamental redesign of how organizations discover, classify, govern, and operationalize data across increasingly complex regulatory and technological environments.
For decision-makers navigating 2026, these numbers translate into critical strategic realities. Budgets are no longer discretionary. Privacy software is transitioning into a foundational layer of enterprise architecture, demanding careful evaluation of integration pathways, automation maturity, and long-term vendor viability. The research report is built to cut through marketing noise and equip leaders with the analytical rigor required to allocate resources, prioritize implementation sequences, and future-proof compliance operations.
Privacy Management Software Market
Market Dynamics Reshaping Enterprise Priorities
No enterprise privacy strategy can be designed in isolation from the regulatory and operational pressures shaping today’s compliance environment. Enforcement intensity has become a defining market catalyst. According to the GDPR Enforcement Tracker, 2026 alone has already recorded 143 fines, contributing to a cumulative total of over €6.29 billion across 3,186 recorded actions since 2018. This enforcement cadence is not merely a legal statistic; it is a direct signal that supervisory authorities are operationalizing privacy obligations with escalating precision and financial consequence.
In parallel, regional regulatory bodies are expanding the scope of obligations beyond traditional data handling. The California Privacy Protection Agency issued its first enforcement advisory on data minimization in April 2024, paired with ongoing proposed updates to the CCPA and CPRA frameworks, including forthcoming rules on automated decision-making technology. These developments illustrate a broader trend: regulators are no longer only scrutinizing static compliance artifacts. They are increasingly focused on how organizations architect data flows, manage consent dynamically, and govern emerging data processing activities in real time.
The operational strain of this expanding landscape is measurable. The PwC Global Compliance Survey from 2025 reveals that 77 percent of companies report negative business impact stemming from compliance complexity across multiple growth areas. When privacy obligations intersect with product innovation, M&A activity, cross-border data transfers, and third-party ecosystems, fragmented toolsets and manual workflows quickly become strategic bottlenecks. This is precisely where modern privacy management software enters as a structural enabler rather than a reactive safeguard.
What the Research Delivers: Operational Intelligence, Not Surface-Level Forecasts
This report is engineered for practitioners who must convert market intelligence into tangible operational decisions. Rather than presenting static snapshots, the analysis provides a comprehensive examination of how privacy management software is deployed across enterprise workflows, how solution categories diverge in capability, and where integration complexity most frequently derails implementation timelines.
The research maps the functional architecture of the market across its dominant solution types. Organizations are increasingly investing in regulatory compliance management as a central orchestration layer, while data discovery and mapping capabilities serve as the foundational prerequisite for accurate inventory, classification, and downstream governance. Risk assessment and management modules are gaining traction as boards and audit functions demand quantified exposure frameworks, while consent and preference management, incident and breach response, and other emerging capabilities round out the operational continuum. The report also examines how these capabilities converge within applied use cases, including privacy impact assessment and reporting, data subject request fulfillment, vendor and third-party risk oversight, and governance around incident response.
Beyond functional taxonomy, the study delivers a granular view of deployment considerations, vendor evaluation criteria, and implementation readiness factors. It investigates how enterprises are aligning privacy platforms with existing data governance structures, security operations, and customer experience architectures. Readers will find structured analysis on procurement pathways, integration dependencies, scalability thresholds, and the operational maturity required to transition from fragmented point solutions to unified privacy orchestration.
Critically, the report is designed to support scenario planning. It frames adoption trajectories within the context of organizational size, data environment complexity, regulatory exposure, and internal capability maturity. This allows strategy teams to model investment pacing, prioritize capability acquisition, and anticipate where automation will deliver the highest return on compliance efficiency.
Competitive Landscape: Platform Evolution and the Rise of Agentic Automation
The vendor ecosystem has matured rapidly, with leading providers differentiating through automation depth, data connectivity breadth, and cross-jurisdictional compliance orchestration. Market concentration currently reflects a moderately dispersed landscape, with the top three providers accounting for 26.2 percent of revenue and the top five capturing 39.5 percent. This structure indicates both vigorous competition and room for specialized innovators to gain footholds in high-value operational niches.
Several established and emerging players define the current competitive frontier. OneTrust, headquartered in Atlanta, Georgia, has advanced as an AI-ready governance platform emphasizing privacy automation, consent management, data subject rights fulfillment, and multi-jurisdictional compliance workflows. BigID, based in New York, has positioned its data security and privacy platform around AI-driven discovery, classification, and governance for sensitive data spanning cloud, on-premises, and AI systems. TrustArc, operating from Walnut Creek, California, provides a privacy management and consent platform supported by certification capabilities, DPIA automation, and global compliance tooling. DataGrail, in San Francisco, offers an agentic data privacy platform focused on consent management, data subject rights fulfillment, and risk assessment workflows. Transcend, also based in San Francisco, functions as a compliance layer for customer data, delivering consent management, data subject request automation, and preference management. Ketch, likewise headquartered in San Francisco, delivers enterprise privacy orchestration software spanning consent, data subject access requests, data mapping, assessments, and AI-ready data governance. IBM contributes through its broader enterprise portfolio, with Guardium Data Protection supporting data discovery, classification, and compliance across hybrid environments aligned with frameworks such as GDPR, CCPA, and PCI.
Recent product movements underscore how quickly the market is shifting toward automation intensity and AI-augmented governance. In March 2026, BigID introduced a unified privacy management platform expansion covering preference portals, deletion workflows, and AI data governance across structured and unstructured data assets. A few months later, in May 2026, Ketch launched the Ketch Agent Network, a multi-agent AI orchestration layer designed to support agentic data mapping, risk management, and assessment workflows within privacy programs. These releases illustrate a broader industry trajectory: privacy software is no longer confined to policy documentation or manual task routing. The frontier is now defined by orchestrated, intelligent workflows that reduce manual burden, accelerate response cycles, and embed compliance logic closer to operational data systems.
Legal Practice Management Software Market
Strategic Implications for 2026 Decision-Making
The convergence of enforcement pressure, regulatory expansion, and automation-driven platform evolution creates a clear mandate for enterprise leaders. Privacy management software is no longer a tactical purchase; it is a strategic capability that directly influences operational agility, risk exposure, and cross-functional coordination. Organizations that approach procurement with fragmented intent risk compounding complexity, while those that evaluate platforms through the lens of architectural fit, automation depth, and long-term scalability are better positioned to convert compliance obligations into competitive advantage.
This research report provides the analytical scaffolding required to make those evaluations with confidence. It illuminates where market growth is concentrated, how solution capabilities are diverging, and what implementation maturity looks like in practice. It also frames the vendor landscape in a way that supports comparative assessment without reducing complex platforms to superficial feature checklists.
For executives planning 2026 investments, the most valuable insight is structural rather than numerical. The market is scaling at a pace that rewards early architectural clarity. Enterprises that define privacy orchestration requirements, data discovery dependencies, and automation priorities now will face fewer integration bottlenecks, lower total cost of ownership, and stronger alignment between compliance operations and business objectives. Delaying that clarity until after procurement often results in reactive vendor selection, overlapping toolsets, and diminished returns on compliance investment.
The complete analysis extends well beyond the macro trajectory and competitive snapshots outlined here. Detailed segmentation intelligence, vendor evaluation frameworks, deployment sequencing models, and forward-looking scenario insights are provided in the full report. Readers seeking a comprehensive, decision-ready view of the Privacy Management Software Market are encouraged to access the complete research on the source page, where deeper segmentation breakdowns, vendor profile comparisons, and implementation pathway guidance are available in full.
For detailed analysis of this topic, please visit the official page: Privacy Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


