



PW Consulting: Zener Diodes Market to Hit $1,063.11M by 2032, 4.2% CAGR

Navigating the Voltage Landscape: Strategic Imperatives in the Global Zener Diodes Market Through 2032
Executive Summary
In the complex ecosystem of modern electronics, few components are as fundamentally critical yet often overlooked as the Zener diode. Serving as the guardian of voltage stability, this discrete device underpins the reliability of everything from automotive control units to high-performance computing infrastructure. As we move further into the decade, the Zener Diodes Market presents a nuanced narrative of steady growth tempered by intense competitive dynamics and supply chain volatility. PW Consulting's latest comprehensive study offers a definitive roadmap for stakeholders aiming to capitalize on these shifts between 2026 and 2032.
The global market for Zener diodes is projected to demonstrate resilient growth, driven by the expanding electrification of transport, the ubiquitous nature of consumer electronics, and the increasing sophistication of industrial automation. Our analysis indicates that the market valuation is on a consistent upward trajectory, building upon the foundations laid in the post-pandemic recovery period. With the base year established at 2025 and forecast extending through 2032, this research provides a granular look at revenue streams measured in USD Million. The compound annual growth rate (CAGR) clocking in at 4.2 percent signals a mature but expanding sector where incremental gains are tied directly to technological innovation and geographic market penetration.
For strategic planners and procurement leaders, understanding the magnitude of this growth is only the first step. The real value lies in dissecting the drivers behind the numbers. The transition from historical analysis covering 2020 to 2025 into the forecast period allows organizations to benchmark their performance against market rhythms. The historical data reveals a steady climb from earlier valuation points, reflecting renewed demand cycles and the normalization of supply chains. As we look toward the 2032 horizon, the revenue projections suggest a market that is not only growing in size but also evolving in complexity, requiring a more sophisticated approach to market entry and expansion.
Zener Diodes Market
The Voltage of Competition: Key Players and Strategic Moves
The competitive landscape of the Zener Diodes Market is characterized by a mix of established semiconductor giants and specialized manufacturers. Market concentration metrics indicate that while the top players hold significant sway, there remains ample room for differentiation through technology and packaging innovation. The CR3 and CR5 values suggest a moderately consolidated environment where strategic partnerships and product portfolio breadth are key differentiators.
Texas Instruments continues to reinforce its position through aggressive portfolio expansion. In a recent move during January 2026, the company introduced Zener diodes as part of its growing protection devices portfolio, specifically targeting voltage regulation and overvoltage protection needs. This release coincides with updated data sheets for their BZX84Cx and BZX884Cx series, transitioning these devices from advanced status to full production. Such moves highlight a focus on stabilizing supply for high-yield production environments, where process control and capability analysis are paramount.
Diodes Incorporated remains a critical player focused on precision and package technology. Their recent catalog updates in December 2025 showcased surface-mount and leadless Zener diodes with voltage tolerances as tight as plus or minus 2.0 percent. This level of precision is crucial for applications requiring stringent voltage stability. However, the company also navigates the turbulent waters of supply chain dynamics, having experienced significant lead time expansions due to broader component demand shifts. This dual reality of high-precision offering and supply chain pressure underscores the volatility inherent in the sector.
Toshiba Electronic Devices & Storage Corporation has tailored its offerings toward robust protection in power lines and semiconductor devices. The launch of the CMZBxxA series in November 2025 introduced a new planar structure designed to protect against switching surges and overvoltage pulses close to DC. With AEC-Q101 qualification and PPAP capability, Toshiba is positioning its Zener diodes to meet the stringent reliability standards required in automotive applications. This regulatory alignment is a critical barrier to entry for competitors and a key trust signal for automotive OEM procurement teams.
Vishay Intertechnology, Inc. is pushing the boundaries of miniaturization and power handling. Their expansion in October 2025 included new leadless sidewall plated DFN1006-2A packages, enabling next-generation designs where space is at a premium. By offering automotive-qualified and PPAP capable parts alongside standard SMD options, Vishay addresses the dual needs of high-volume consumer manufacturing and specialized automotive supply chains. The use of silicon planar technology across their lineup ensures consistent performance across power ratings ranging from less than 350 mW to over 500 mW.
Nexperia Holding B.V. focuses on reducing noise and enhancing reliability for industrial and automotive designs. Their portfolio enhancements include new 50 microampere series and A-selection series with plus or minus 1 percent tolerance. These enhancements are designed to eliminate overswing and reduce noise, catering to sensitive electronic environments. Meanwhile, Microchip Technology Inc. and onsemi continue to broaden the availability of Zener diodes for general-purpose voltage regulation and transient overvoltage protection respectively, ensuring that the market remains well-supplied across diverse application verticals.
Segmentation Dynamics: Technology and Application Vectors
Understanding where value is generated within the market requires a look at the segmentation splits without losing sight of the overarching trends. The market is broadly divided by technology type and application sector, each presenting unique growth vectors and challenges.
Technology segmentation reveals a preference for specific packaging and mounting solutions that align with modern design constraints. Surface Mount Technology continues to hold a significant share of the market revenue, reflecting the industry wide shift toward miniaturized and automated assembly processes. Through Hole Technology maintains a substantial presence, particularly in applications where mechanical robustness and higher power handling are prioritized. The balance between these two technology types is shifting gradually as design architectures evolve toward denser integration, yet the legacy needs of industrial and heavy-duty sectors keep Through Hole technology relevant.
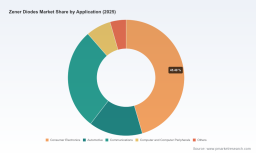
On the application front, the demand landscape is diverse. Consumer Electronics remains a dominant force, driven by the sheer volume of devices requiring voltage protection and regulation. Communications infrastructure also represents a substantial portion of the market, reflecting the need for reliable power management in network equipment and telecommunications hardware. The Automotive sector is experiencing a transformation, with Zener diodes playing a critical role in the increasing number of electronic control units and power management circuits within modern vehicles. Computer and Computer Peripherals constitute another vital segment, where stability and protection are non-negotiable for data integrity. Other applications collectively contribute to the market volume, encompassing specialized industrial and aerospace needs.
It is within these segments that the strategic opportunities lie. While the aggregate numbers show growth, the rate of adoption varies significantly across regions and sectors. Organizations must identify which segment aligns best with their technological capabilities and supply chain resilience. The interaction between technology type and application requirements often dictates the specific product specifications needed, such as voltage tolerance, power rating, and package size.
Market Dynamics and Operational Realities
The operational environment for Zener diodes is influenced by a confluence of supply chain, regulatory, and production factors. Recent industry intelligence highlights specific dynamics that cannot be ignored when formulating strategy for the 2026 to 2032 period.
Rectifier Diode Market
Supply chain stability remains a primary concern. There have been instances where lead times for Zener diodes and related components expanded significantly, moving from standard weeks to extended periods due to demand surges in adjacent sectors such as AI server motherboards. Price increases across product lines have also been observed, reflecting the inflationary pressure and component scarcity that can ripple through the discrete semiconductor market. Understanding these lead time fluctuations and their correlation with demand spikes in high-growth sectors is essential for inventory management and cost forecasting.
Regulatory compliance is another pillar of market dynamics. With the automotive sector demanding higher reliability, qualifications such as AEC-Q101 and capabilities like PPAP are becoming standard expectations rather than optional differentiators. Manufacturers that can demonstrate compliance with these stringent standards gain a competitive advantage in securing long-term contracts with automotive suppliers. This regulatory layer adds complexity to production but also serves as a moat for established players who have invested in quality assurance infrastructure.
Production processes are evolving to meet the needs of next-generation designs. The adoption of advanced wafer processes and leadless package technologies enables manufacturers to offer components that are smaller, more efficient, and more reliable. Miniaturization continues to be a key driver, as electronic devices become more compact. Providers that can maintain high yield production through rigorous process control while shrinking form factors are well-positioned to capture market share. The ability to verify capability analysis metrics during new product qualification ensures that volume production meets quality expectations from the outset.
Material technology also plays a role in defining product boundaries. The use of silicon planar technology allows for a wide range of power ratings, accommodating diverse application needs from low-power signal protection to higher-power regulation. New package innovations, such as leadless DFN structures, enable integration into designs where space constraints previously limited component choices. These material and packaging advancements are not merely technical specs but strategic assets that enable customers to innovate in their own product development cycles.
Strategic Recommendations for 2026 and Beyond
Based on the comprehensive data and qualitative insights gathered in this study, several strategic imperatives emerge for stakeholders operating in the Zener Diodes Market.
First, supply chain resilience must be prioritized. Given the observed volatility in lead times and pricing, organizations should diversify their supplier base and maintain strategic safety stocks for critical voltage regulation components. Engaging with suppliers who demonstrate robust process control and production capability can mitigate the risk of disruption.
Second, product portfolio alignment is crucial. As automotive and industrial applications demand higher reliability and tighter tolerances, manufacturers should focus on expanding offerings that meet AEC-Q101 standards and offer precision voltage regulation. The shift toward leadless and surface-mount packages suggests that investing in packaging technology innovation will yield competitive returns as designs become more constrained.
Third, geographic and application-specific targeting should guide expansion efforts. While the total market size offers a broad opportunity, growth is not uniformly distributed. Understanding which regions and application segments are driving the specific growth vectors allows for more efficient resource allocation. Companies should tailor their messaging and technical support to the specific pain points of each segment, whether it is noise reduction for industrial users or surge protection for automotive engineers.
Fourth, monitoring competitive developments is essential. The recent product launches and catalog updates by key players indicate a rapidly evolving landscape. Keeping abreast of new series introductions, package innovations, and qualification achievements allows organizations to anticipate market shifts and adjust their strategies proactively.
Finally, long-term planning should account for the forecasted trajectory through 2032. The consistent growth rate suggests a stable demand environment, but the competitive intensity means that margin protection and value-added services will become increasingly important. Partnerships, co-development opportunities, and deep integration with customer design cycles can create sticky relationships that withstand price competition.
Conclusion
The Zener Diodes Market stands at a pivotal juncture where steady demand growth intersects with rapid technological evolution and supply chain complexity. For decision-makers in 2026, the ability to navigate these dynamics will define success in the coming years. This market research provides the foundational intelligence required to make informed strategic choices, from product development to market entry. However, the full depth of segmentation data, regional analysis, and competitive benchmarking is detailed in the complete report. We invite you to access the full study to unlock the specific insights necessary to drive your organizational strategy forward in this critical component market.
For detailed analysis of this topic, please visit the official page: Zener Diodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


