



PW Consulting: Automotive EPS Market to Hit $397M by 2032, 5.57% CAGR Forecasted

Navigating the Torque Shift: Strategic Imperatives in the Global Automotive Electronic Power Steering Market Through 2032
The automotive industry is currently undergoing one of the most significant paradigm shifts in steering technology since the invention of the rack-and-pinion system. The transition from hydraulic power steering (HPS) to Electronic Power Steering (EPS) is no longer merely an incremental improvement in energy efficiency; it is the foundational enabler for modern Advanced Driver Assistance Systems (ADAS), autonomous driving capabilities, and rigorous emissions compliance. For original equipment manufacturers (OEMs) and tier-one suppliers alike, understanding the trajectory of the EPS market is not optional—it is a prerequisite for strategic resilience.
PW Consulting's latest comprehensive market research report offers a granular examination of the Automotive Electronic Power Steering sector, providing stakeholders with the intelligence necessary to navigate the forecast period from 2026 to 2032. This article serves as a strategic overview of the market landscape, highlighting the macro-economic trends, regulatory pressures, and competitive dynamics that define this critical automotive subsystem.
Market Trajectory and Macroeconomic Environment
The global demand for electronic power steering systems has demonstrated robust growth over the past half-decade, driven by consumer preference for lighter steering feel, improved fuel economy, and the increasing electronic content in vehicles. Historical data from 2020 through 2025 indicates a consistent upward trend in revenue, reflecting the widespread adoption of EPS across various vehicle segments. As the industry moves into the forecast period, the market is projected to sustain a healthy compound annual growth rate, signaling continued investment opportunities in manufacturing capacity and R&D.
By the base year 2025, the aggregate market revenue had reached substantial levels in millions of USD, establishing a strong platform for the forecast years. The projected figures for 2026 and beyond suggest that while the pace of electrification may fluctuate based on regional economic conditions, the underlying demand for steering assist technology remains inelastic. This stability is underpinned by the fact that EPS is now the standard for nearly all new passenger vehicle platforms, displacing legacy hydraulic systems that carry parasitic energy losses.
It is crucial for decision-makers to recognize that the market size expansion is not uniform across all years. Forecasts indicate a gradual acceleration as newer vehicle architectures mature and as regulatory mandates fully take effect in key markets. Understanding the specific revenue projections for each forecast horizon is essential for capacity planning and supply chain optimization, details of which are extensively mapped out in the full report.
Regulatory Catalysts and Technology Dynamics
Regulatory frameworks are acting as potent accelerants for the adoption of EPS technologies. In Europe, the Union's commitment to reducing carbon emissions has directly impacted steering system specifications. With the Euro 7 regulation applicable to new type approvals from 2025, hydraulic power steering has effectively been eliminated from new passenger car specifications due to the parasitic CO2 penalty calculations associated with engine-driven pumps. This regulatory hard line forces manufacturers to prioritize electric solutions that decouple steering power from engine load.
Furthermore, safety standards are evolving to require active intervention rather than passive assistance. The Euro NCAP 2026 protocol now requires lane-keeping assistance as a rated safety feature. This mandate necessitates EPS torque overlay capability across all new passenger vehicle platforms seeking five-star ratings. Consequently, the EPS system is no longer just a comfort feature; it is a critical safety component that must integrate seamlessly with camera and radar inputs to execute corrective steering maneuvers.
Parallel to regulatory pressure, technological innovations are reshaping the competitive landscape. The development of solid-state and sensor-based EPS technologies is improving reliability while reducing system complexity. Modern EPS gearboxes are being engineered with high-strength materials and precision manufacturing techniques that not only improve durability but also reduce noise, vibration, and harshness (NVH)—a key differentiator in premium vehicle segments. Additionally, the shift toward steer-by-wire systems represents the next frontier, removing the mechanical connection between the steering wheel and the wheels entirely, offering unparalleled flexibility in vehicle packaging and human-machine interface design.
Competitive Landscape and Key Player Strategies
The market structure is characterized by high concentration, with a few dominant players holding significant sway over pricing, technology standards, and supply chain dynamics. The top three companies command a substantial share of the market revenue, while the top five entities collectively control an even larger portion of the industry output. This oligopolistic structure suggests that collaboration, strategic partnerships, and first-mover advantages in new technology segments are critical for maintaining market position.
Several key manufacturers are driving these trends through targeted product launches and strategic expansions:
-
Nexteer Automotive , based in Auburn Hills, Michigan, continues to diversify its portfolio beyond traditional column and pinion assist systems. Recently, they initiated series production of a steer-by-wire system as part of a full drive-by-wire chassis program for a leading Chinese New Energy Vehicle (NEV) manufacturer. This move signifies a strategic pivot toward next-generation architectures where steering is fully integrated into the software-defined vehicle ecosystem.
-
China Automotive Systems, Inc. has been aggressively expanding its geographic footprint. Following the award of its first South American C-EPS contract for a new vehicle platform from a leading local manufacturer, the company began volume shipments of EPS systems to a global automaker's European division for two new vehicle models. This demonstrates the increasing competitiveness of Chinese suppliers in established Western markets.
-
JTEKT Corporation confirmed the installation of next-generation steer-by-wire backup power and components in the Lexus RZ production BEV. This validation by a premium brand underscores the reliability challenges inherent in steer-by-wire technology and highlights the importance of redundancy systems in ensuring consumer trust.
-
Other major players such as Robert Bosch GmbH , ZF Friedrichshafen AG , N SK Ltd. , and Denso Corporation continue to refine integrated EPS solutions, focusing on energy-efficient designs and ADAS integration capabilities. Meanwhile, regional champions like Mando Corporation and Hyundai Mobis Co., Ltd. are leveraging their positions within Korean conglomerates to supply premium and volume vehicle platforms with rack-type and column-type systems.
The interplay between these companies involves a complex mix of patent licensing, joint development agreements, and vertical integration strategies. Understanding the specific supply relationships and technology ownership claims among these entities is vital for assessing supply chain risk.
Strategic Segmentation and Application Insights
While the overall market figures provide a top-down view, the true value lies in understanding the dynamics of specific segments. The market is broadly categorized by type, region, and application, each with unique growth drivers and constraints.
In terms of technology type, the market includes Column Assist EPS, Pinion Assist EPS, and Rack Assist EPS systems. Each configuration offers distinct advantages regarding packaging space, steering feel, and cost profile. Rack Assist systems often dominate in terms of revenue volume due to their prevalence in larger vehicles and trucks where higher torque assistance is required. However, Column Assist systems remain prevalent in smaller, cost-sensitive passenger cars. The choice of technology often depends on the vehicle class and the required integration with ADAS features.
Geographically, the market is diversified with significant contributions from North America, Europe, and Asia Pacific. Asia Pacific typically leads in volume due to the high production rates of passenger cars and commercial vehicles in the region. Europe remains a critical market driven by stringent emissions regulations and a strong presence of premium OEMs demanding high-performance steering solutions. North America continues to be a hub for innovation, particularly in steer-by-wire development. Latin America and the Middle East & Africa represent emerging growth areas, often driven by cost-effective manufacturing hubs and increasing vehicle ownership rates.
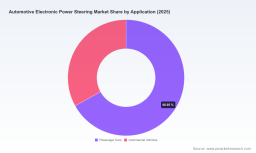
By application, the market is primarily split between Passenger Cars and Commercial Vehicles. Passenger cars account for the majority of the revenue share, reflecting the sheer volume of production and the mandatory nature of EPS in modern sedans, SUVs, and hatchbacks. Commercial vehicles, including heavy-duty trucks and buses, represent a high-growth niche. As fleet operators seek to reduce operational costs and comply with urban emissions zones, the electrification of steering systems in commercial vehicles is gaining momentum. The specific revenue splits and volume distributions between these applications are detailed in the full dataset, providing precise guidance for segment-specific targeting.
Automotive Electronic Power Steering Market
Implications for 2026 and Beyond
As we move deeper into the forecast period, several strategic implications stand out for industry participants. First, the integration of EPS with vehicle-wide electronic architectures will become a key differentiator. Suppliers who can offer scalable steering solutions that integrate seamlessly with autonomous driving stacks will capture greater value than those offering standalone components.
Second, supply chain resilience is paramount. The reliance on specific electronic components, sensors, and high-strength materials means that disruptions in semiconductor or raw material markets can have outsized impacts on EPS production. Companies must evaluate their supplier diversification strategies and consider localized manufacturing to mitigate geopolitical risks.
Worldwide Automotive Power Steering Market
Third, the rise of Chinese suppliers in European and South American markets suggests that cost competitiveness will remain a primary battleground. Western manufacturers must innovate not just in performance but also in manufacturing efficiency to maintain margins amidst intensifying competition.
Finally, the transition toward steer-by-wire technology, while still in its early stages relative to traditional EPS, will likely accelerate as regulatory approvals streamline and consumer acceptance grows. Early movers in this space have the opportunity to define the standards and interfaces that will govern steering systems for the next decade.
Unlocking the Full Intelligence
This overview provides a high-level synthesis of the Automotive Electronic Power Steering market dynamics, highlighting the critical intersection of regulation, technology, and competition. However, for executives and analysts who need to make precise investment decisions, allocate marketing budgets, or formulate sourcing strategies, a higher resolution of data is required.
PW Consulting's full market research report contains detailed quantitative forecasts, end-user consumption analysis, and granular segmentation data that remain essential for tactical planning. The complete report delves into specific revenue projections for each year through 2032, breaks down market share estimates by region and type with precision, and provides in-depth company profiles that include financial health assessments and product pipeline analyses.
To access the comprehensive intelligence needed to navigate the complexities of the EPS market, stakeholders are encouraged to refer to the full publication. Understanding the exact magnitude of growth, the competitive intensity in specific niches, and the timing of regulatory impacts will be the difference between leading the market and reacting to it.
The road ahead for automotive steering is electric, integrated, and increasingly autonomous. Armed with the right data, industry leaders can steer their organizations toward sustainable growth and technological leadership in this evolving landscape.
For detailed analysis of this topic, please visit the official page: Automotive Electronic Power Steering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


