



PW Consulting: DEIPA Market to Hit $344.8M by 2032, CAGR 6.98%

Unlocking Growth Trajectories in the Diethanol Isopropanolamine Market: A Strategic Imperative for 2026
The global chemical landscape is undergoing a quiet but decisive transformation, and at the center of this shift lies Diethanol Isopropanolamine, commonly known as DEIPA. Once confined to niche industrial applications, DEIPA has evolved into a critical enabler across construction chemistry, advanced materials, and precision manufacturing. As organizations navigate an era defined by supply chain recalibration, regulatory tightening, and demand concentration in high-value sectors, understanding the DEIPA market is no longer optional. It is a strategic necessity. Our latest comprehensive market study delivers exactly that clarity, providing enterprise leaders with the analytical rigor required to make informed capital allocation, sourcing, and expansion decisions throughout the forecast window.
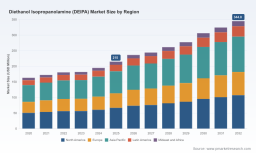
The narrative arc of this market is compelling. Drawing from historical data spanning 2020 through 2025, the industry has demonstrated consistent expansion, culminating in a robust baseline valuation that sets the stage for an accelerated growth trajectory. The report projects a compound annual growth rate of 6.98 percent across the 2026 to 2032 period, pushing the market toward a multi-hundred-million-dollar valuation by the end of the forecast horizon. These macro indicators are not merely statistical artifacts. They reflect underlying structural shifts in how industrial chemicals are sourced, formulated, and deployed across increasingly specialized end-use environments. For corporate strategists, procurement directors, and market entry teams, this growth vector signals both opportunity and complexity. The challenge lies in translating broad market momentum into actionable, segmented intelligence that aligns with organizational capability and risk tolerance.
This is precisely where executive decision-makers encounter friction. Aggregate market size and headline growth rates offer direction, but they rarely provide the granularity required to model capacity expansion, pricing strategy, or regional prioritization. Our research framework is designed to bridge that gap. By dissecting demand drivers, supply chain dynamics, regulatory pressure points, and competitive positioning, the study equips stakeholders with a multidimensional view of where value is being created, where bottlenecks are emerging, and how incumbents and newcomers are positioning themselves for the next cycle. The objective is not to overwhelm with volume, but to deliver precision. Every analytical layer serves a practical purpose: reducing uncertainty, sharpening scenario planning, and enabling faster, more confident execution.
Diethanol Isopropanolamine (DEIPA) Market
Decoding the Structural Architecture of DEIPA Demand
DEIPA's growth story is fundamentally tied to its functional versatility. As a specialized chemical intermediate and performance additive, it serves applications where consistency, purity, and formulation compatibility are non-negotiable. The market's demand architecture reflects this reality, with certain application verticals commanding disproportionate share due to their sensitivity to chemical performance and their growth momentum in high-tech and infrastructure sectors. Understanding which verticals are expanding, which are consolidating, and how feedstock volatility influences pricing behavior is essential for any organization operating in or adjacent to this space.
From a supply-side perspective, the DEIPA ecosystem is characterized by a concentrated but strategically active manufacturing base. The report examines how leading producers are navigating raw material fluctuations, particularly around isopropanolamine and diethanolamine, whose pricing can swing sharply in response to global market instability. These input cost dynamics are not abstract concerns. They directly impact margin structures, inventory strategies, and long-term contract positioning. Organizations that integrate feedstock risk modeling into their procurement and production planning gain a measurable advantage, especially when competing in price-sensitive or specification-driven segments.
Equally critical is the role of product differentiation. Within the DEIPA market, performance tiers and purity specifications increasingly dictate commercial outcomes. The study maps how different product configurations align with specific industrial requirements, revealing where premium positioning can sustain pricing power and where volume-driven strategies may be necessary to capture scale. This segmentation lens allows companies to avoid the common trap of treating DEIPA as a homogeneous commodity, and instead approach it as a portfolio of distinct value propositions with varying margin profiles, customer retention characteristics, and entry barriers.
Navigating Regulatory Friction and Cost Dynamics
Growth in the DEIPA market does not occur in a vacuum. Environmental and compliance frameworks are reshaping production economics, particularly in mature markets where regulatory scrutiny has intensified. The research highlights a clear pattern: stringent environmental requirements in North America and Europe are elevating production costs for DEIPA manufacturers, forcing a strategic recalibration of operating models. Compliance is no longer a peripheral consideration. It is a core determinant of competitive positioning, capacity utilization, and regional sourcing strategy.
The operational reality on the ground is stark. A significant portion of global producers are encountering environmental compliance hurdles that affect throughput, capital planning, and time-to-market for new formulations. Nearly half of surveyed manufacturers report restrictions related to volatile organic compounds as a meaningful restraint, while more than half cite broader compliance challenges as direct pressure points on their operational footprint. These figures underscore a market where regulatory agility is becoming a differentiator. Companies that proactively invest in emission control, process optimization, and documentation readiness are better positioned to sustain production continuity, while those that treat compliance as reactive overhead risk margin erosion and supply disruption.
Worldwide N-Methyl Diethanolamine (MDEA) Market
Raw material volatility further compounds this environment. Because DEIPA production depends on precursor chemicals that are exposed to global pricing instability, manufacturers must balance cost pass-through mechanisms with customer retention strategies. The report explores how leading firms are structuring hedging approaches, renegotiating supply agreements, and adjusting formulation strategies to preserve competitiveness without sacrificing compliance standards. For procurement and commercial teams, these insights are vital. They reveal where pricing negotiations are likely to face resistance, where long-term contracts can create structural advantage, and where regional regulatory divergence may open arbitrage opportunities for organizations with multilateral sourcing capabilities.
Competitive Positioning and the Landscape of Strategic Operators
The DEIPA market is not dominated by a single monolithic player. Instead, it features a coalition of specialized producers, regional manufacturers, and distribution networks that collectively shape supply availability, technical service expectations, and market access. The research profiles a set of core companies whose operational footprint and strategic focus provide a clear window into how the market is being contested. These include established producers such as Nanjing Hongbaoli Group Co., Ltd. and Shandong Inniolamine New Material, which anchor significant production capacity around high-purity DEIPA grades for cement grinding aids and concrete admixtures. Their positioning reflects a broader trend in Asian manufacturing ecosystems, where scale, export orientation, and specification refinement are converging to support both domestic infrastructure demand and international supply channels.
India's chemical manufacturing base also features prominently, with organizations like Viswaat Chemicals Limited and Amines & Plasticizers Limited operating as influential contributors to the DEIPA supply chain. Their focus on construction chemicals and cement applications aligns with the region's ongoing infrastructure expansion and the increasing adoption of chemical admixtures to improve performance efficiency. Meanwhile, distribution and trading specialists such as Bisley International LLC play a critical intermediary role, ensuring that industrial and construction end-users can access DEIPA with reduced friction across geographies and specification requirements. This diversified competitive architecture means that market access is rarely about securing a single supplier relationship. It is about understanding how manufacturers, formulators, and distributors interact to create reliability, technical support, and pricing stability.
The report also examines market concentration as a structural indicator of competitive intensity. With a CR3 near 24.6 percent and CR5 at approximately 26.2 percent, the market displays a moderately fragmented profile. This concentration pattern suggests that while leading players hold meaningful influence, there remains substantial room for regional specialists, product-focused innovators, and service-oriented distributors to capture share through differentiation rather than scale alone. For companies evaluating partnerships, acquisitions, or greenfield capacity, this landscape offers multiple entry and expansion pathways, each with distinct risk-reward profiles depending on target segment, geographic exposure, and technical capability requirements.
Translating Market Intelligence into 2026 Execution
What separates useful market research from strategically actionable intelligence is relevance to decision cycles. Our DEIPA study is built around that principle. Rather than stopping at descriptive analysis, the report integrates practical frameworks that help organizations align market signals with internal planning processes. This includes scenario-based forecasting approaches that account for feedstock volatility, regulatory escalation, and demand concentration shifts. It also encompasses supplier evaluation criteria, regional cost-structure comparisons, and application-level demand sensitivity mapping that supports more precise commercial targeting.
For product and R&D teams, the research provides a structured view of specification trends and performance expectations across end-use environments. This enables formulation teams to anticipate where purity thresholds, compatibility requirements, or additive performance benchmarks are moving, reducing the lag between market demand and product readiness. For manufacturing and operations leaders, the study highlights where process efficiency, compliance readiness, and feedstock procurement strategy intersect, offering a basis for capital prioritization and capacity optimization. For commercial and go-to-market teams, the segmentation and competitive analyses clarify where pricing stability is most achievable, where technical service differentiation can protect share, and where geographic expansion may yield disproportionate returns.
The report's design reflects a commitment to operational utility. It organizes complex market dynamics into decision-ready components, allowing executive teams to extract relevant insights without navigating irrelevant detail. Whether the objective is to reassess sourcing strategy, evaluate expansion into adjacent application areas, benchmark competitive positioning, or stress-test margin assumptions under regulatory and raw material pressure, the study provides a coherent foundation for those conversations. In a market where misreading a single variable can compound into inventory imbalance, pricing misalignment, or missed entry windows, that coherence has direct financial and strategic value.
The Strategic Edge in an Accelerating Market
DEIPA is no longer a peripheral chemical story. It is a market where demand growth, regulatory pressure, raw material dynamics, and competitive differentiation intersect in ways that reward informed, anticipatory decision-making. The projected growth trajectory through 2032 signals that the window for strategic positioning is open, but it will not remain frictionless. Companies that treat DEIPA as a static procurement line item risk falling behind organizations that approach it as a strategic capability area, integrating market intelligence into sourcing, product development, compliance planning, and commercial execution.
Our full market study goes deeper into every dimension that matters for 2026 planning and beyond. It unpacks regional demand architectures, application-level growth drivers, competitive movement patterns, and regulatory impact pathways with the level of detail required for credible strategic action. The executive summary provided here is intended to demonstrate analytical depth and establish confidence in the methodology, while preserving the precise segmentation data, detailed company assessments, and scenario modeling frameworks for the complete report. For decision-makers who need more than directional insight, accessing the full study is the logical next step. The market is moving, and the organizations that move with it most effectively will be those that invest in intelligence before they invest in execution.
For detailed analysis of this topic, please visit the official page: Diethanol Isopropanolamine (DEIPA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


