



Paper Pallet Market to Reach $745 Million by 2032 with 5.48% CAGR

Navigating the Paper Pallet Market: Strategic Intelligence for 2026 Decision-Makers
As global supply chains recalibrate around sustainability mandates and regulatory pressures, the packaging sector stands at a pivotal inflection point. The paper pallet market, once a niche alternative to traditional wooden and plastic logistics solutions, has matured into a strategic imperative for enterprises managing high-volume freight across international borders. PW Consulting's latest comprehensive study on the Paper Pallet Market delivers actionable intelligence designed to inform capital allocation, supplier partnerships, and regional expansion strategies throughout the 2026–2032 horizon.
This introduction outlines the strategic architecture of our research, demonstrates how macroeconomic indicators translate into operational foresight, and illustrates why forward-looking organizations are treating paper-based palletization as a core component of their supply chain resilience playbook.
The Macro Trajectory: Growth Signals and Structural Shifts
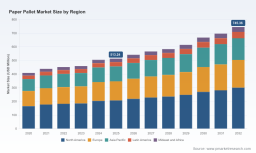
Between 2020 and 2025, the global paper pallet market demonstrated consistent revenue expansion, reflecting a steady migration away from conventional wood-based packaging. Initial valuation benchmarks in the early 2020s established a foundation that subsequent years reinforced through accelerated adoption across logistics-intensive sectors. The market's progression through 2024 and 2025 reflects an ecosystem that has moved beyond early-adopter experimentation into mainstream procurement considerations.
Our forecast model projects continued revenue growth across the 2026–2032 period, with compound annual growth rates indicating a durable expansion path. This trajectory is not merely a reflection of volume displacement; it captures fundamental shifts in how multinational corporations evaluate total cost of ownership, customs compliance, and environmental reporting. Decision-makers who understand the drivers behind this upward curve position themselves to capture margin advantages before commoditization erodes early-mover benefits.
The scale of the opportunity underscores why organizations cannot rely on fragmented industry anecdotes. A structured, data-anchored view of revenue pathways, demand elasticity, and competitive intensity allows procurement leaders and supply chain executives to evaluate whether paper pallet integration belongs in their near-term roadmap or longer-term sustainability pipeline.
Regulatory Tailwinds and the ISPM-15 Advantage
One of the most consequential dynamics shaping the market involves international phytosanitary regulations. Wooden packaging materials entering cross-border trade corridors must comply with ISPM-15 treatment requirements, which mandate heat treatment or fumigation protocols to mitigate pest transmission risks. Paper pallets, by contrast, fall outside these treatment mandates, eliminating a layer of compliance complexity that has historically slowed freight movement and increased administrative overhead.
This regulatory distinction creates measurable operational advantages for shippers managing high-frequency transatlantic, transpacific, and intra-Asia logistics flows. Paper alternatives reduce dwell time at inspection points, lower the risk of shipment rejection, and simplify documentation workflows. As customs enforcement protocols become more stringent in 2026 and beyond, organizations that standardize paper pallet utilization across export lanes can expect smoother clearance cycles and reduced contingency costs.
Wood Pallet Market
The regulatory environment also intersects with corporate sustainability commitments. Enterprises tracking Scope 3 emissions and packaging circularity targets find that paper-based solutions offer clearer end-of-life pathways when paired with recycling infrastructure, reinforcing the business case beyond mere compliance convenience.
Competitive Architecture: Who Shapes the Market and How
Market leadership in the paper pallet sector is defined not by raw production capacity alone but by proprietary engineering, material science capabilities, and the ability to integrate pallet solutions into broader transit and storage ecosystems. Several organizations have emerged as influential players, each pursuing distinct value propositions that appeal to specific supply chain profiles.
Smurfit Kappa Group, headquartered in Dublin, has built a recognizable presence through engineered paper pallet offerings such as PaPillOn strong paper pallet and TOPPSafe™ pallet top systems. Their approach emphasizes load-bearing performance combined with compatibility into existing corrugated supply networks. DS Smith Plc, based in London, advances a complementary yet differentiated position with its patented fibre-based pallet technology, targeting organizations that prioritize structural consistency and manufacturability at scale.
International Paper Company brings extensive raw material and converting infrastructure to the market, offering corrugated and molded paper pallet formats that leverage decades of industrial packaging expertise. Sonoco Products Company, operating from Hartsville, South Carolina, focuses on integrated paper pallet systems designed for specialized transit requirements and operational durability. PALLITE Limited, headquartered in the United Kingdom, has carved a distinct niche through honeycomb paper pallet designs and PIX® storage solutions that appeal to organizations seeking lightweight yet structurally reliable storage and transport alternatives.
Signode, based in Illinois, has positioned itself around paper pallet options designed for transit environments with ISPM-15 compliance considerations, aligning its portfolio with cross-border shippers seeking regulatory simplicity. ATTA Pallet, located in Hungary, emphasizes production and assembly capabilities tailored to paper pallet manufacturing workflows, while EcoDuro Inc., operating in Canada, contributes molded pulp and paper-based pallet options that broaden the material palette available to sustainability-focused procurement teams.
The competitive field reflects a mosaic of engineering priorities, regional strengths, and integration strategies. Understanding which players are expanding capacity, which are locking in proprietary formulations, and which are building partnerships with logistics integrators is essential for organizations evaluating supplier resilience and pricing stability over multi-year contracting cycles.
Recent Developments Reshaping Product Expectations
The pace of product-level innovation has accelerated markedly in recent months, signaling that incumbents are actively responding to shifting procurement criteria. In September 2025, Smurfit Westrock introduced a recyclable paper pallet wrap engineered as a direct replacement for single-use plastic pallet wraps in shipment applications. This launch reflects a growing emphasis on eliminating plastic wrapping without compromising load containment, a concern that has become increasingly prominent among shippers tracking packaging waste reduction targets.
Earlier, in March 2024, Seaman Paper expanded the functional scope of paper-based transit solutions with the launch of SeaStretch™, a patented lightweight paper alternative designed for shipping and storage loads. This development reinforced the viability of paper as a performance-competitive material in contexts where plastic film had previously dominated, particularly when weight reduction and recyclability are weighted heavily in procurement evaluation frameworks.
These launches matter because they illustrate a market trend moving beyond pallet boards alone. The broader product ecosystem now includes wrapping solutions, load stabilization approaches, and storage geometries that collectively influence total logistics cost. Buyers evaluating paper pallet adoption must consider how compatible wrapping, cushioning, and handling practices affect throughput, damage rates, and downstream recycling feasibility.
What the Report Delivers: Operational Intelligence Beyond Headline Figures
PW Consulting's Paper Pallet Market research is structured to support decision-making at multiple organizational levels. Rather than presenting a static snapshot, the study maps revenue evolution, segment dynamics, and competitive interventions across historical and forecast periods, enabling readers to test assumptions against evidence-based scenarios.
The report examines the structural composition of market demand, identifying how different product types and application categories contribute to overall revenue behavior. It explores regional demand patterns without reducing complexity to oversimplified ratios, offering instead a nuanced view of where adoption momentum is strongest and what local regulatory or logistics conditions amplify or constrain growth.
Detailed company profiles analyze strategic positioning, product differentiation, and recent developmental activity across key participants. This competitive mapping is paired with an assessment of concentration dynamics, helping stakeholders gauge pricing influence, supplier dependency risk, and the likelihood of consolidation pressure in the years ahead.
Operational considerations are addressed through analysis of material developments, product launches, and regulatory alignments that affect procurement planning. Readers gain insight into how transit compliance frameworks, sustainability reporting expectations, and packaging innovation cycles intersect with supplier selection and contract structuring. The research also contextualizes supply chain decision points such as total cost comparisons, damage-risk trade-offs, customs efficiency, and recyclability infrastructure readiness.
Because the study spans a defined historical baseline and extends across a multi-year forecast window, it supports scenario-based evaluation. Organizations can assess how shifts in freight volume, regulatory enforcement intensity, or material cost dynamics may alter adoption timing and budget allocation. This forward-looking structure is particularly valuable for teams planning capital-intensive logistics improvements or evaluating multi-year supplier partnerships.
Why 2026 Is a Defining Year for Strategic Action
The convergence of regulatory clarity, product innovation, and expanding adoption creates a window in which strategic choices carry disproportionate long-term effects. Organizations that delay evaluation risk entering supplier negotiations after pricing structures adjust to heightened demand visibility, while those that assess options prematurely may overlook rapid product improvements that reshape performance comparisons.
In 2026, procurement and supply chain leaders must determine whether paper pallet integration belongs within tactical cost-reduction programs or within broader transformation initiatives tied to compliance, sustainability reporting, and international freight efficiency. Answering that question requires a granular understanding of market direction, competitive behavior, and application-specific demand behavior, all of which our research is designed to clarify.
Firms operating across multiple regions face additional complexity. Regional demand intensity varies, and local regulatory expectations, recycling infrastructure availability, and logistics partner capabilities influence whether paper pallet adoption generates the anticipated benefits. A market-level view must therefore be paired with operational realism about implementation readiness, supplier reliability, and internal change management requirements.
The report enables this level of discernment by connecting macro growth signals with actionable procurement implications. Readers can evaluate whether current supplier options align with their technical specifications, whether product innovation timelines match their implementation horizons, and whether market concentration trends suggest a need for diversification or long-term contracting.
From Insight to Execution
Deep market intelligence becomes valuable only when it informs concrete decisions. PW Consulting's Paper Pallet Market study is built to support that translation. It equips strategy teams with evidence-based context, helps procurement groups benchmark supplier claims against market-wide patterns, and gives executive stakeholders the framing needed to prioritize packaging logistics investments alongside other transformation initiatives.
For organizations preparing for the 2026 decision cycle, the critical task is not simply recognizing that the market is expanding. The strategic value lies in understanding which forces are structural rather than cyclical, which supplier capabilities are likely to endure, and where adoption timing will most strongly affect cost and operational outcomes. Our research is designed to illuminate those distinctions without leaving decision-makers to infer them from partial data.
Paper Pallet Market
The complete analysis provides the depth, segmentation clarity, competitive mapping, and scenario-aware forecasting required to move from awareness to action. For teams tasked with evaluating paper pallet integration as part of broader supply chain strategy, the full report offers the intelligence foundation necessary to make informed, timely, and defensible decisions.
For detailed analysis of this topic, please visit the official page: Paper Pallet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


