



PW Consulting: Medical Ultrasound Probe Market Hits $215M in 2025, Projected 3.3% CAGR Through 2032

Navigating the Pulse: Strategic Intelligence for the 2026 Medical Ultrasound Probe Market
The medical ultrasound probe market stands at a critical inflection point as healthcare delivery models shift toward point-of-care diagnostics and advanced imaging integration. For executives and strategy teams planning capital allocation and product roadmaps through 2032, understanding the nuanced trajectory of this sector is not merely analytical—it is imperative. This article introduces PW Consulting's latest comprehensive market research, designed to equip decision-makers with the foresight required to navigate regulatory shifts, competitive realignments, and evolving clinical demands. The following insights distill the executive summary of our full report, highlighting the strategic value embedded within our analysis while preserving the granular data necessary for precise execution available exclusively in the complete document.
Macroeconomic Trajectory and Market Size Evolution
Our analysis covers a robust historical period from 2020 through 2025, extending a forecast horizon to 2032. This longitudinal view allows for the identification of structural trends rather than transient fluctuations. The market has demonstrated consistent growth over the past half-decade, with revenue figures reflecting a steady expansion in diagnostic imaging adoption globally. In 2020, the market valuation stood at approximately 163.15 Million USD. Year-over-year progression saw increases to 167.51 Million USD in 2021, 175.83 Million USD in 2022, and a notable acceleration to 183.64 Million USD in 2023. The recent past indicates a significant jump to 205.21 Million USD in 2024, culminating in an estimated base year valuation of 215.0 Million USD for 2025.
Looking forward, the forecast period projects the market to reach 222.9 Million USD in 2026. The trajectory suggests continued growth, with valuations anticipated to climb toward 236.95 Million USD by 2027. However, strategic planners must note specific variance points within the forecast window. While growth is the overarching theme, the data indicates a slight contraction to 235.1 Million USD in 2028 before resuming an upward trend toward 252.9 Million USD in 2029. Subsequent years show fluctuation, with dips to 247.5 Million USD in 2030, followed by recovery to 266.77 Million USD in 2031 and a projected stabilization near 268.83 Million USD by 2032. The Compound Annual Growth Rate (CAGR) calculated over this forecast period is 3.3 percent. This moderate yet steady growth rate underscores a mature market environment where competitive advantage is derived from segmentation precision and operational efficiency rather than pure volumetric expansion.
Structural Segmentation Overview
To truly leverage market opportunities, one must understand the underlying architecture of demand and supply. Our research dissects the market across three primary dimensions: Region, Type, and Application. Each dimension reveals distinct behavioral patterns and strategic entry points for stakeholders.
Geographically, the market exhibits significant dispersion. While North American markets have historically commanded strong positions, our data highlights the substantial weight of the Asia Pacific region, followed closely by North America and Europe. Latin America and the Middle East and Africa represent emerging vectors with unique adoption curves. The concentration of revenue across these regions suggests that supply chain resilience and localized regulatory compliance are becoming key differentiators.
In terms of product Type, the landscape is diversified. Convex probes remain a dominant segment, reflecting their broad utility in abdominal and obstetric imaging. Linear probes constitute a significant portion of the revenue mix, driven by vascular and musculoskeletal applications. Specialized categories such as Phased Array and Endocavitary probes serve niche but critical clinical needs, while Other types capture emerging technologies. The distribution across these types indicates that innovation is not solely focused on volume drivers but also on high-value specialized transducers.
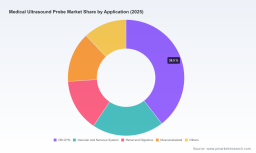
Regarding Clinical Application, the demand is heavily influenced by standard diagnostic protocols. OB-GYN applications represent a substantial share, consistent with the global emphasis on maternal health and routine screening. Vascular and Nervous System applications follow as a major demand driver, supported by the rising prevalence of cardiovascular conditions. Renal, Digestive, and Musculoskeletal applications round out the core demand pillars, with Other applications encompassing emerging use cases in emergency medicine and primary care. Understanding the revenue contribution of each application helps manufacturers prioritize R&D and marketing resources effectively.
Competitive Landscape and Strategic Positioning
The market is characterized by a fragmented yet competitive environment. The top three companies hold a combined market concentration of 24.6 percent, while the top five extend this to 26.2 percent. This relatively low concentration ratio implies that no single entity dominates the entire value chain, leaving ample room for specialized players and regional champions to compete on technology, service, and cost.
Our report provides detailed profiles and strategic assessments of key industry participants. Global giants such as GE HealthCare, headquartered in Chicago, Illinois, continue to lead with proprietary diagnostic systems and transducer compatibility, notably within their Voluson Expert series. Koninklijke Philips N.V., based in Amsterdam, maintains a strong presence through its EPIQ and Affiniti series, offering broad diagnostic compatibility. Siemens Healthineers AG, operating from Erlangen, Germany, manufactures MyLab systems and associated probes that serve diverse clinical imaging needs.
Recent Regulatory Milestones and Industry Noise
The regulatory environment remains a pivotal factor in product deployment and market access. Recent months have seen significant activity regarding FDA 510(k) clearances, which directly impact the availability and cycle times for new probe technologies. In January 2025, GE HealthCare announced FDA clearance for enhanced Voluson Expert Series ultrasound systems, including lightweight probes, signaling a push toward ergonomics and portability. Further clearances followed in July 2025 for the Venue Go, Venue Fit, Venue Sprint, and Venue systems, and again in November 2025 for the Voluson Expert 18, 20, and 22 systems under specific K-numbers. Philips also secured FDA clearance in June 2025 for its EPIQ and Affiniti Series diagnostic systems.
Beyond approvals, the industry must also navigate recall dynamics. Recent database entries indicate Class III recalls for multiple Philips ultrasound transducers in early 2026. Such events highlight the importance of quality assurance and risk management in strategic planning. Additionally, service ecosystems are evolving; for instance, in January 2026, Probo Medical secured the inclusion of ultrasound probe repair services on the Federal Supply Schedule via Maclean Group LLC, indicating a growing demand for lifecycle management and repair solutions alongside new equipment sales.
Unlocking Decision-Ready Intelligence
While this overview establishes the strategic context, the full PW Consulting report delivers the depth required for actionable execution. The complete study moves beyond high-level trends to provide specific revenue splits, growth rates by segment, and detailed competitor benchmarking that are essential for tactical planning. By accessing the full intelligence, stakeholders can dissect exactly how regional shifts will impact their supply chains, which probe types offer the highest margin potential in specific clinical settings, and how the competitive moves of entities like FUJIFILM Sonosite, Canon Medical, Samsung Medison, Hitachi Healthcare, Esaote, Mindray, SIUI, and emerging players like Shenzhen Ruqi Technology will reshape the battlefield.
Worldwide Ultrasonic Probe Covers Market
The report integrates real-world data to map out the competitive intensity, identifying where consolidation might occur and where niche players can secure defensible positions. It also analyzes the implications of regulatory clearances on market entry barriers and the strategic value of service contracts in an era of increasing hardware complexity. With the market projected to nearly double from its 2020 levels by the end of the forecast period, the cost of inaction or misinformed strategy is significant.
Medical Ultrasound Probe Market
Call to Action for Strategic Leaders
As we move through 2026, the ability to anticipate market fluctuations—such as the variance projected between 2027 and 2030—will separate market leaders from followers. The data suggests that while the overall CAGR is 3.3 percent, specific segments and regions may outperform or underperform this average based on regulatory adoption and clinical guideline updates. PW Consulting's detailed analysis provides the granular visibility needed to capitalize on these discrepancies.
We invite industry executives, investors, and product strategists to explore the full findings of our Medical Ultrasound Probe Market report. The comprehensive document includes detailed segmentation tables, competitor SWOT analyses, and forward-looking scenarios that go beyond the summary provided here. To gain the competitive edge required for 2026 and beyond, access the complete intelligence package available on the PW Consulting website. Let us guide your strategy with data precision and industry expertise.
For detailed analysis of this topic, please visit the official page: Medical Ultrasound Probe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


