



PW Consulting: Legal Practice Management Software Market Hits $2.68B in 2025, 11.5% CAGR to 2032

Strategic Intelligence for Legal Decision-Makers: Navigating the Practice Management Software Market in 2026
The legal technology landscape has reached an inflection point. What was once a fragmented market of niche tools has matured into a consolidated ecosystem where operational efficiency, AI integration, and regulatory compliance converge. For enterprise buyers, law firm managing partners, and institutional investors, understanding the trajectory of legal practice management software is no longer optional. It is a core component of operational strategy.
PW Consulting is pleased to introduce our latest market intelligence study, a comprehensive analysis designed to equip leadership teams with the actionable insights required to navigate the 2026 landscape and beyond. This report does not merely recount historical trends. It constructs a forward-looking framework that aligns technology procurement, competitive positioning, and capital allocation with the structural shifts reshaping legal service delivery.
Market Trajectory and the Case for Strategic Foresight
The legal practice management software sector has demonstrated consistent, above-average growth across the historical analysis window. Revenue expansion has outpaced many adjacent enterprise software categories, driven by a compounding set of operational pressures: rising labor costs, stringent client expectations around transparency, and the accelerating digitization of court and compliance workflows. The market has moved decisively from early-adopter experimentation to mainstream operational dependency.
This maturation is not accidental. It reflects a structural recalibration within legal operations. Firms of all sizes are confronting margin compression and talent scarcity, forcing a shift from manual, paper-heavy processes toward integrated platforms that centralize matter management, financial operations, and client engagement. Cloud-based architectures have become the default deployment model, supported by an increasingly robust security and compliance infrastructure that addresses the sector's unique trust accounting and data privacy requirements.
The forecast horizon captured in our analysis points to continued robust expansion through the end of the decade. However, aggregate growth rates only tell part of the story. The true strategic value of this research lies in its ability to segment that growth into actionable intelligence: where adoption is concentrating, which deployment models are winning, how revenue is shifting across user categories, and what competitive dynamics will determine market leadership over the next several years. These are the questions that separate reactive procurement from proactive strategy.
Inside the Analysis: What the Report Delivers
Our research methodology combines quantitative modeling with on-the-ground industry validation. The resulting publication is structured to serve multiple executive functions simultaneously: situational awareness, vendor evaluation, investment scenario planning, and operational roadmap development.
Readers will find detailed examinations across the dimensions that matter most to decision-makers:
- Market sizing and trajectory modeling spanning historical performance and a forward-looking forecast window, enabling scenario-based planning rather than single-point estimates.
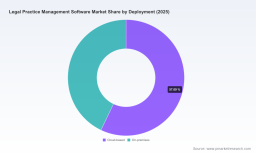
- Deployment architecture analysis comparing cloud-native and on-premises environments, with emphasis on security postures, integration pathways, and total cost of ownership implications.
- Application-level segmentation distinguishing demand patterns across law firms and attorneys, court systems, and other institutional users, revealing where procurement momentum is strongest.
- Regional landscape mapping that contextualizes adoption maturity, regulatory environments, and purchasing dynamics across key geographic markets.
- Competitive benchmarking of leading platform providers, evaluating product roadmaps, AI integration depth, pricing architectures, and ecosystem partnerships.
- Operational dynamics assessment covering labor cost pressures, compliance frameworks, reimbursement cycle acceleration, and the evolving ethical boundaries around AI-driven case analysis and document review.
Each section is designed to produce a clear decision artifact. Rather than leaving readers with abstract market commentary, the report translates data into procurement criteria, vendor shortlisting guidance, and implementation sequencing recommendations.
The AI Inflection and Competitive Reconfiguration
No variable has reshaped this market more rapidly than artificial intelligence. Over the past year, AI usage among legal professionals has expanded meaningfully, with practice management platforms absorbing automation capabilities that were previously isolated in point solutions. Document generation, time capture, matter triage, and financial reconciliation are increasingly handled through embedded intelligence rather than manual workflow. This shift is altering vendor value propositions across the board.
The competitive landscape reflects this transformation. Market concentration remains moderate, with leading firms commanding a combined share that underscores both established presence and ongoing consolidation potential. The roster of influential players spans full-suite cloud platforms, specialized matter management systems, and AI-forward tools targeting specific practice verticals.
Analysis of the current vendor ecosystem reveals several distinct strategic postures. Cloud-native leaders such as Clio and MyCase continue to expand their functional breadth, embedding client intake, billing, trust accounting, and compliance tooling within unified workflows. Clio's strategic moves illustrate the scale-up dynamic: the acquisition of vLex in mid-2025 represents the largest legal tech M&A transaction in recent memory, merging AI-powered global legal research directly into practice management infrastructure. Shortly thereafter, the launch of a large-firm platform signaled a deliberate push into more complex case and process management environments.
Medical Practice Management Software Market
Other providers are executing differentiated plays. Rocket Matter and Filevine have emphasized reimagined platforms with stronger analytics and AI-powered case handling, while Smokeball and PracticePanther have doubled down on automated time capture, document automation, and trust accounting for firms seeking operational simplification. Centerbase's partnership to embed accounts payable automation directly into its midsize firm platform highlights a parallel trend: integration with back-office financial ecosystems as a competitive differentiator. Supio's specialization in personal injury and mass tort workflows demonstrates how vertical-specific AI can command premium positioning. Lexzur and Caseflow extend the field with AI-assisted matter management and client communication features, while LeanLaw's focus on QuickBooks-integrated revenue operations points to a growing appetite for financial tooling built around familiar accounting backbones.
These vendor movements matter because they redefine buyer expectations. A practice management decision in 2026 is simultaneously a decision about AI strategy, data residency, financial reconciliation speed, and vendor longevity. The report's competitive analysis maps these trade-offs explicitly, helping organizations match platform capabilities against their operating model rather than adopting a one-size-fits-all framing.
Industry Dynamics Driving Procurement and Adoption
Market growth is not simply a function of technology availability. It is being propelled by a set of interlocking operational and regulatory forces that raise the cost of inaction. Our research distills these dynamics into practical considerations for both buyers and vendors.
Cloud adoption has become the baseline expectation. Recent industry survey data indicates that a substantial majority of law firms now rely on cloud-based legal tools, with practice management and document management software posting the highest utilization rates. This shift is not cosmetic. It reflects reduced on-premises maintenance burdens, improved remote collaboration, and the ability to push updates and security patches without disrupting firm operations. For decision-makers, the question has moved from whether to adopt cloud architecture to how to select platforms that meet rigorous compliance and performance standards.
Security and regulatory compliance have accordingly become central procurement criteria. Cloud-based platforms increasingly emphasize SOC 2 alignment and data privacy standards to support trust accounting integrity and client data protection. These requirements are not uniform across jurisdictions, and the report examines how compliance posture varies by platform and what that means for multi-jurisdiction firms.
Financial workflow acceleration is another powerful driver. Automated billing, trust accounting, and integrated payment capabilities are shortening client payment cycles and reducing administrative overhead. For firms operating on tight margins, faster cash conversion is a direct operational benefit, not merely a feature checkbox. The analysis quantifies how these capabilities influence vendor selection and what performance indicators buyers should track post-implementation.
At the same time, AI integration introduces a new compliance layer. As automation expands into case analysis and document review, firms must navigate evolving professional ethics guidance on the use of AI in legal work. Regulatory bodies are actively updating expectations around supervision, accuracy, and client confidentiality. The report evaluates how leading platforms are addressing these requirements and what risk management frameworks should accompany AI adoption.
Legal Practice Management Software Market
Why This Research Matters for 2026 Decision-Making
The strategic stakes for 2026 are unusually high. Organizations that treat practice management software as a routine IT purchase risk underinvesting in capabilities that directly affect profitability, risk exposure, and client retention. Conversely, organizations that approach the market with structured intelligence can sequence implementations, negotiate from a position of clarity, and avoid vendor lock-in to platforms that lack the roadmap depth required for future growth.
This report is built for that decision environment. It provides the macro context needed to validate market timing, the segmentation detail needed to prioritize investment, and the competitive analysis needed to assess vendor durability. For law firm leadership, it supports operational transformation planning and resource allocation. For technology buyers and institutional stakeholders, it clarifies where durable demand is forming and which platform categories are likely to consolidate further.
Because the full value of this analysis depends on the underlying segmentation models, regional breakdowns, deployment comparisons, and company-level benchmarking, the complete dataset and executive findings are available through our comprehensive market study. The page-length overview presented here is intended as a strategic preview: a demonstration of the analytical rigor and decision-focus that define the full publication.
Next Steps for Strategic Alignment
Market leadership in legal technology is being redefined in real time. Firms that align their practice management strategy with the realities of AI adoption, compliance evolution, and financial workflow acceleration will be best positioned to convert operational software into durable competitive advantage. Those that delay structured evaluation risk entering a more consolidated market with fewer negotiating advantages and higher switching costs.
The complete market research extends well beyond this overview. It delivers the segmented data, vendor assessments, and forward-looking projections required to support confident 2026 decision-making across procurement, investment, and operational transformation initiatives. Readers seeking the full intelligence package, including detailed segmentation splits and competitive benchmarking, are encouraged to access the complete report at the source page, where the full dataset and executive insights are available for direct review.
For detailed analysis of this topic, please visit the official page: Legal Practice Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


