



PW Consulting: Distillation Packings Market to Reach $1,456.41M by 2032 at 6.0% CAGR

Navigating the Distillation Packings Market: Strategic Intelligence for 2026 Decision-Making
Executive Overview: A Market at an Inflection Point
The global distillation packings market stands at a critical juncture as industrial separation processes demand higher efficiency, lower energy consumption, and stricter compliance with environmental standards. Our latest market research report provides a comprehensive examination of this evolving landscape, offering corporate strategists, procurement leaders, and engineering executives the data-driven foundation needed to make confident decisions in 2026 and beyond.
Building on a historical analysis spanning 2020 through 2025, our forecast model projects sustained growth through 2032, anchored by a compound annual growth rate of 6.0 percent. The market, valued at approximately 965.22 million USD in the 2025 base year, is expected to reach 1,019.74 million USD in 2026 and continue its upward trajectory toward 1,456.41 million USD by 2032. These figures reflect more than incremental expansion; they signal a structural shift in how industries approach mass transfer equipment, driven by technological advancement, regulatory pressure, and regional capacity realignment.
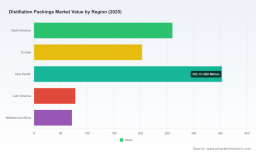
This article serves as a strategic preview of our full Distillation Packings Market report. It highlights the analytical framework, competitive intelligence, and operational dynamics that decision-makers must understand to position their organizations advantageously. Core segmentation data, regional revenue breakdowns, and application-specific valuations are reserved for the complete publication, where they are presented with the granularity required for actionable planning.
Distillation Packings Market
Market Trajectory: From Recovery to Sustained Expansion
The five-year historical window from 2020 to 2025 reveals a market that has consistently outpaced initial projections. Revenue climbed from 750.15 million USD in 2020 to 965.22 million USD by 2025, reflecting a recovery trajectory that accelerated as petrochemical and chemical processing facilities resumed capital expenditure programs following earlier disruptions. The steady year-over-year progression underscores durable demand for distillation internals across multiple processing sectors.
Our forecast period, covering 2026 through 2032, models a continuation of this momentum. The market is projected to surpass the 1 billion USD threshold in 2026 and reach 1,090.35 million USD by 2027. Subsequent years show compounding growth, with valuations of 1,165.98 million USD in 2028, 1,249.42 million USD in 2029, and 1,305.96 million USD in 2030. The latter half of the forecast window reflects moderating but still robust expansion, culminating in a 1,456.41 million USD market size by 2032. This trajectory is supported by ongoing capacity additions in emerging industrial corridors, retrofits of aging distillation columns, and the gradual substitution of conventional trays with advanced packing solutions that deliver superior theoretical stage efficiency.
It is important to note that these aggregate figures provide the macro foundation for our analysis. The complete report dissects the underlying drivers segment by segment, enabling clients to identify which product categories, material specifications, and end-use verticals are contributing most significantly to growth. This layered approach ensures that strategic planners can align procurement timelines, capacity investments, and partnership decisions with the segments that match their operational priorities.
Structural Dynamics: Technology, Regulation, and Operational Realities
Several interconnected forces are reshaping the distillation packings landscape and will continue to influence purchasing behavior throughout the forecast period. First, the technical differentiation between structured and random packing architectures remains a central consideration for process engineers. Structured packings, with their engineered surface area and controlled flow distribution, are increasingly favored in applications where pressure drop minimization and high separation efficiency are paramount. Random packings continue to occupy a significant share of the market, particularly in scenarios where cost-effectiveness, ease of installation, and tolerance for uneven liquid distribution are prioritized. Grid packings and other specialized variants address niche requirements, including high-capacity vacuum operations and temperature-sensitive distillations.
Material selection is another critical determinant of market behavior. Metal packings, typically fabricated from stainless steel or specialty alloys, dominate segments requiring corrosion resistance, mechanical strength, and long operational life. Plastic packings serve applications where chemical compatibility, weight reduction, and lower initial cost are decisive factors. Ceramic packings, while representing a smaller portion of overall demand, remain essential in highly corrosive environments and specific chemical processing contexts. The interplay between material performance, fabrication complexity, and total cost of ownership creates a nuanced decision matrix that our report analyzes in detail.
Regulatory and operational dynamics are equally influential. Environmental regulations targeting volatile organic compound emissions in chemical plants are accelerating the preference for low-emission structured packings in distillation applications. These regulations are not merely compliance checkboxes; they are reshaping engineering specifications and prompting facility operators to reevaluate existing column internals. At the same time, the skilled labor cost differential for precision installation and maintenance of structured packings, which averages 15 percent higher than for random packings, introduces a practical consideration that procurement and operations teams must weigh against long-term efficiency gains.
Supply chain and fabrication considerations further complicate the landscape. Custom corrosion-resistant packings designed for aggressive chemical processes require specialized surface treatments that increase fabrication time by approximately 20 percent compared to standard metal media. Meanwhile, raw material pricing dynamics, such as the current unit price of stainless steel wire gauze for structured packings at approximately 45 USD per cubic foot, directly affect margin structures and pricing strategies. These factors are integrated into our market dynamics analysis to provide a realistic picture of cost pressures, lead time implications, and negotiation leverage.
Competitive Landscape: Key Players and Strategic Positioning
The distillation packings market exhibits moderate concentration, with the top three companies holding a combined market share of 55.5 percent and the top five accounting for 62.3 percent. This concentration reflects the technical barriers to entry, the importance of established engineering relationships, and the value of proprietary packing designs that have been validated across decades of industrial operation. Our report provides a thorough competitive assessment of the organizations shaping this landscape.
Sulzer AG, headquartered in Winterthur, Switzerland, is recognized as a core provider of Mellapak series structured packings and BXPlus gauze packings for distillation columns. The company emphasizes low pressure drop and high efficiency in chemical and petrochemical separations, and its January 2025 introduction of the MellapakEvo structured packing demonstrates a continued commitment to performance enhancement. Koch-Glitsch, based in Wichita, Kansas, USA, offers FLEXIPAC HC structured packings and INTALOX ULTRA random packings, along with the Montz Pak line, optimized for crude vacuum distillation and high-capacity applications. Their portfolio reflects a strong focus on processing conditions that demand robust mechanical design and flexible capacity scaling.
Raschig AG, located in Ludwigshafen, Germany, develops and supplies Raschig Super Ring random packings and metal structured packings for distillation, with a clear emphasis on high-performance mass transfer media. Julius Montz GmbH, also based in Germany, specializes in Montz-Pak wire gauze structured packings tailored for vacuum and temperature-sensitive distillations, delivering low pressure drop per theoretical stage. These European incumbents maintain strong positions through engineering heritage, consistent product innovation, and deep integration with global process design firms.
The competitive field also includes several manufacturers with significant regional presence and growing international reach. Finepac India, headquartered in Pune, manufactures FP series and wiremesh structured packings for distillation columns, prioritizing corrosion resistance and broad application range. Goel Impex, based in New Delhi, supplies high-performance structured packings for distillation, absorption, and stripping, with an emphasis on customized chemical resistance solutions. Ambani Metals, located in Ahmedabad, produces advanced structured packings for efficient separation in distillation and related processes, supported by global export capabilities. These organizations illustrate the expanding influence of manufacturers outside the traditional European and North American core, particularly as cost-competitive engineering and material expertise become increasingly valued.
Chinese suppliers such as Pingxiang Xingfeng Chemical Packing Co., Ltd. and Jiangxi Kelley Chemical Packing Co., Ltd., both based in Pingxiang, Jiangxi, contribute meaningfully to the market. Pingxiang Xingfeng supplies metal random packings including Pall rings for distillation columns, serving petrochemical and chemical industries, while Jiangxi Kelley provides tower packing and structured packings with a focus on high-efficiency random and metal media. In the United States, Mach Engineering, headquartered in Houston, Texas, manufactures X and Y corrugated structured packings for distillation columns, offering both custom and off-the-shelf options. The presence of these diverse players underscores the importance of evaluating suppliers not only by brand recognition but by alignment with specific process requirements, lead time expectations, and regional service capabilities.
Report Contents: Operational Intelligence for Strategic Planning
Our Distillation Packings Market report is structured to deliver practical value at every stage of the decision-making process. Rather than presenting abstract market narratives, the publication focuses on actionable intelligence that can be integrated into capital planning, supplier evaluation, product development, and competitive positioning. The report includes the following core components:
Mass Transfer (Distillation) Market
- Historical and Forecast Revenue Analysis: A detailed examination of market size evolution from 2020 through 2025, followed by a year-by-year forecast extending to 2032. This section provides the quantitative backbone for scenario planning and investment timing.
- Segmentation Framework: A systematic breakdown of the market by type, material, application, and region. Each segmentation dimension is analyzed to reveal growth patterns, share dynamics, and the strategic implications of shifting demand.
- Competitive Profiling: In-depth company assessments covering product portfolios, technological focus, geographic reach, and recent developments. Profiles are designed to support supplier selection, partnership evaluation, and competitive benchmarking.
- Market Dynamics and Cost Drivers: An integrated discussion of raw material pricing, labor cost differentials, fabrication complexity, regulatory influences, and infrastructure considerations that affect total cost of ownership and procurement strategy.
- Strategic Recommendations: Actionable guidance for navigating capacity investments, technology adoption, supplier diversification, and regional market entry, tailored to the needs of engineering firms, processing companies, and equipment manufacturers.
By combining quantitative rigor with qualitative industry context, the report enables clients to move beyond high-level trends and into the specifics that determine project success. Whether the objective is to optimize a distillation column retrofit, evaluate a new supplier relationship, or anticipate demand shifts in a target region, the analysis is organized to support evidence-based decisions.
Strategic Value for 2026 Decision-Making
The 2026 planning cycle presents a unique set of considerations for organizations operating in or adjacent to the distillation packings market. On one hand, the projected growth trajectory suggests expanding opportunity across multiple segments and geographies. On the other hand, the concentration of market share among a limited number of established players, combined with evolving regulatory requirements and cost pressures, demands a disciplined approach to strategy. Our report is designed to help decision-makers navigate this environment with clarity.
For procurement and engineering leaders, the report offers a structured basis for comparing packing types, materials, and supplier capabilities against specific process conditions. The segmentation analysis clarifies where performance advantages are most pronounced and where cost-driven considerations may justify alternative selections. For corporate strategists and investors, the forecast data and competitive profiling provide a foundation for assessing market entry opportunities, partnership potential, and long-term demand visibility. For product development teams, the discussion of operational dynamics, including fabrication time implications and environmental regulation trends, highlights the innovation areas most likely to influence future purchasing criteria.
Importantly, the report does not treat the market as a monolithic entity. It recognizes that the drivers of demand in petrochemical processing differ from those in chemical manufacturing, pharmaceutical applications, and oil and gas operations. Similarly, regional variations in industrial activity, regulatory frameworks, and supplier ecosystems require tailored strategic responses. By preserving the granularity of segmentation data within the full publication, we ensure that clients can extract the precise insights relevant to their operational context without relying on generalized assumptions.
Conclusion: Turning Market Intelligence into Strategic Advantage
The distillation packings market is characterized by steady growth, meaningful technological differentiation, and a competitive structure that rewards organizations capable of aligning product capabilities with process requirements. Our comprehensive report translates this complexity into a clear, data-supported framework that decision-makers can use to reduce uncertainty, prioritize investments, and strengthen their competitive position.
The macro trajectory, from a 965.22 million USD market in 2025 to a projected 1,456.41 million USD by 2032, provides the broad context. The detailed segmentation, competitor analysis, and dynamics assessment provide the precision needed to act confidently. For leaders who require a complete view of the market, including the specific regional, application, and product-level data that underpin our forecasts, the full Distillation Packings Market report is available for immediate review. We invite you to access the complete publication to obtain the full intelligence package and begin integrating these insights into your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Distillation Packings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


