



PW Consulting: Auto Aluminium Wheel Market Hits $165M in 2025, Projected CAGR 2.8% to 2032

Strategic Intelligence for the Automotive Aluminium Alloy Wheels Market: Navigating 2026 and Beyond
Executive Overview
The automotive aluminium alloy wheels market stands at a critical inflection point in 2026. As original equipment manufacturers accelerate platform electrification, pursue aggressive lightweighting targets, and navigate an increasingly fragmented tariff and raw-material landscape, the strategic importance of wheel supply chain intelligence has never been higher. This report provides a comprehensive, data-driven roadmap for executives, product planners, procurement leaders, and investors who must align their portfolios with structural shifts rather than short-term market noise. By synthesizing five years of historical performance with a seven-year forward outlook, the analysis equips decision-makers with the contextual clarity required to allocate capital, prioritize engineering roadmaps, and recalibrate regional exposure.
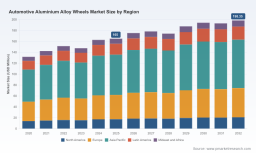
The market has demonstrated resilient recovery patterns following pandemic-era disruptions, with global revenue climbing from approximately 142.3 million USD in 2021 to a projected 175.3 million USD in 2026. Over the full forecast horizon through 2032, the sector is expected to expand at a compound annual growth rate of 2.8 percent, reflecting steady demand from passenger and commercial vehicle segments compounded by regulatory tailwinds and material substitution trends. While headline figures suggest moderate growth, the underlying dynamics reveal significant variation in profitability, capacity utilization, and competitive positioning across manufacturing processes, vehicle architectures, and geographic corridors. Understanding where margin compression concentrates and where premium differentiation can be sustained requires granular segmentation analysis that extends well beyond aggregate market sizing.
Market Trajectory and Structural Growth Drivers
Historical data from 2020 through 2025 illustrates a sector that has rebounded unevenly but decisively. After a brief contraction in 2023, revenue reaccelerated through 2024 and 2025, establishing a foundation for the 2026 to 2032 forecast window. The compound annual growth rate of 2.8 percent reflects a market transitioning from volume-led expansion toward value-driven optimization. Lightweight construction requirements, particularly within passenger vehicles and high-performance SUVs, continue to anchor baseline demand. Simultaneously, commercial vehicle fleets face mounting pressure to reduce total cost of ownership and meet fleet-level efficiency mandates, gradually shifting procurement preferences toward alloy wheels where durability and load ratings justify premium positioning.
The forecast trajectory accounts for both organic end-market growth and structural supply-side adjustments. Regional capacity additions, evolving OEM sourcing strategies, and the gradual reallocation of production toward low-pressure casting and forged architectures influence how value is distributed across the forecast period. Notably, the market does not follow a linear expansion curve; phases of capacity rationalization and technology adoption create inflection points that reward participants with flexible manufacturing footprints and disciplined raw-material hedging strategies. Executives evaluating regional exposure or plant utilization targets must therefore interpret growth projections through the lens of process maturity, contract visibility, and tariff-adjusted landed costs rather than relying on a single blended growth assumption.
Competitive Landscape and Strategic Positioning
The competitive environment is defined by a concentrated but highly differentiated supplier base. Global market structure analysis indicates a relatively modest concentration profile, with the top three participants capturing roughly 25.5 percent of total revenue and the top five reaching approximately 29.2 percent. This fragmentation reflects the coexistence of large-scale integrated producers, regional specialists, and aftermarket-focused brands that serve distinct customer segments with varying performance, aesthetic, and cost requirements.
CITIC Dicastal operates as the world's largest producer and exporter of automotive aluminium alloy wheels, supplying OEMs globally with high-volume cast and forged products. Its technological breadth spans LPDC, CPC, spinning, and forging processes, enabling scale advantages in high-volume passenger vehicle programs. Borbet, a family-owned German manufacturer, emphasizes quality, style, and off-road applications across light alloy wheels for cars, caravans, campers, and commercial vehicles. Ronal Wheels positions itself as a premier global supplier of forged and multi-piece alloy wheels, spanning passenger cars, SUVs, commercial vehicles, and premium or racing-oriented lines. Maxion Wheels and Iochpe-Maxion reinforce the southern hemisphere's strategic importance, with Maxion supplying steel and aluminium alloy wheels across passenger, commercial, and specialty segments through global production networks, while Iochpe-Maxion leverages its leadership in aluminium wheels and structural components with targeted expansion in South America for light-vehicle applications.
Aluminum Alloy Wheels Market
The aftermarket and performance segments introduce a parallel competitive layer. Enkei supplies major Japanese and global automakers with lightweight OEM and aftermarket alloy wheels, while American Racing delivers performance, custom, and vintage designs with strong aftermarket credibility. Wheel Pros functions as a designer and marketer of aftermarket alloy wheels that is actively expanding into forged and high-performance luxury segments. Alcoa Corporation maintains its position as a global leader in forged aluminium wheels, emphasizing sustainable, low-carbon solutions for premium and OEM applications. MAK Wheels rounds out the competitive field as an Italian manufacturer of custom alloy wheels for cars, SUVs, 4x4, and heavy-duty applications, with recent dedicated model development for major OEMs.
Recent product activity underscores the pace of innovation and brand differentiation. In early 2026, MAK Wheels introduced its 2026 collection, including the KULT and AURUM models dedicated to BMW and Mercedes-Benz programs alongside the LEGEND model developed for 4x4, heavy-duty, and camper applications. Earlier in 2025, MAK launched the Stark flagship alloy wheel targeting Volkswagen Group vehicles and broader SUV and car segments, while American Racing announced the TTF II drag-inspired wheel designed for high-performance trucks. These launches reflect a dual strategy across the industry: OEM program exclusivity that secures volume stability, and aftermarket or specialty positioning that supports premium pricing and brand affinity.
Demand Architecture Across Vehicles, Channels, and Processes
Demand segmentation analysis reveals how revenue is distributed across vehicle types, sales channels, and manufacturing methodologies, providing essential context for capacity planning and product mix optimization. Passenger vehicles account for the larger share of total market revenue, while commercial vehicles represent a substantial secondary pool driven by fleet durability, total cost of ownership considerations, and heavy-duty load requirements. The channel split between OEM and aftermarket demand further clarifies where volume stability and margin flexibility intersect. OEM relationships deliver multi-year program visibility but introduce price compression cycles and technical qualification burdens. Aftermarket demand offers faster response to design trends and regional customization, though it remains more exposed to discretionary spending cycles and retail channel dynamics.
Manufacturing process segmentation adds another layer of strategic relevance. Casting remains the dominant process by revenue, reflecting its cost efficiency and suitability for high-volume passenger vehicle programs. Forging contributes a meaningful share associated with strength-to-weight advantages and premium positioning, particularly in performance and light-duty commercial applications. Flow forming occupies a more specialized role, often bridging cost and performance objectives for targeted applications. Because each process carries distinct capital intensity, cycle time, material yield, and qualification requirements, participants must evaluate their process portfolios against the specific growth profile of their target segments rather than treating process capability as a generic competitive lever.
Automotive Aluminium Alloy Wheels Market
Operating Environment: Cost Volatility, Tariffs, and Regulatory Acceleration
The operating environment in 2026 and beyond is shaped by three interlocking forces: raw-material cost volatility, evolving trade policy, and tightening emission regulations. Aluminium prices represent a dominant share of production costs in automotive aluminium alloy wheels, and annual price fluctuations in the range of 18 to 22 percent continue to exert pressure on manufacturer margins. Suppliers without integrated procurement strategies, long-term supply agreements, or effective hedging programs face structural disadvantage when market conditions shift suddenly. Recruitment of low-carbon and recycled aluminium content is increasingly viewed as a dual-purpose response, supporting both cost resilience and sustainability commitments while opening access to 고객에게 preferred supplier status in OEM networks.
Trade policy developments have introduced new complexity to cross-border sourcing. Tariff actions on aluminium articles have raised the cost of imported wheels and parts, directly affecting landed-cost calculations for distributors, retailers, and OEM supply chains that rely on international procurement. At the same time, proposed and implemented tariff escalations on goods from key trading partners create uncertainty around supply continuity and shift the attractiveness of regional production footprints. Companies that previously optimized solely for unit cost must now incorporate tariff exposure, logistics flexibility, and customs-resolution timelines into their sourcing models. The result is a market in which tariff-aware capacity placement and dual-sourcing strategies are becoming baseline requirements rather than optional safeguards.
On the regulatory side, tightening CO2 emission targets for passenger cars are accelerating OEM demand for lighter aluminium alloy wheels as one component of broader fleet efficiency improvement programs. Weight reduction contributes directly to fuel economy and electric range performance, making alloy wheel specifications a tangible lever within multi-parameter engineering optimization. This regulatory push reinforces long-term demand for lightweight structures and supports premium positioning for suppliers that can demonstrate measurable weight savings, consistent quality, and compliance with OEM specifications. As vehicle architectures evolve, especially within electrified platforms, wheel design requirements may also shift toward thermal management, load distribution, and integration with suspension and braking systems, creating opportunities for suppliers with advanced engineering capabilities.
Sustainability, Recycling, and Strategic Capacity Evolution
Sustainability expectations are reshaping procurement priorities and capacity investment decisions. Recycled aluminium content in wheels is increasing as manufacturers seek to align with corporate environmental goals and customer-facing sustainability commitments. New production line investments in markets such as Mexico and Brazil are expanding capacity for low-pressure cast aluminium wheels while supporting the broader transition toward lower-carbon material inputs. This evolution is not merely a compliance exercise; it affects supplier qualification, brand positioning, and long-term cost structure as recycled material availability and processing efficiency improve.
For OEM-facing suppliers, sustainability credentials increasingly intersect with commercial competitiveness. Programs that can demonstrate traceability, reduced embedded carbon, and consistent mechanical performance are better positioned to win and retain high-value contracts. For aftermarket players, sustainability messaging can support premium pricing in segments where customers value environmental responsibility alongside aesthetics and performance. However, the operational reality is that sustainability investments must be paired with disciplined cost management and process reliability. Otherwise, the margin impact of raw-material volatility can quickly offset the strategic benefits of greener sourcing.
Strategic Implications for 2026 Decision-Making
Translating this landscape into actionable strategy requires a disciplined focus on several priority areas. First, portfolio alignment should distinguish between volume stability in OEM programs and margin opportunity in aftermarket and performance segments, ensuring that capacity and commercial resources reflect the distinct economics of each channel. Second, process configuration must be reviewed against segment growth profiles, with casting supporting high-volume cost competitiveness, forging enabling premium differentiation, and flow forming addressing targeted performance niches. Third, supply chain architecture should incorporate tariff-aware sourcing, regional flexibility, and raw-material risk management, given the persistent volatility of aluminium prices and the ongoing evolution of trade measures.
Fourth, sustainability and lightweighting should be treated as interconnected strategic priorities rather than separate initiatives. The same engineering capabilities that reduce weight can often be paired with lower-carbon material strategies and recycling pathways that strengthen OEM qualification and aftermarket positioning. Fifth, competitive intelligence should go beyond headline market shares to assess process mix, program pipeline visibility, regional footprint, and brand strength within specific vehicle types and customer segments. In a market where the top three participants collectively account for just over a quarter of revenue, the ability to capture differentiated value depends on precision positioning rather than scale alone.
What the Full Report Delivers
This summary frames the strategic questions that matter most entering 2026, but the complete report provides the detailed segmentation, competitive benchmarking, and scenario analysis required to convert direction into execution. The full study breaks down market size and growth trajectories by region, vehicle type, OEM versus aftermarket channels, and manufacturing process, enabling precise identification of where growth is concentrated and where margin pressure is most acute. It examines competitive positioning for key global suppliers, incorporating recent product launches, technology focus, and regional expansion patterns, while contextualizing operating dynamics through raw-material cost volatility, tariff developments, and regulatory demand drivers. The analysis also explores sustainability trends and capacity evolution, offering practical frameworks for evaluating sourcing strategy, product mix, and program prioritization.
For executives responsible for capital allocation, product planning, procurement, or market entry, the complete report functions as a decision-support tool that turns market complexity into structured insight. The full dataset, segmentation detail, and competitive profiles are available through the source market research page, where readers can access the complete intelligence package designed to support 2026 strategy formulation and execution.
For detailed analysis of this topic, please visit the official page: Automotive Aluminium Alloy Wheels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


