



PwC Consulting: Carbon Capture Market to Hit $329M by 2032 with 10.5% CAGR

Strategic Intelligence for the Carbon Capture Era: Unlocking Value in the 2026-2032 Market Cycle
The global transition toward net-zero emissions has moved decisively from policy aspiration to industrial execution. As enterprises across heavy industry, energy, and infrastructure confront tightening regulatory frameworks and intensifying investor scrutiny, carbon capture and storage (CCS) has evolved from a niche mitigation option into a core component of long-term operational resilience. The CCS market is now entering a phase of structural acceleration, characterized by expanding project pipelines, maturing capture technologies, and increasingly complex commercial architectures. For leadership teams navigating capital allocation, supply chain strategy, and compliance positioning in 2026, a rigorous, forward-looking market intelligence foundation is no longer optional. It is a prerequisite for competitive advantage.
Our latest Carbon Capture and Storage Market research study, anchored in historical performance from 2020 through 2025 and projecting through 2032, offers a comprehensive decision-support framework designed specifically for executive strategy, corporate development, and investment planning functions. The study is structured to translate macro-level market momentum into actionable intelligence, enabling organizations to anticipate demand shifts, evaluate technology pathways, and align partnership strategies with the trajectory of a rapidly consolidating industry.
Macro Trajectory and Revenue Outlook
The CCS market has demonstrated sustained expansion over the past half-decade, with revenue performance reflecting the compounding effect of policy tailwinds, corporate decarbonization commitments, and the gradual commercialization of flagship capture, transport, and storage clusters. Historical data from 2020 to 2025 maps a consistent upward curve, driven by early-mover deployments, pilot-to-commercial scale-ups, and the progressive alignment of carbon pricing mechanisms with industrial implementation timelines. Building on this foundation, the forecast period from 2026 to 2032 projects a compound annual growth rate of 10.5 percent, signaling a market that is scaling past the experimentation phase and entering a period of accelerated commercial maturation.
By the close of the forecast window, cumulative market revenue is positioned to reach a materially higher valuation environment than the current baseline, underscoring the strategic importance of timing in capacity commitments, technology licensing, and infrastructure partnerships. This trajectory is not uniformly distributed across all segments or geographies. Rather, it reflects a differentiated landscape in which capture readiness, storage accessibility, offtake economics, and regulatory clarity collectively determine which projects advance and which stall. The report provides the analytical scaffolding necessary to navigate these divergences, mapping demand drivers and cost dynamics without relying on simplistic aggregate assumptions.
Technology Pathways and Segment Dynamics
The commercialization of CCS is fundamentally shaped by the technological architecture chosen to separate, compress, and prepare CO2 for transport and permanent storage. Post-combustion capture remains a central focus for retrofit applications, particularly in power generation and existing industrial facilities where minimizing disruption to ongoing operations is paramount. Pre-combustion pathways continue to attract interest in integrated gasification and hydrogen-adjacent contexts, where capture can be embedded into process design rather than layered onto legacy infrastructure. Oxy-fuel and emerging alternative approaches serve specialized use cases, offering performance characteristics that align with specific fuel inputs, thermal profiles, and concentration environments.
Each technology pathway carries distinct implications for capital intensity, operational expenditure, solvent or media management, and long-term reliability. The report dissects these trade-offs across the commercial landscape, examining how adoption patterns are influenced by plant lifecycle stage, emissions concentration, and the availability of downstream storage or utilization infrastructure. Importantly, the analysis also accounts for the practical realities of component supply chains, where CO2 processing conditions demand durable materials and specialized fabrication, translating directly into cost structures and project execution risk. Organizations evaluating capture investments or vendor partnerships require this level of operational granularity to avoid over-reliance on laboratory-scale promise or untested scale-up assumptions.
Industrial Applications and Demand Architecture
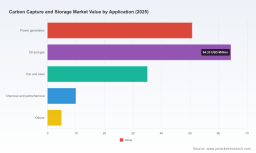
CCS demand is not a monolith. It is anchored in a set of industrial applications where decarbonization is technically challenging, emissions intensity is high, and alternative mitigation options remain limited or cost-prohibitive. Power generation continues to represent a significant deployment context, particularly where grid decarbonization timelines intersect with asset longevity and retrofit feasibility. Oil and gas operations present a distinct opportunity set, combining enhanced recovery economics with the operational capability to manage large-volume capture, transport, and injection workflows. Iron and steel production, cement manufacturing, and chemical and petrochemical processing each introduce unique process integration challenges, driving demand for tailored capture configurations, waste heat utilization, and site-specific storage solutions.
The study assesses how these application verticals are shaping procurement behavior, partnership models, and project prioritization. It examines the interplay between regulatory pressure, customer-facing sustainability requirements, and the internal economics of emissions abatement, providing a nuanced view of where CCS adoption is most likely to accelerate and where friction points will persist. This application-level perspective is critical for suppliers, engineering firms, and industrial emitters seeking to align product roadmaps and commercial strategies with the sectors that will generate sustained demand over the next several years.
Competitive Landscape and Strategic Positioning
The CCS industry is defined by a blend of industrial gas integrators, engineering and construction specialists, technology licensors, and integrated energy operators. This mix reflects the multidisciplinary nature of CCS value chains, which span capture system design, solvent and materials engineering, pipeline and terminal infrastructure, offshore or onshore storage development, and long-term commercial offtake arrangements. Within this environment, competitive advantage increasingly depends on an organization's ability to integrate across multiple value chain segments, secure recurring commercial agreements, and demonstrate proven deployment experience at commercial scale.
Linde plc stands out as a leading provider of large-scale post-combustion CO2 capture systems and industrial gases integration for CCS projects, including long-term commercial agreements for CO2 transport and storage. Its positioning underscores the strategic importance of combining capture technology with broader gas handling expertise and durable offtake frameworks. Mitsubishi Heavy Industries has built a recognized footprint through its KM-CDR Process and Advanced KM-CDR Process amine-based post-combustion capture technology, with more than 14 commercial plants delivered worldwide, reinforcing the value of demonstrated operational track records in a market where performance risk remains a critical procurement concern.
Shell CANSOLV continues to develop and license its regenerable amine technology for post-combustion CO2 capture, with performance credentials reaching up to 99 percent removal efficiency. This level of capture effectiveness is increasingly relevant as emitters confront stricter compliance thresholds and stakeholder expectations. Aker Solutions operates as an engineering, procurement, and construction provider specializing in CCS capture plants, CO2 terminals, and storage infrastructure, illustrating the capital-intensive, delivery-centric dimension of the market. Fluor Corporation complements this landscape as an engineering and construction firm delivering full-scale CCS project execution and retrofits for industrial and power applications, where integration expertise and schedule discipline often determine project outcomes.
On the operator side, ExxonMobil has advanced multiple integrated CCS projects providing capture, transport, and permanent storage services for industrial emitters, including partnerships with CF Industries and Nucor. Its recent operational milestones, including the startup and expansion of commercial CCS activities in Louisiana, reflect a broader trend in which major energy and industrial companies are positioning CCS as both a service offering and an internal decarbonization lever. SLB contributes advanced carbon capture technologies, including SLB Capturi systems and pilot-scale solutions for industrial emitters, extending the footprint of technical innovation into a broader set of deployment contexts.
The report evaluates these market participants and others through a structured competitive lens, analyzing positioning, capability breadth, technology focus, and recent activity patterns. It also examines market concentration dynamics, where a defined group of leading players accounts for a substantial share of activity, shaping pricing expectations, partnership scarcity, and the strategic calculus for new entrants seeking to establish credibility in a technically demanding market.
Regulatory and Commercial Dynamics Shaping Deployment
Technology alone does not determine market outcomes. The pace and pattern of CCS deployment are increasingly governed by the interaction between regulatory design, incentive architecture, and infrastructure readiness. In Europe, the European Commission is reviewing the EU ETS Directive, with findings expected by July 2026, including the potential integration of permanent carbon removals and municipal waste incineration. This regulatory evolution could reshape eligibility, compliance pathways, and the economic rationale for capture investments across multiple sectors. At the same time, the EU ETS has reserved 300 million allowances in the New Entrants Reserve to fund deployment of innovative renewable energy technologies and carbon capture and storage, creating a policy-backed channel that may influence early-stage project financing and commercial risk allocation.
Carbon Capture and Storage Market
Cost structures remain highly sensitive to project context. Offshore transport and storage scenarios have consistently exhibited the highest unit costs relative to onshore alternatives, while overall expenses vary widely by project location due to differences in labor, freight, fuel, and electricity rates. These variables complicate benchmarking and make localized analysis essential for investment decisions. Compounding this complexity, harsh chemical effects in CO2 processing require expensive special steel alloys for plant components, reinforcing the importance of materials engineering and procurement strategy in total cost-of-ownership assessments.
Recent industry activity further illustrates the market's accelerating rhythm. In mid-2025, the Global CCS Institute published its Global Status of CCS 2025 report, documenting a 54 percent year-on-year increase in operational projects to 77, a signal that commercialization is broadening beyond a narrow set of flagship initiatives. By early 2026, ExxonMobil had begun transporting and storing CO2 from the New Generation Gas Gathering project in Gillis, Louisiana, expanding its CCS operations footprint. In mid-2025, the company also commenced operations for a commercial CCS project with CF Industries in Donaldsonville, Louisiana, capturing up to 2.5 million metric tons of CO2 annually. More recently, in May 2026, the Global Cement and Concrete Association signed a Memorandum of Understanding with the Global CCS Institute to advance the use of carbon capture and storage across the global cement and concrete industry. These developments, taken together, reflect a landscape in which partnership formation, operational startup, and sector-specific engagement are all intensifying.
What the Report Delivers for 2026 Decision-Making
This Carbon Capture and Storage Market study is constructed to serve as a sustained strategic reference rather than a one-time snapshot. It provides a detailed examination of market sizing and forecast logic across the 2026-2032 horizon, grounded in the historical performance of the 2020-2025 period. The analysis spans technology types, application segments, and regional demand environments, with an emphasis on the structural factors that differentiate high-conviction deployment pathways from lower-probability activity. It also integrates competitive profiling, market concentration assessment, and recent corporate developments to help readers interpret strategic positioning, partnership opportunity, and execution risk.
Beyond aggregate market direction, the report addresses the operational and commercial levers that executive teams face in practice: how capture technology selection affects long-term operating economics, how infrastructure availability shapes project feasibility, how regulatory evolution influences compliance and revenue models, and how leading organizations are structuring collaborations to share risk and accelerate deployment. The objective is to equip strategists, investors, and business leaders with a defensible analytical basis for prioritizing investments, evaluating vendor and partner ecosystems, and anticipating the next wave of market consolidation.
Carbon Dioxide (CO2) Market
For organizations seeking to move beyond headline narratives and into the operational realities of CCS commercialization, this research offers a structured, evidence-based portal into the market's most consequential dynamics. To access the full dataset, detailed segmentation analysis, complete company profiles, and forward-looking scenario frameworks, visit the full report page and secure the complete intelligence package designed for 2026 strategic planning.
For detailed analysis of this topic, please visit the official page: Carbon Capture and Storage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


