



PW Consulting: Fiber Optic Cable Assembly Market to Reach $11.13B by 2032 at 6.9% CAGR

Fueling High-Velocity Networks: The Strategic Imperative Behind the 2026 Fiber Optic Cable Assembly Market Outlook
As global digital infrastructure accelerates toward 2032, leaders across telecommunications, data center development, aerospace, and public-sector engineering are navigating a market defined by compounding demand, evolving regulatory frameworks, and intensifying competitive maneuvering. The Fiber Optic Cable Assembly Market has transitioned from a purely operational procurement category to a strategic leverage point for enterprises seeking bandwidth resilience, latency optimization, and future-proof connectivity architectures. Our newly released research offering provides a comprehensive, decision-oriented exploration of this landscape, mapping historical trajectories, forward-looking growth corridors, and the operational realities that will shape purchasing, positioning, and partnership strategies throughout the 2026–2032 forecast horizon.
For executives evaluating capacity planning, vendor consolidation, or geographic expansion in the coming fiscal year, the underlying market signals warrant close attention. Drawing on a rigorous analytical framework anchored in historical performance through 2025 and extending across the 2026–2032 forecast window, this research translates macro-level momentum into actionable strategic context. Rather than offering static snapshots, the study is designed to help leadership teams anticipate inflection points, stress-test assumptions, and align capital allocation with the structural drivers reshaping fiber connectivity value chains.
Decoding the Macro Trajectory: Why the Growth Curve Matters for 2026 Planning
The market has demonstrated consistent expansion across the historical review period, reflecting a steady escalation in demand for high-performance cable assemblies that support increasingly data-intensive networks. By the close of the base year, total market revenue had climbed to a substantial milestone, underscoring the durability of fiber-based connectivity as a foundational infrastructure layer. The forecast period projects continued upward momentum, with the overall market expected to advance at a compound annual growth rate of 6.9 percent through 2032. For strategists, this trajectory is more than a headline figure; it signals a sustained demand environment in which capacity missteps, overly conservative sourcing models, or delayed technology adoption can create competitive disadvantages that compound over multiple planning cycles.
Importantly, the growth profile reflects more than incremental volume increases. It encapsulates shifting end-user expectations around reliability, signal integrity, deployment speed, and lifecycle durability. As enterprises and public institutions push bandwidth requirements higher while tightening tolerance for failure points, the cable assembly segment sits at the intersection of physical-layer performance and strategic network design. Decision-makers evaluating product roadmaps, inventory strategies, and supply commitments in 2026 must therefore interpret growth not merely as a sizing exercise, but as an indicator of where performance specifications, qualification standards, and application-specific requirements will become increasingly binding.
Inside the Research: What Decision-Makers Will Find
This study is structured to support practical, executive-level decision-making rather than abstract market commentary. It delivers a layered analytical architecture that connects high-level sizing context with granular structural insights, enabling readers to isolate the drivers most relevant to their operating environment. The report examines the market through multiple strategic lenses, including:
- Structural segmentation analysis that clarifies how demand patterns diverge across cable assembly formats, end-use applications, and regional deployment realities, helping teams pinpoint where specification requirements and procurement cycles differ most sharply.
- Competitive positioning and profiling of leading and emerging participants, including operational footprints, product focus areas, and the strategic moves that are reshaping share dynamics and customer value propositions.
- Regulatory and standards-driven dynamics that assess how qualification frameworks, customs and trade policy developments, and infrastructure-era procurement practices are influencing sourcing risk, compliance planning, and regional competitiveness.
- Deployment and production context covering the operational prerequisites that distinguish high-precision assembly environments, including cleanroom-class manufacturing considerations, testing rigor, and the practical implications for lead times, customization, and reliability assurance.
- Recent event intelligence tied to corporate collaborations, product catalog evolution, major infrastructure rollouts, and regulatory updates, providing a real-time anchor for interpreting how the competitive and operating landscape is shifting on the ground.
Each section is designed to feed directly into commercial assessment, procurement strategy, and forward planning. The goal is not simply to show what the market has been, but to equip leadership with the context needed to evaluate where to invest, where to standardize, and where to differentiate in a segment that rewards both technical precision and strategic timing.
Competitive Landscape and Strategic Positioning Signals
The fiber optic cable assembly market remains structurally fragmented, with a top-three concentration that reflects meaningful but not dominant consolidation among leading manufacturers and solution providers. This competitive configuration creates a distinctive environment: large-scale incumbents can leverage established manufacturing capabilities, broad product portfolios, and long-standing customer relationships, while specialized players compete on precision, customization, qualification readiness, and application-specific engineering. For procurement leaders and strategy teams, the implication is clear. Vendor evaluation cannot be reduced to unit pricing alone; total value increasingly depends on qualification support, delivery predictability, design flexibility, and the supplier's ability to align with the technical and regulatory demands of the target deployment environment.
Several market participants illustrate the range of strategic postures now shaping the segment. Optical Cable Corporation has built its profile around military, tactical, and commercial enterprise fiber optic cable assemblies and connectivity solutions, spanning both pre-terminated and custom variants. In mid-2025, the company entered a strategic collaboration agreement with Lightera, LLC, including an investment component, aimed at expanding offerings for data center and enterprise applications. That move signals a deliberate pivot toward higher-growth infrastructure end-markets and reflects a broader industry pattern in which traditional manufacturers are reinforcing capabilities where bandwidth demand and deployment velocity are most acute.
Diamond SA exemplifies the precision-engineering orientation that increasingly differentiates suppliers serving demanding use cases. Based in Switzerland, the company specializes in high-precision fiber optic interconnects and assemblies and maintains cleanroom production environments tailored to enterprise, space, and other stringent applications. In a market where signal integrity and contamination control can directly affect qualification success, this production philosophy highlights the operational premium attached to controlled-assembly environments. Meanwhile, L-com Global Connectivity continues to emphasize ruggedized and pre-terminated fiber optic cable assemblies, patch cords, and custom connectivity solutions for networking and industrial applications, reinforcing the importance of durability and field-readiness in industrial and critical-infrastructure settings.
Cable Assembly Market
On the distribution and customization side, Fiber Instruments Sales, Inc. provides a broad catalog of fiber optic cable assemblies, including fusion-spliced and field-installable options, bridging manufacturing output with practical deployment flexibility. fiberone, llc has similarly emphasized customer-specific design in its custom multi-fiber cable assemblies, adjusting lengths, breakouts, and pulling eyes to meet precise project requirements. Recent activity from fiberone, llc in early 2026, including an updated product catalog and refreshed emphasis on customer-specific designs, illustrates how tailored specification support remains a competitive differentiator for projects where off-the-shelf configurations are insufficient. Taken together, these profiles show a market in which competitive advantage is being constructed through a blend of manufacturing discipline, application specialization, partnership strategy, and responsiveness to project-level engineering requirements.
Regulatory Currents, Trade Realities, and Deployment Economics
Strategic sourcing in fiber optic cable assemblies cannot be separated from the regulatory and policy environment shaping cross-border trade, safety qualification, and public infrastructure procurement. One of the most consequential developments for safety-critical deployments came from the Nuclear Regulatory Commission, which issued Regulatory Guide RG 1.257 in August 2025. The guide addresses the qualification of fiber-optic cables, connections, and optical fiber splices for use in safety systems within production and utilization facilities. For organizations operating in or supplying to regulated environments, this type of guidance directly affects validation pathways, documentation expectations, and the burden of demonstrating long-term reliability under defined operating conditions.
Trade policy remains another critical variable. Implementation of Section 301 tariffs on optical fiber cables from China continues to impose a 25 percent additional duty, and industry commentary submitted to BIS in late 2025 noted that these measures remain in effect without coverage under Section 232 tariffs. For sourcing teams, the practical consequence is a persistent cost and supply-chain consideration that can influence origin decisions, inventory timing, and supplier diversification strategies. Executives evaluating total landed cost, qualification continuity, and geopolitical exposure must factor these duties into scenario planning rather than treating them as transient conditions.
At the infrastructure level, fiber deployment economics remain highly project-dependent. Recent cost-plot updates from U.S. Department of Transportation ITS KRS, including revisions to roadside telecommunications fiber optic cable installation costs, highlight the sensitivity of project budgets to installation context, geography, and operational constraints. Public-sector and private infrastructure programs alike must contend with cost variability that can reshape feasibility assessments and phased rollout plans. In parallel, legislative interest in fiber infrastructure security has continued to gain visibility, including the introduction of the Bipartisan Strategic Subsea Cables Act of 2026, which proposes expanded U.S. government engagement around subsea fiber-optic cable security, maintenance, and repair. While subsea systems represent a distinct layer of the broader connectivity ecosystem, the policy direction reinforces a widening recognition of fiber infrastructure as a strategic asset worthy of heightened oversight and coordinated response frameworks.
These overlapping forces illustrate why the market cannot be understood through sizing alone. Regulatory qualification, tariff exposure, installation cost variability, and infrastructure security priorities all influence how quickly projects move, which suppliers are eligible, and how procurement teams balance cost efficiency with resilience. The research incorporates these dynamics as active variables in the market outlook, helping readers connect policy and operational realities to commercial planning.
Why 2026 Is a Decision Pivot Point
The current forecast window places unusual importance on early-cycle decisions. With market value projected to rise materially from the 2026 base estimate toward the end of the decade, organizations that define their sourcing architectures, qualification strategies, and application focus early are better positioned to manage cost structures, secure supply continuity, and align product capabilities with the most attractive demand pools. Conversely, teams that defer structural decisions risk entering a more crowded, more regulated, and more cost-sensitive environment with less flexibility.
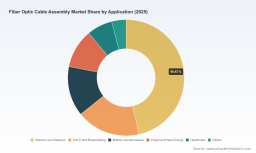
Several practical imperatives follow from this outlook. First, demand planning should be anchored in application-specific requirements rather than aggregate volume alone. The growth trajectory is being shaped by differing needs across telecom and datacom environments, broadcasting and CATV deployments, military and aerospace specifications, power and new energy applications, healthcare installations, and other specialized use cases. Each of these segments carries its own performance thresholds, qualification expectations, and purchasing rhythms, making segmented insight essential for accurate forecasting and effective product positioning.
Fiber Optic Cable Assembly Market
Second, supply-chain strategy should account for both performance assurance and policy exposure. Cleanroom-class production environments, precision assembly practices, and rigorous testing protocols are not merely operational details; they are increasingly central to winning qualification-sensitive work and differentiating from lower-spec alternatives. At the same time, tariff structures and sourcing origins can materially affect total cost and supply predictability, requiring scenario-based procurement planning rather than single-path sourcing assumptions.
Third, competitive strategy should recognize that the market rewards a blend of scale, specialization, and adaptability. Some participants compete by expanding into high-growth data center and enterprise segments through collaboration and investment. Others compete by deepening precision manufacturing and application-specific engineering. Still others compete through catalog breadth, distribution reach, or customization capability. Understanding where a company’s own strengths align with these competing logics is essential for positioning, partnership selection, and long-term share capture.
From Intelligence to Action: What the Full Study Enables
The overview presented here is intended to demonstrate the analytical rigor and strategic relevance of the full report, while deliberately preserving the deeper segmentation data, quantification detail, and comparative frameworks that justify the complete study. Enterprise teams that rely on a high-level summary alone risk missing the structural nuance that determines where growth is concentrated, how competitive pressure is distributed, and which operational requirements will most influence sourcing outcomes in specific deployment contexts.
The complete research offering expands on every dimension introduced here, providing the detailed market sizing breakdown, segmentation insight, and competitive profiling required to support precise planning. It enables readers to move from general market confidence to targeted decision support by revealing how demand is distributed across cable assembly types, application areas, and regional dynamics, and by placing those patterns in the context of recent corporate moves, regulatory developments, and infrastructure activity. For organizations preparing budgets, product strategies, qualification roadmaps, or expansion plans for 2026, that level of detail is not optional; it is the difference between reactive planning and strategically informed execution.
The market is expanding, but expansion alone does not create advantage. Advantage is created by understanding where the growth is structurally grounded, which requirements will become non-negotiable, and how competitive and regulatory forces will reshape the cost and capability equation over the next several years. Our full market research is designed to deliver exactly that level of intelligence. We invite decision-makers to access the complete study to obtain the comprehensive segmentation data, comparative analysis, and forward-looking strategic context needed to translate this market outlook into concrete, high-confidence action throughout the 2026–2032 forecast period.
For detailed analysis of this topic, please visit the official page: Fiber Optic Cable Assembly Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


