



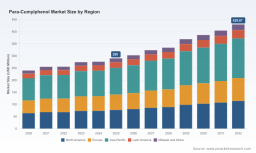
PW Consulting: Para-Cumylphenol Market to Hit $429.87M by 2032 with 5.8% CAGR from $290M in 2025

Para-Cumylphenol Market Strategic Outlook 2026: Navigating Growth, Consolidation, and Application Diversification
The global chemical intermediates sector is entering a decisive phase where precision, supply chain resilience, and formulation agility separate market leaders from passive participants. Within this landscape, para-cumylphenol (PCP) has emerged as a foundational building block across multiple high-value downstream industries. Our latest market research delivers a comprehensive, data-driven assessment of the para-cumylphenol market, designed specifically to equip corporate strategists, procurement leaders, and R&D directors with the analytical clarity required for sound 2026 decision-making. This report does not merely track historical volume; it maps the structural forces, competitive pressures, and application shifts that will define commercial trajectories through the end of the decade.
Firms operating in specialty chemicals, advanced materials, and formulation science cannot afford to rely on fragmented supplier briefings or outdated industry snapshots. The para-cumylphenol value chain is experiencing measurable evolution in capacity deployment, grade differentiation, and regional demand pacing. Our analysis integrates verified historical tracking from 2020 through 2025 with a forward-looking projection window spanning 2026 to 2032. The overarching revenue trajectory reflects a compound annual growth rate of 5.8 percent, moving from a baseline valuation of approximately 290.0 million USD in the base year to a projected 429.87 million USD by 2032. These figures are not abstract indicators; they represent the cumulative impact of resin engineering upgrades, adhesive formulation modernization, coating performance mandates, and expanding pharmaceutical intermediate requirements. For executives planning capital allocation, vendor qualification, or geographic footprint adjustments, understanding the pace and composition of this expansion is indispensable.
Why 2026 Demands a Refined Strategic Lens
The current operating environment requires more than top-line forecasting. Companies must evaluate how grade specifications, regional supply dynamics, and end-use substitution patterns interact to shape pricing power, availability, and long-term contract viability. Our research framework is built to surface those linkages without obscuring the operational realities that drive them.
4-Cumylphenol Market
First, the transition from generic chemical sourcing to specification-aligned procurement has intensified. Manufacturers are no longer selecting para-cumylphenol solely on cost; they are evaluating purity thresholds, impurity profiles, batch consistency, and downstream compatibility. Second, the concentration of supply among established producers has created a market structure where relationship management, technical support, and continuity assurance carry substantial commercial weight. Third, application-side innovation is accelerating requirements for tailored intermediate performance, pushing suppliers to align production capabilities with formulation roadmaps rather than treating PCP as a commoditized feedstock. These dynamics converge in 2026, making structured market intelligence a strategic asset rather than an optional reference document.
Report Architecture: What Decision-Makers Will Find Inside
This study is engineered for immediate operational relevance. Rather than presenting isolated statistics, the report constructs a connected analytical narrative that spans market sizing, segmentation logic, competitive positioning, and forward risk mapping. The structure is intended to support multiple decision contexts, from board-level strategic reviews to procurement planning and R&D prioritization.
Readers will encounter a meticulously documented historical reconstruction covering the 2020 to 2025 period, establishing a transparent baseline against which future projections are calibrated. The forecast component extends through 2032 and translates macro-growth signals into actionable directional intelligence. The segmentation architecture dissects the market along multiple commercial dimensions, including product grade classification, application end-use categories, and regional demand distribution. Each segmentation layer is analyzed not as a standalone table, but as an interactive variable that influences pricing behavior, capacity utilization, and supplier selection criteria.
Para-Cumylphenol Market
Beyond sizing and segmentation, the report delivers practical operational content designed to support execution. This includes:
- Detailed assessment of grade differentiation dynamics, with emphasis on how high-purity and low-purity streams serve distinct downstream requirements and pricing environments
- Application-side evaluation that traces how resins, adhesives, coatings, pharmaceutical intermediates, and other industrial uses shape demand stability, substitution risk, and formulation trends
- Regional demand profiling that identifies where consumption momentum is building, which markets are maturing, and how logistical or regulatory factors influence supply routing
- Supply-side structural review that examines capacity deployment patterns, production concentration, and the strategic implications of a consolidated supplier base
- Forward-looking scenario framing that helps organizations stress-test assumptions around volume growth, specification upgrades, and competitive re-alignment through the late 2020s
Every section is cross-referenced to ensure that sizing logic, segmentation behavior, and competitive context reinforce one another. The result is a cohesive intelligence package that allows strategy teams to move from high-level market awareness to targeted commercial action.
Competitive Landscape: Consolidation, Capability, and Commercial Positioning
The para-cumylphenol market is characterized by a notably concentrated supplier environment. Market structure indicators point to a high degree of consolidation, with the top three participants accounting for approximately 80 percent of industry revenue and the top five reaching roughly 82 percent. This concentration is not simply a statistical footnote; it shapes bargaining dynamics, technical service expectations, and supply continuity planning for downstream buyers. In a market where a limited number of producers control the majority of output, relationship durability, specification reliability, and responsiveness to customization requests become central competitive differentiators.
SI Group, Inc., headquartered in Albany, New York, operates as one of the primary large-scale industrial producers of para-cumylphenol. Its commercial relevance extends across multiple downstream pathways, serving as a key intermediate for surfactant production, a monomer for phenolic resins, and a chain terminator in polycarbonate applications. This multi-role positioning gives the company broad exposure to formulation trends and allows it to align production capabilities with diverse end-use requirements.
Dover Chemical, operating through ICC Industries in Findlay, Ohio, manufactures para-cumylphenol as a phenol-based monomer focused on polymer industry applications. Its production orientation reflects the ongoing importance of PCP in polymer engineering, where intermediate quality and consistency directly influence downstream material performance. Suppliers with this profile typically compete on technical reliability, batch control, and the ability to support polymer developers seeking predictable intermediate behavior.
On the Asia Pacific side, Shanghai ShengShan Chemical Technology Co., Ltd. stands out as a major manufacturing presence, recognized as one of China's largest producers of 4-cumylphenol with substantial monthly capacity. Its output supports a wide spectrum of downstream uses, including chemicals, pharmaceuticals, washing products, surfactants, fungicides, preservatives, stabilizers, and electronic-related applications. The breadth of this application base illustrates how a single intermediate supplier can anchor a diversified demand profile, reducing dependence on any single end-use cycle while increasing sensitivity to cross-sector regulatory and formulation shifts.
Beijing Xing Li Gong Mao Co., Ltd. operates as another important supplier within the hydroxybenzene, ketone, aether, and related product spectrum, offering p-cumylphenol as part of a broader intermediates portfolio. Suppliers of this type often compete through portfolio integration, technical documentation support, and supply flexibility, enabling downstream formulators to consolidate vendor relationships while maintaining access to multiple chemical inputs.
Together, these companies illustrate a competitive environment where scale, grade control, application breadth, and geographic positioning intersect. The report examines how such players manage capacity, respond to specification demands, and position themselves relative to regional consumption patterns. Understanding these competitive mechanics is essential for buyers assessing supplier resilience, for investors evaluating market entry or consolidation potential, and for producers benchmarking their strategic posture against established incumbents.
Market Dynamics Shaping Commercial Behavior
The para-cumylphenol market does not evolve in isolation. Its trajectory is influenced by interrelated forces that span raw material economics, downstream formulation priorities, regulatory expectations, and regional industrial development patterns. Our analysis frames these dynamics as actionable considerations rather than abstract trends.
One of the most consequential shifts is the increasing emphasis on performance specification over basic availability. As downstream industries seek improved durability, processing stability, and functional consistency, the value of higher-grade intermediates rises relative to lower-specification alternatives. This does not eliminate demand for standard purity streams, but it reorders commercial priorities and creates a two-tier market environment in which grade alignment, impurity control, and technical support increasingly influence purchasing decisions.
Another defining factor is the concentration of supply and its implications for continuity planning. In a market where a small number of producers command the majority of revenue, procurement teams must look beyond unit pricing and evaluate supplier stability, capacity commitment, and responsiveness to custom grade requests. This environment rewards long-term supplier alignment and makes supplier diversification strategies more complex, since meaningful alternatives may not always be available at comparable specification levels.
Regional demand behavior also plays a central role. Consumption patterns differ by industrial maturity, formulation adoption rates, and local manufacturing footprints. Some markets are driven by established resin and coating production ecosystems, while others are expanding through pharmaceutical intermediate needs, surfactant development, and specialized chemical applications. The report maps these regional variation patterns without reducing them to simplistic rankings, instead highlighting how local industrial structure, logistics, and demand composition influence purchasing rhythm and supply strategy.
How Organizations Can Use This Intelligence in 2026
The strategic value of this report lies in its ability to convert market complexity into structured decision support. For procurement and supply chain leaders, the analysis clarifies where specification requirements are tightening, which supplier relationships merit deeper due diligence, and how regional demand momentum may affect lead times and availability. For R&D and formulation teams, the segmentation and application discussion provides context on how intermediate quality, purity thresholds, and downstream compatibility expectations are evolving across resins, adhesives, coatings, pharmaceutical uses, and other industrial categories.
For executive strategists and corporate planners, the forward projection framework supports scenario planning around volume growth, grade migration, and competitive re-alignment. The report enables organizations to test assumptions about capacity expansion, pricing behavior, and application substitution without relying on unverified industry anecdotes. Investors and market entry teams can use the competitive structure and concentration analysis to evaluate barriers, supplier leverage, and the realistic scope for new capacity or partnership strategies.
Importantly, the study is designed to function as a living reference point for cross-functional alignment. When procurement, technical, and commercial teams share a common evidence base, decisions become faster, risk assessment becomes more disciplined, and supplier negotiations gain strategic context. That is the core purpose of this research: to provide a reliable foundation for 2026 planning and beyond.
What Is Reserved for the Full Report
This overview demonstrates the analytical depth, structural clarity, and commercial relevance of the full study. At the same time, the most operationally sensitive details are intentionally reserved for the complete report. The full version provides the precise segmentation values, regional breakdown figures, application-level revenue distribution, grade-specific sizing, and supplier-level competitive metrics that strategy teams need for concrete planning. Those data points are essential for building procurement models, capacity forecasts, and vendor evaluation matrices, but they are most effective when accessed in full context rather than in isolation.
The complete report also includes the integrated forecasting logic, historical calibration notes, supply-side structural interpretation, and application-side trend mapping that connect high-level market size to practical commercial action. For teams that require defensible numbers, supplier comparisons, and forward-looking scenario support, the full document delivers the granularity needed to move from directional insight to executable strategy.
Para-cumylphenol is no longer a background intermediate; it is a strategically significant input whose market structure, specification demands, and application breadth will increasingly shape downstream competitiveness. Organizations that equip themselves with rigorous, well-structured intelligence will be better positioned to manage supply continuity, align procurement with formulation roadmaps, and anticipate the commercial shifts that define the 2026 to 2032 window. The full report provides the complete evidentiary foundation for that undertaking.
For detailed analysis of this topic, please visit the official page: Para-Cumylphenol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


