



PW Consulting: AI in Agriculture Market to Hit $13.9B by 2032, Growing at 22.85% CAGR

Navigating the Harvest of Intelligence: Strategic Imperatives in the AI Agriculture Market (2026–2032)
Executive Preview: The Inflection Point for Agricultural Intelligence
The global agricultural sector is undergoing a structural transformation driven by artificial intelligence, shifting from incremental automation to foundational decision intelligence. As we move through 2026, the Artificial Intelligence (AI) in Agriculture market has crossed a critical adoption threshold. Recent market research indicates that the sector generated approximately $2.6 billion in revenue during the base year of 2025, reflecting a maturation phase where pilot deployments are rapidly transitioning into enterprise-grade agricultural operations. This trajectory is projected to accelerate through the end of the forecast period in 2032, with the market expanding to $13.9 billion. This represents a compound annual growth rate (CAGR) of 22.85%, signaling sustained capital allocation and accelerated commercialization across the agri-tech ecosystem.
Artificial Intelligence (AI) in Agriculture Market
For executive leadership, investors, and strategic planners, these aggregate figures represent more than macroeconomic momentum. They reflect a fundamental reordering of competitive advantage in food production. Organizations that treat AI as an operational utility rather than a discretionary technology investment are capturing disproportionate margins in yield optimization, input efficiency, and supply chain resilience. This market intelligence briefing outlines the strategic architecture of the AI agriculture landscape, equipped to guide resource allocation, partnership strategies, and risk mitigation in the 2026–2032 horizon.
Market Architecture and Growth Trajectory
The historical progression from 2020 to 2025 demonstrates a market that has consistently expanded despite macroeconomic headwinds and transitional supply chain constraints. Revenue climbed from $1.8 billion in 2020 to $2.6 billion by 2025, with minor cyclical fluctuations reflecting regional deployment pacing and platform maturity cycles. The forward-looking trajectory through 2032 indicates sustained expansion, with revenue scaling past $3.04 billion in 2026 and continuing to accelerate through the latter half of the forecast window.
This growth is underpinned by converging operational pressures and technological enablement. Agricultural operators are increasingly deploying AI to address structural labor constraints, input cost volatility, and climate-related yield unpredictability. The market is simultaneously being shaped by enterprise digitization initiatives, subsidies for precision technologies, and the standardization of agricultural machine learning datasets. Strategic decision-makers must recognize that the revenue expansion is not uniform across use cases or geographies; rather, it is concentrated in high-value application domains and regions with advanced digital infrastructure, creating distinct monetization pathways and competitive moats.
Core Application Domains and Technological Enablers
The AI agriculture ecosystem is organized around several foundational technological pillars and application segments that collectively drive value creation across the farm-to-market continuum. The dominant deployment patterns reflect a shift from isolated automation tools to integrated decision platforms that combine sensing, predictive modeling, and operational execution.
- Machine Learning continues to serve as the core analytical engine, enabling adaptive modeling for crop performance, input optimization, and risk forecasting across variable environmental conditions.
- Computer Vision has become critical for real-time field-level perception, supporting weed identification, crop health assessment, and automated guidance systems that reduce chemical usage and operational waste.
- Predictive Analytics is increasingly embedded in agronomic planning workflows, allowing growers and agribusinesses to anticipate weather impacts, soil conditions, and yield variability with greater temporal precision.
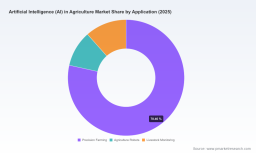
On the application side, Precision Farming remains the most extensively deployed category, integrating data-driven field management, variable-rate application, and equipment interoperability. Parallel growth is evident in Agriculture Robots and Livestock Monitoring, where AI-enabled automation addresses labor scarcity, animal welfare, and operational consistency. The strategic implication for enterprise buyers is clear: the highest near-term returns are emerging where AI is embedded directly into operational workflows rather than deployed as standalone analytics. Organizations evaluating market entry or capability expansion should prioritize integration depth, data interoperability, and measurable operational impact over feature breadth alone.
Competitive Landscape and Strategic Positioning
The market remains moderately fragmented, with a concentrated core of established players and a dynamic periphery of specialized innovators. Industry concentration metrics indicate that the top three competitors command approximately 24.6% of total market revenue, while the top five collectively account for 26.2%. This structure reflects an environment where scale advantages in data networks, platform ecosystems, and equipment integration coexist with niche differentiation in imaging, sensing, and agronomic intelligence.
Several incumbents and platform leaders define the current competitive architecture. John Deere continues to anchor its strategy in precision agriculture platforms that combine AI-driven autonomous equipment, computer vision for weed and crop identification, and centralized farm management data operations. Microsoft leverages its Azure FarmBeats ecosystem to unify machine learning, IoT sensing, drone imagery, and satellite data for precision farming insights and resource optimization. IBM contributes through its Watson Decision Platform for Agriculture, integrating AI, weather intelligence, and IoT streams to generate predictive crop health, soil, and weather insights. Bayer Crop Science extends its digital farming footprint via the Climate FieldView platform, applying AI-powered analytics for crop recommendations, risk management, and yield optimization. Trimble supports the space with AI-powered precision agriculture tools and connected solutions designed for machine guidance, data analysis, and operational efficiency.
Worldwide Agricultural Nanotechnology Market
Beyond the platform and equipment incumbents, a robust wave of specialized innovators is reshaping field-level intelligence. Valmont Industries applies integrated AI and machine learning to irrigation systems, crop monitoring, and anomaly detection through center-pivot technology. Taranis has built an AI-powered crop intelligence platform that uses machine learning and leaf-level imagery for disease detection, nutrient analysis, and agronomic recommendations. Gamaya combines hyperspectral imaging and remote sensing within an AI platform for crop health monitoring, yield prediction, and sustainability optimization. Ag Leader Technology focuses on precision farming technology for machine guidance, planting, and harvest optimization with integrated field operation data. Corteva Agriscience continues to expand digital tools and AI solutions for precision agriculture, including seed genetics and input recommendations.
Recent corporate activity underscores the velocity of this competitive evolution. In February 2026, John Deere announced its 2026 Startup Collaborator program, aligning with six ag-tech startups focused on AI, robotics, satellite analytics, and advanced sensing to strengthen precision farming capabilities. In October 2025, Taranis disclosed a strategic AI partnership with Syngenta Group to integrate generative AI-powered agronomic intelligence for crop advisors and growers. In July 2025, Gamaya merged with Terraview to unlock new opportunities for sustainable food systems through AI-powered agronomic intelligence. These moves reflect a broader pattern: incumbents are increasingly acquiring, partnering, or collaborating to accelerate data network effects, expand application coverage, and reduce time-to-market for advanced agronomic capabilities.
Industry Dynamics, Regulation, and Infrastructure Realities
Market expansion is not occurring in a vacuum. Strategic planners must account for an evolving regulatory and operational environment that directly shapes deployment economics and adoption pacing. Public-sector frameworks are increasingly directing how AI is governed, standardized, and integrated into agricultural operations. The USDA Fiscal Year 2025–2026 AI Strategy mandates ethical, transparent, and accountable governance for AI deployment in agricultural operations, establishing expectations for data use, model accountability, and operational oversight. In parallel, the European Union Coordinated Plan on Artificial Intelligence includes targeted implementation progress for AI applications in precision agriculture and intelligent spraying, indicating heightened attention to compliance, environmental outcomes, and technology verification in mature regulatory markets.
Standardization efforts are also gaining traction. The AgML framework is working to standardize agricultural machine learning datasets and benchmarks for AI model development and evaluation, an initiative that should reduce fragmentation in training data quality and improve cross-platform comparability. For enterprise buyers and technology developers alike, these standardization and governance trends create both operational clarity and new compliance obligations. Organizations that build governance-ready architectures and auditable model workflows will face lower regulatory friction and stronger stakeholder trust as adoption scales.
Infrastructure and labor dynamics further define the practical boundaries of market growth. IoT sensors and solar-powered connectivity systems require significant upfront investment in farm-level data collection infrastructure for AI applications, meaning that deployment economics can vary sharply by operation size, connectivity availability, and capital access. At the same time, AI integration is increasingly positioned as a structural response to labor shortages, automating weed identification, spraying, and harvest operations through computer vision and robotics. This dual pressure—higher upfront infrastructure cost alongside labor cost mitigation—creates a nuanced investment calculus. Strategic decision-makers should evaluate AI adoption not solely on technology capability, but on total cost of ownership, infrastructure readiness, and the scalability of automation benefits across seasons and field conditions.
Strategic Priorities for 2026 Decision-Making
The 2026–2032 forecast window rewards organizations that align AI strategy with operational reality, data readiness, and ecosystem positioning. Several priority axes emerge for leadership teams evaluating market participation, investment, or capability development.
- Prioritize workflow-embedded AI over standalone analytics. Solutions that integrate directly into planting, spraying, irrigation, and harvest decisions are more likely to deliver measurable return and stickier adoption.
- Assess infrastructure readiness before scaling deployment. Farm-level connectivity, sensor coverage, and data ingestion capacity will determine whether AI initiatives translate into repeated operational gains or remain constrained pilot programs.
- Monitor partnership and consolidation signals. The mix of startup collaboration programs, platform partnerships, and mergers indicates that capability gaps are increasingly being closed through ecosystem alliances rather than internal build-only strategies.
- Embed governance and data standards early. With regulatory expectations rising and dataset standardization advancing, organizations that adopt transparent, auditable AI practices will be better positioned for cross-market expansion and partner integration.
- Evaluate concentration risk and differentiation opportunities. While leading platforms hold meaningful share, the market remains open to specialized solutions in imaging, irrigation intelligence, livestock monitoring, and agronomic advisory. Targeted differentiation can create defensible positions even in a fast-scaling market.
How to Use This Intelligence
This overview is designed to establish the strategic frame for deeper operational planning. It highlights the direction of market growth, the structure of competition, and the regulatory and infrastructure realities that shape deployment outcomes. However, actionable market entry, investment allocation, and capability planning require granular segmentation, use-case-level revenue splits, regional deployment differentials, and competitive benchmarking that exceeds the scope of a high-level briefing.
For organizations that need precise allocation models, segment-level growth decomposition, application-specific adoption curves, and detailed competitor capability mapping, the complete market research report provides the structured intelligence necessary to convert strategic direction into executable plans. The full analysis isolates the segments, regions, and deployment models that matter most to your operating context, enabling decision-makers to move from directional confidence to specific, data-backed action.
Closing Perspective
The AI in Agriculture market has entered a phase where technological promise is being converted into operational impact at scale. The combination of sustained double-digit growth, expanding platform ecosystems, and intensifying competitive collaboration suggests that the decisive question for 2026 is no longer whether AI will reshape agricultural operations, but how quickly organizations can integrate it into the economics of production. Leaders who align strategy with workflow reality, data infrastructure, and governance readiness will be best positioned to capture value as the market advances toward 2032.
For detailed analysis of this topic, please visit the official page: Artificial Intelligence (AI) in Agriculture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


