



PW Consulting: Cast Film Market to Reach $14.47B by 2032, 4.5% CAGR Amid Food Packaging Demand

Strategic Imperatives in the Cast Film Market: Navigating Growth and Complexity Through 2032
The global cast film market stands at a critical juncture where material science, regulatory pressure, and sustainability mandates converge. For strategic planners and category leaders, understanding the trajectory of this sector is no longer optional. It is a prerequisite for resilient supply chain design, product portfolio optimization, and long-term competitive positioning. Our latest comprehensive study on the Cast Film Market translates years of historical performance and forward-looking modeling into an executable intelligence framework. This article outlines the structural forces shaping the industry, highlights the operational content embedded in the full report, and demonstrates how executives can leverage these insights to de-risk decisions across the 2026 to 2032 horizon.
Market Trajectory and the Momentum Behind Sustained Expansion
Over the past five years, the cast film sector has demonstrated consistent upward movement, underpinned by expanding packaging demand, continuous extrusion technology improvements, and the material's inherent versatility across food, pharmaceutical, agricultural, and industrial applications. Historical revenue patterns from 2020 through 2025 reflect a steady climb, with the market surpassing the nine-figure million threshold and closing the base year at a level that signals durable commercial relevance. The forward projection reinforces this trajectory. Our forecast modeling indicates that the global market will continue its measured expansion through 2032, supported by volume growth, product innovation, and the gradual penetration of advanced mono-material structures. The compound annual growth rate anchored at 4.5 percent reflects a market that is neither overheated nor stagnant, but rather evolving at a pace that rewards organizations capable of aligning production capacity, feedstock strategy, and downstream application development with shifting end-user requirements.
For decision-makers, this growth profile carries nuanced implications. A mid-single-digit expansion rate suggests that headline market size alone will not differentiate winners. Instead, margin capture, application-level specialization, and regional execution precision will determine which participants convert industry-wide growth into outsized financial returns. The full research deliverable dissects these dynamics across multiple analytical lenses, allowing clients to isolate high-conviction opportunities without getting lost in aggregate figures that mask structural variation.
Segmentation Architecture and Where Strategic Value Actually Resides
Cast film demand does not move uniformly. The market is inherently multi-dimensional, shaped by resin chemistry, end-use performance specifications, and geographic manufacturing footprints. Understanding how these layers interact is essential for capacity planning, pricing strategy, and customer targeting. The study examines the primary segmentation axes that matter most to commercial and operational leaders, focusing on how resin categories, application verticals, and regional ecosystems each present distinct risk-return profiles.
On the material side, polyethylene-based structures continue to anchor a substantial portion of industry volume, reflecting their balanced mechanical properties, processability, and cost competitiveness across broad packaging formats. Polypropylene variants serve a strategically important but more specialized slice of the market, often favored where flexural strength, thermal stability, or specific barrier characteristics are prioritized. Polyester-based cast films occupy a narrower but high-performance niche, typically linked to demanding graphics, labeling, and specialty conversion environments. Rather than treating these categories as static share buckets, the report evaluates how resin selection is increasingly driven by downstream regulatory compliance, recyclability objectives, and converter-level processing economics.
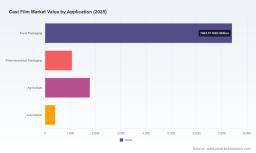
Application-level analysis reveals equally important divergence. Food packaging remains the dominant demand engine, shaped by freshness preservation, print fidelity, and stringent safety standards. Pharmaceutical packaging introduces a different calculus, where consistency, traceability, and regulatory alignment take precedence over pure cost optimization. Agricultural uses add complexity through exposure conditions, durability requirements, and seasonal demand cycles. Automotive and industrial applications, while smaller in aggregate volume, often function as high-specification adoption pathways that influence broader material innovation. The report maps these application environments to operational implications, helping clients anticipate where technical service, qualification lead times, and supply reliability will matter more than price alone.
Geographic dispersion further complicates the picture. Demand concentration varies by manufacturing maturity, export orientation, packaging infrastructure investment, and regional sustainability policy tempo. Instead of presenting narrow regional breakdowns that can obscure strategic context, the study evaluates how macro-regional demand patterns interact with local compliance frameworks, logistics constraints, and competitive density. This approach allows executives to assess where near-term volume growth is most likely to materialize and where longer-term positioning requires patience, partnership, or localized product adaptation.
What the Full Report Delivers Beyond Top-Line Figures
Aggregated market size and growth rates are only the starting point. The research is built around an operational architecture designed to support real decision-making. Inside the full study, clients gain access to a structured set of analysis modules that connect market behavior to executable strategy. The report incorporates:
- A multi-year historical reconstruction that validates trend assumptions and isolates structural shifts from cyclical noise
- Forward-looking demand modeling through the end of the decade, with scenario-aware forecasts that account for feedstock volatility, regulatory acceleration, and technology adoption pacing
- Application-specific demand logic that explains why certain verticals expand faster, resist downturns more effectively, or respond differently to material substitution
- Resin and processing-technology assessments that clarify the commercial relevance of downgauging, mono-material transition, and high-performance extrusion advances
- Competitive profiling that evaluates participant positioning across material supply, film conversion, equipment provision, and specialty application expertise
- Regulatory and compliance mapping that ties policy developments to substrate selection, recycled content requirements, and converter-level risk exposure
- Strategic implication summaries that translate data patterns into capacity, procurement, partnership, and go-to-market recommendations
This structure is intentionally designed to avoid the common trap of presenting data without decision context. Each section is linked to practical questions facing production leaders, procurement teams, R&D groups, and commercial strategists. The objective is to help organizations move from awareness to action, whether that means adjusting resin procurement timing, prioritizing regional expansion,qualifying new mono-material formats, or repositioning product offerings around recyclability and performance.
Competitive Landscape: Diversification of Capability and the Rise of Ecosystem Play
The cast film environment is not defined by a single business model. Instead, it comprises a blend of film converters, resin suppliers, extrusion-technology providers, and specialty solution developers. This diversity matters because competitive advantage increasingly depends on how well an organization can integrate upstream material capability with downstream application performance and regulatory alignment.
Several established participants illustrate the range of strategic postures now shaping the market. Avery Dennison operates with a strong orientation toward professional-grade cast films serving graphics and labeling applications, where print reliability, conformance, and converter usability are central to product value. Profol Group is recognized for custom cast film manufacturing across polypropylene and polyethylene formats, reflecting a conversion-focused model that emphasizes specification flexibility and customer-specific film design. Windmöller & Hölscher contributes from the equipment and process side, producing high-speed cast film extrusion lines and supporting CPP cast film production, which positions the company as an enabler of capacity and throughput improvements across the value chain. SML extends this technology-driven logic further, specializing in high-performance cast film extrusion technology and MDO-PE cast films, where dimensional performance and process efficiency are closely intertwined.
Material suppliers add another critical layer. TotalEnergies provides polymers that support downgauging initiatives for MDO-PE cast films, linking resin development directly to lightweighting and material efficiency objectives. LyondellBasell develops and supplies resins tailored to cast film grades, reinforcing the importance of feedstock-level innovation in achieving targeted mechanical and processing outcomes. Amcor rounds out the landscape as a manufacturer and supplier of cast films for packaging applications, combining conversion capability with broad commercial reach across end-use sectors.
The strategic lesson is clear: competitiveness is increasingly multidimensional. A company may compete on specification customization, extrusion efficiency, resin innovation, or application-oriented service. The full report maps these postures against market demand patterns, enabling clients to identify where partnerships, vertical alignment, or product portfolio adjustments can create defensible positioning.
Recent Innovation Signals and What They Reveal About Market Direction
Recent product activity confirms that the industry is moving toward thinner structures, improved material efficiency, and digitally enabled application formats. These developments are not isolated launches; they reflect a broader shift in how performance, sustainability, and processing economics are being optimized simultaneously.
TotalEnergies and SML collaborated on the development of two innovative downgauging films, including an unlaminated MDO-PE cast film designed for deep-freeze bags with a 35 to 50 percent thickness reduction. This kind of advancement illustrates how resin and technology alignment can deliver measurable material savings without sacrificing functional performance, a theme that will likely intensify as cost pressure and sustainability expectations rise together.
Avery Dennison reinforced the graphics and labeling trajectory by launching MPI 1903, a professional-grade cast film developed for digitally printable applications. This move highlights the growing importance of print compatibility, workflow integration, and specification reliability in higher-value conversion environments.
Amcor introduced Stratos cast film for ultra-lightweight packaging solutions, underscoring the continued emphasis on material efficiency and packaging optimization. Taken together, these developments suggest that the market's next phase of value creation will come less from raw volume expansion and more from engineered improvements that reduce material input, enhance processing performance, and satisfy evolving application requirements.
Industry Dynamics: Raw Material Pressure, Regulatory Acceleration, and Structural Reorientation
No strategic assessment of the cast film market is complete without addressing the external forces that can reshape margins, product design, and procurement timing. Two interlinked dynamics are particularly consequential in the current environment.
First, raw material volatility has become a defining operational challenge. Polypropylene prices rose 34 percent year-to-date through April 2026, driven by feedstock shortages and crude oil and naphtha volatility. For cast film producers and converters, this level of input fluctuation affects cost structures, pricing negotiations, inventory strategy, and product mix decisions. Organizations that rely on rigid procurement models or single-resin dependence face heightened exposure. The study examines how material price sensitivity interacts with application economics and identifies where feedstock diversification, hedging discipline, and product engineering can mitigate risk.
Cast Film Market
Second, regulatory and sustainability frameworks are actively restructuring demand logic. The EU Green Deal and single-use plastic reduction mandates are driving demand for recyclable mono-material cast films, shifting attention away from multi-layer complexity toward structures that are easier to recover and reprocess. At the same time, Extended Producer Responsibility schemes in Europe are requiring higher recycled content in cast films, placing additional pressure on material sourcing, quality consistency, and compliance documentation. REACH chemical restrictions are also tightening substrate compliance for cast film converters, adding another layer of technical and administrative scrutiny.
These forces are not separate noise; they are converging into a structural reorientation of the market. Recyclability, recycled content, chemical compliance, and material efficiency are increasingly embedded in purchasing criteria and product qualification processes. Companies that treat sustainability as a peripheral initiative risk losing relevance in segments where compliance and circularity are becoming commercial gatekeepers. The report integrates these dynamics into the forecast narrative and competitive analysis, ensuring that strategic recommendations reflect the regulatory reality facing the industry.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle requires more than retrospective review. It demands forward visibility into where demand will intensify, which material transitions will accelerate, how regulatory pressures will alter qualification cycles, and where competitive differentiation will be won or lost. The Cast Film Market study is built to support that moment of decision. It provides a calibrated view of market size evolution, segmentation behavior, technology relevance, and competitive positioning, while intentionally preserving room for scenario-based interpretation rather than fixed predictions.
For executives, the practical value lies in connection. The research links macro trends to segment-level logic, connects innovation signals to commercial outcomes, and translates raw material volatility and regulatory change into operational implications. Whether the objective is to evaluate capacity expansion, optimize resin sourcing, prioritize application development, or refine regional market entry, the study is designed to reduce ambiguity and sharpen resource allocation.
Casters Market
To access the complete segmentation detail, competitive profiles, forecast tables, regulatory mapping, and strategic recommendation sets, readers are encouraged to explore the full report. The aggregate trends outlined here establish the strategic frame; the full research delivers the execution-level intelligence required to act on it with confidence.
For detailed analysis of this topic, please visit the official page: Cast Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


