



PW Consulting: Commercial Payment Cards Market to Hit $364.76B by 2032, Growing at 6.98% CAGR

Navigating the Next Wave: Strategic Insights from the Commercial Payment Cards Market Research 2026
The landscape of corporate spending is undergoing a seismic shift. As businesses grapple with inflationary pressures, evolving regulatory frameworks, and the demand for seamless digital integration, the commercial payment card sector has emerged as a critical lever for operational efficiency. For decision-makers navigating the fiscal calendar of 2026, understanding the trajectory of this market is not merely an academic exercise—it is a strategic imperative. PW Consulting is proud to unveil our latest comprehensive market research, designed to equip leaders with the intelligence needed to capitalize on growth opportunities and mitigate emerging risks in the commercial payment ecosystem.
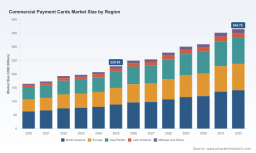
This research is anchored in rigorous data analysis covering historical performance from 2020 through 2025 and extending robust forecasts through 2032. The macro-environment presents a compelling story of resilience and expansion. In 2025, the global revenue for commercial payment cards reached approximately 229.05 billion USD. Looking ahead, the market is projected to climb to 249.66 billion USD in 2026, marking a significant inflection point in corporate adoption rates. Our forecast models indicate a steady compound annual growth rate of 6.98 percent throughout the forecast period, with revenues expected to surpass 364.76 billion USD by 2032. These figures underscore a sustained appetite for flexible payment instruments that bridge the gap between traditional corporate treasury functions and modern procurement needs.
Decoding Market Concentration and Competitive Forces
One of the most critical aspects of our analysis focuses on the competitive dynamics that define the industry. The market is characterized by a moderate level of concentration, where strategic positioning among top-tier players dictates the pace of innovation. Our report details a landscape where the top three companies command a combined market share of roughly 49.5 percent, while the top five entities control approximately 62.8 percent of the revenue pool. This structure suggests that while dominant networks hold significant sway, there remains substantial room for specialized issuers and niche providers to carve out profitable segments.
Plastic Cards Market
The competitive arena is populated by a diverse mix of global network operators and specialized issuers. Giants like American Express, Visa, and Mastercard continue to dominate the infrastructure layer, offering robust networks that support virtual purchase cards and corporate spend management solutions. American Express, headquartered in New York, remains a key player in issuing commercial payment cards including virtual purchase cards for business-to-business procurement. Similarly, Visa, based in San Francisco, operates a global network supporting commercial payment cards including virtual cards for corporate spend management, while Mastercard, located in Purchase, NY, provides network infrastructure with a focus on virtual and single-use variants for B2B transactions.
However, the ecosystem extends far beyond these primary networks. Discover Financial Services, based in Riverwoods, IL, issues commercial payment cards for business expense tracking and virtual solutions, catering to specific expense management needs. International reach is exemplified by JCB in Tokyo and UnionPay in Beijing, the latter facilitating commercial payment cards with contactless and virtual options to support cross-border commerce. On the specialized issuer front, companies like WEX in Minneapolis provide commercial fleet and virtual payment cards for business expenses, whereas Corpay in Nashville issues and manages commercial payment cards for corporate travel and expense programs.
Innovation is also being driven by agile entrants and standards bodies. Engine, based in Denver, recently made waves with the launch of the Engine X Visa-branded corporate charge card specifically for small and mid-sized businesses. This product features spending controls and travel rewards, directly addressing the needs of the SMB segment which often feels overlooked by larger issuers. Furthermore, standards development plays a crucial role in interoperability and security. X9, the standards body in Annapolis, MD, developed and published X9.149 for single-use virtual business-to-business payment cards, aiming to streamline transaction efficiency.
Recent Developments Shaping the 2026 Landscape
Real-time intelligence is vital in a sector moving this fast. Our research integrates the latest developments that are actively reshaping the value proposition for corporate clients. In March 2026, Engine announced the launch of their corporate charge card, featuring spending limits, merchant restrictions, and up to 10 percent rewards on business travel. This move highlights a trend toward incentivizing specific spending categories while maintaining strict control parameters, a balance that many finance teams are seeking.
Simultaneously, the regulatory and standards environment is tightening to support higher efficiency and security. In April 2026, the Accredited Standards Committee X9 published the X9.149 standard for single-use virtual purchase card payment automation. This development is designed to improve B2B transaction efficiency and reconciliation following ISO 20022 messaging standards. Such standardization efforts are critical for reducing friction in accounts payable processes and enhancing the auditability of corporate spending.
Beyond specific product launches, broader industry dynamics are influencing market behavior. The Federal Reserve Board reported on average debit card interchange fees by payment card network in December 2025, providing essential data for cost-benefit analyses of different card programs. Security remains paramount, with the PCI DSS Card Production and Provisioning Physical and Logical Security Requirements defining standards for card manufacturing, transport, and personalization. Additionally, the Payment Card Industry Data Security Standard version 4.0 guides organizations on card data handling and compliance, a critical consideration for any firm integrating payment cards into their IT infrastructure.
Infrastructure costs also play a background role in the economics of payment processing. The American Society of Civil Engineers 2025 Infrastructure Report Card noted that deployment costs for broadband infrastructure increased over 10 percent with materials and labor as primary drivers. While this relates to physical infrastructure, it impacts the broader digital ecosystem supporting payment technologies. Furthermore, macro-level shifts are occurring, as highlighted by the McKinsey Global Payments Report in September 2025, which pointed to growing payment sovereignty initiatives in regions such as Europe and Brazil to reduce reliance on global intermediaries. This trend could influence network selection and localization strategies for multinational corporations.
Segmentation Dynamics and Application Scenarios
Understanding where the revenue is generated is key to allocating resources effectively. Our research delves deep into the segmentation of the market by type and application, revealing distinct growth drivers within each category. The market is segmented by type into Credit Cards, Debit Cards, and Prepaid Cards. Credit cards continue to hold a substantial portion of the market value, reflecting their utility in managing cash flow and earning rewards, while Debit Cards offer a controlled spending mechanism linked directly to funds. Prepaid Cards also represent a significant segment, often utilized for specific budgeting purposes or employee allowances.
From an application perspective, the divide between Large Business Cards and Small Business Cards illustrates the diverse needs across the corporate spectrum. Large Business Cards constitute a major share of the application market, driven by high-volume procurement and complex travel requirements. Small Business Cards, while representing a smaller total revenue share compared to the enterprise segment, are witnessing heightened innovation and competitive pressure from issuers like Engine looking to capture the SME market. Our report provides granular analysis of how these segments interact with regional dynamics and type preferences without exposing the specific numerical splits that constitute our core proprietary intelligence.
Geographic distribution also plays a pivotal role in strategy formulation. The market serves key regions including North America, Europe, Asia Pacific, Latin America, and Mideast and Africa. Each region presents unique regulatory environments, adoption rates, and competitive intensities. For instance, payment sovereignty trends may impact strategies in Europe and Latin America differently than in North America. Our analysis contextualizes these regional variations to help clients prioritize market entry or expansion efforts based on their specific risk tolerance and growth objectives.
The Strategic Value of Comprehensive Intelligence
Why does this level of detail matter for your 2026 planning? In a market projected to grow by over 130 billion USD between 2026 and 2032, the margin for error shrinks as competition intensifies. Access to detailed segmentation data, competitive profiling, and regulatory roadmaps allows organizations to move from reactive spending management to proactive financial strategy. Whether you are a issuer looking to refine your product portfolio, a corporate treasurer optimizing expense policies, or an investor assessing the viability of fintech ventures in the payments space, this report provides the foundational knowledge required to make informed decisions.
The report goes beyond high-level numbers to explore the operational realities faced by market participants. It examines how reimbursement dynamics, influenced by factors such as interchange fee structures, affect the total cost of ownership for corporate card programs. It also assesses how compliance with evolving security standards impacts procurement timelines and vendor selection. By synthesizing data on market concentration, company profiles, and recent developments, we offer a 360-degree view of the ecosystem.
Our analysis of key companies includes detailed profiles covering their headquarters, operational focus, and strategic moves. For example, understanding the focus of WEX on fleet and virtual payment cards versus Corpay's emphasis on corporate travel and expense programs helps tailor partnership or benchmarking strategies. Similarly, tracking the standardization efforts of bodies like X9 ensures that technology investments align with future-proof protocols.
Commercial Payment Cards Market
Unlock the Full Intelligence
The insights summarized here represent only the surface of the comprehensive intelligence available in the full PW Consulting Commercial Payment Cards Market Research. To truly leverage the 6.98 percent CAGR opportunity and navigate the complexities of a market reaching 364.76 billion USD by 2032, decision-makers need access to the complete dataset, detailed forecasts, and proprietary analytical models.
We invite you to access the source webpage to download the full report. There you will find the specific regional growth rates, detailed application segment valuations, and deep-dive competitive benchmarking that cannot be fully disclosed in this overview. Equip your team with the precise data needed to outperform in the evolving commercial payment landscape. Visit our report page today to secure your copy and start transforming market intelligence into strategic advantage.
For detailed analysis of this topic, please visit the official page: Commercial Payment Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


