



PW Consulting: Medical Ultrasonic Cleaners Market to Hit $1.98B by 2032, 6.8% CAGR

Strategic Imperatives in the Medical Ultrasonic Cleaners Market 2026-2032: A Executive Outlook
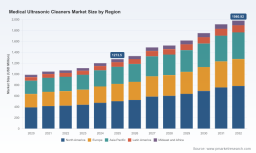
The global medical ultrasonic cleaners market stands at a critical inflection point as healthcare infrastructure modernization, stringent infection control mandates, and evolving regulatory frameworks reshape equipment procurement cycles. Over the 2026–2032 forecast horizon, the sector is projected to advance at a compound annual growth rate of 6.8 percent, translating into a trajectory from 1331.54 million USD in 2026 to 1980.92 million USD by 2032. This sustained expansion is not merely a function of volume replacement; it reflects a structural revaluation of decontamination workflows within sterile processing departments, operating rooms, and centralized instrument reprocessing facilities. For executives navigating medical device manufacturing, healthcare operations, or sterile supply chain management, the current market phase demands more than incremental procurement adjustments. It requires a disciplined, data-informed approach to technology adoption, regional deployment, and competitive positioning. Our newly released Medical Ultrasonic Cleaners Market research delivers precisely that analytical infrastructure, translating macro momentum into actionable enterprise strategy.
Market Trajectory and the 2026 Investment Thesis
Growth in the ultrasonic cleaning sector has accelerated decisively since 2020, when the market was valued at 987.65 million USD. By 2025, revenue had climbed to 1273.5 million USD, reflecting a compound expansion of roughly 6 percent annually across the historical record. The forecast period extends this momentum, with revenue projected to cross 1524.59 million USD in 2028, 1751.76 million USD in 2030, and 1913.12 million USD in 2031, before stabilizing at 1980.92 million USD in 2032. This trajectory is underpinned by three converging forces: the replacement of legacy manual decontamination protocols, the integration of ultrasonic technology into automated reprocessing lines, and the growing recognition of ultrasonic cavitation as a repeatable, validated method for contaminant removal on complex surgical and dental instrument geometries.
Medical Desktop Ultrasonic Equipment Market
For 2026 strategic planning, the most salient implication is that volume growth is increasingly tied to capability upgrades rather than baseline installation counts. Healthcare networks are reassessing capital expenditure priorities in light of labor constraints, throughput bottlenecks, and compliance documentation requirements. Ultrasonic systems that deliver programmable cycles, reproducible rinse profiles, and digital validation outputs are transitioning from optional enhancements to operational necessities. The research emphasizes that organizations which anchor their 2026 procurement roadmaps to process standardization, instrument throughput targets, and total cost of ownership modeling will capture disproportionate efficiency gains relative to peers pursuing ad hoc equipment rotation.
Core Report Architecture: From Data Layers to Decision Frameworks
The study is structured to support multi-functional decision-making across procurement, clinical operations, regulatory affairs, and market development. Rather than presenting isolated statistics, the analysis integrates demand-side drivers, supply-side capacity signals, and operational benchmarks into a cohesive planning environment. Key analytical modules include:
- Demand driver mapping across surgical, dental, laboratory, and medical device reprocessing workflows, with emphasis on throughput requirements, cycle validation expectations, and decontamination chain integration points.
- Product configuration analysis that distinguishes between benchtop, industrial, and specialized formats, linking tank capacity, frequency stability, and control architecture to use-case suitability and procurement risk.
- Regional deployment intelligence that evaluates healthcare spending patterns, manufacturing footprint expansion, and localized compliance expectations across major economic corridors without isolating granular share percentages.
- Competitive benchmarking that profiles product positioning, recent commercial moves, and strategic intent across the leading participants shaping category standards.
- Scenario-based modeling that allows leadership teams to test procurement timing, capacity expansion, and partnership strategies against shifting regulatory and reimbursement conditions.
This architecture is designed for execution. Procurement leaders can calibrate specification thresholds against validated deployment patterns. Clinical operations teams can align decontamination workflows with cycle reproducibility and purity expectations. Commercial teams can identify account segments where digital control upgrades, modular reconfiguration, or eco-friendly agent compatibility directly influence purchasing velocity. The report deliberately refrains from over-disclosing sub-segment percentages and localized valuation breakdowns within this executive preview; those layers remain fully accessible in the complete intelligence package, where the granularity supports precise territory planning and product-mix optimization.
Competitive Architecture and Strategic Orbital Moves
The competitive field is moderately concentrated, with the top three firms accounting for approximately 28.5 percent of category revenue and the top five expanding that footprint to roughly 35.2 percent. This concentration signals a market where scale, application specialization, and compliance readiness increasingly separate leaders from followers. Several manufacturers have moved aggressively to reinforce their positions through targeted product evolution, partnership formation, and regulatory alignment.
Crest Ultrasonics, headquartered in Trenton, New Jersey, has sharpened its focus on precision cleaning for surgical and medical instruments through healthcare-oriented product lines such as the Healthcare Pro Junior series, which incorporates multi-cycle wash and rinse capabilities alongside digital controls tailored for sterile processing environments. In September 2025, the company entered a strategic partnership with a leading hospital network to deliver customized ultrasonic cleaning solutions, a move that underscores the growing preference for networked deployments aligned to institutional workflow specifications.
Elma Schmidbauer GmbH, based in Singen, Germany, continues to advance modular ultrasonic cleaning platforms and has introduced eco-friendly InnoWave PCF models designed to support medical device instrument reprocessing and decontamination under evolving medical device regulation expectations. In July 2025, the company unveiled an eco-friendly ultrasonic cleaner utilizing biodegradable cleaning agents for medical applications, highlighting an industry-wide shift toward agent compatibility, waste stream management, and environmental compliance within sterile decontamination processes. Regulatory documentation reinforces that Elma Schmidbauer medical ultrasonic cleaners are positioned for instrument reprocessing in medical technology applications, with ultrasound cleaning systems expected to provide reproducible processes and the highest purity standards in medical device manufacturing.
Branson Ultrasonics, operating from Danbury, Connecticut, has reinforced its emphasis on digital control sophistication for surgical instrument cleaning. In August 2025, the company announced a new line of ultrasonic cleaners specifically for surgical instruments, incorporating advanced digital controls intended to enhance cleaning efficiency and support validation workflows. This product direction aligns with broader operating-room and sterile processing priorities around cycle repeatability, documentation readiness, and reduced manual intervention.
Ultrasonic Power Corporation, based in New Britain, Connecticut, manufactures industrial and medical-grade ultrasonic cleaners for pharmaceutical and medical applications, including custom systems engineered for precision part cleaning. Ultrasonic LLC, also United States-based, supplies machines designed for medical parts cleaning, handling small batches and complex components across healthcare and aerospace-related requirements. Together, these participants reflect a diversifying supplier base in which application specificity, custom configuration capability, and regulatory awareness increasingly influence purchasing decisions.
For enterprise strategists, these competitive signals carry clear implications. Supplier selection is no longer a function of unit price alone; it incorporates validation readiness, cycle programmability, compliance support, and compatibility with institutional decontamination chains. Organizations that evaluate vendors through a multi-criteria scorecard encompassing traceability, digital output quality, service response, and upgrade pathways will be better positioned to lock in operational resilience as category standards tighten.
Operational, Regulatory, and Labor Economics Shaping Procurement Behavior
Beyond competitive dynamics, the market is being reshaped by operational realities that directly influence specification priorities. High-capacity stainless steel tank models in the 5-liter to 8-liter range have become standard in medical ultrasonic cleaners for instrument pre-cleaning, reflecting a broader shift toward throughput-compatible hardware that can process reusable instrument sets efficiently at the front end of decontamination workflows. This hardware normalization reduces variability in cycle execution while supporting consistent exposure of instrument surfaces to cavitation activity.
Labor economics are also accelerating adoption. Ultrasonic cleaners deliver measurable labor savings by replacing manual cleaning methods for surgical instruments in sterile processing departments. As staffing pressures persist and training consistency becomes a recognized operational risk, automated or semi-automated cleaning cycles offer a practical lever for reducing variability, reducing rework, and improving instrument readiness before sterilization. Reimbursement and compliance structures further reinforce this direction. In practice, instrument cleaning equipment used in healthcare settings must support decontamination prior to autoclaving, and systems that align with established healthcare standards are increasingly favored during procurement reviews and quality audits.
Regulatory context adds another layer of strategic relevance. Medical technology applications are subject to evolving expectations around documentation, process reproducibility, and validation traceability. Organizations are therefore placing greater weight on equipment that supports repeatable cycles, verifiable rinse outcomes, and integration into broader quality management systems. In this environment, procurement decisions are increasingly evaluated not just on cleaning performance in isolation, but on how effectively a system supports downstream compliance and sterilization readiness.
Medical Ultrasonic Cleaners Market
Strategic Playbook for 2026 Enterprise Decision-Makers
Translating these dynamics into executable strategy requires a structured approach. The research outlines several priorities that resonate across healthcare networks, medical device manufacturers, and equipment distributors:
- Define instrument reprocessing targets first, then map equipment specifications to those targets. Throughput, cycle flexibility, and validation output should be treated as interdependent decision variables rather than separate purchasing dimensions.
- Embed total cost of ownership analysis into capital planning. Upfront pricing comparisons should be supplemented with assessments of labor displacement, rework reduction, maintenance expectations, and compliance documentation value.
- Align supplier evaluation with future regulatory and environmental expectations. Preference should be given to platforms that accommodate standardized cycle programs, digital record generation, and compatibility with evolving cleaning agent requirements.
- Treat regional deployment as a strategic variable. Healthcare infrastructure maturity, manufacturing presence, and localized service capacity influence implementation timelines and long-term support reliability, making geography a relevant component of procurement planning.
- Use competitive intelligence to anticipate category direction. Recent product launches, partnerships, and eco-friendly innovations signal where specification expectations are heading, enabling earlier internal alignment and reduced procurement friction.
These priorities are not generic best practices; they are derived from the observed intersection of demand-side operational pressures, supplier innovation cadence, and regulatory reinforcement within the ultrasonic cleaning category. Organizations that operationalize them early in the 2026 planning cycle will have a clearer path to procurement efficiency, reduced implementation risk, and stronger alignment with downstream sterilization and quality requirements.
The Complete Intelligence Layer: What Is Held Back and Why
This executive overview is intentionally structured as a strategic preview. The purpose is to establish analytical credibility, demonstrate sector fluency, and clarify how the full report supports decision-making without dispersing the most granular intelligence across public-facing formats. Core segmentation values, regional revenue distributions, application-level breakdowns, and product-type splits remain embedded in the complete study, where they can be cross-referenced against operational benchmarks, competitive profiles, and scenario models without dilution. That architecture allows procurement and strategy teams to apply precise figures to territory planning, product-mix evaluation, and vendor comparison without exposing sensitive analytical layers prematurely.
In practice, the full report provides the quantitative scaffolding required to convert directional momentum into specific procurement, expansion, and partnership decisions. The macro trajectory, competitive positioning, regulatory context, and operational drivers presented here form the strategic foundation; the detailed segmentation and valuation layers supply the execution-level precision. Together, they create a planning environment that supports both short-term purchasing calibration and multi-year capability roadmapping.
Closing Perspective: Positioning for Measured, High-Value Growth
The medical ultrasonic cleaners market is advancing along a clearly defined growth path, but the strategic opportunity lies less in the headline numbers than in the operational and regulatory conditions that are reshaping procurement logic. As the category moves from 1331.54 million USD in 2026 toward nearly 1980.92 million USD in 2032, the organizations that win will be those that convert that momentum into disciplined specification choices, validated workflow integration, and supplier relationships aligned with compliance, reproducibility, and efficiency goals. The complete Medical Ultrasonic Cleaners Market research is built to support precisely that outcome, offering the depth, structure, and benchmarking context required to move from informed awareness to decisive execution.
For detailed analysis of this topic, please visit the official page: Medical Ultrasonic Cleaners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


