



PW Consulting: Diabetes Drugs Market to Hit $117.7B by 2032, 6.5% CAGR Amid GLP-1 Growth

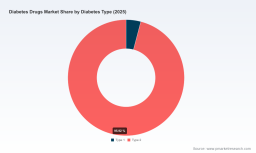
# The Diabetes Drugs Market in 2026: Navigating Growth, Innovation, and Strategic Complexity ## Executive Summary: Why Deep Intelligence Matters Now The global landscape for diabetes management is undergoing a seismic shift, driven by breakthrough therapies, evolving reimbursement models, and persistent supply chain vulnerabilities. For executives, investors, and strategic planners, relying on surface-level data is no longer sufficient. The decisions made in 2026 will dictate competitive positioning for the remainder of the decade. This article provides a high-level strategic overview of the market environment, illustrating the complexity and opportunity that define the sector today. However, true strategic advantage requires granular precision that goes beyond public headlines. Our comprehensive Diabetes Drugs Market research report delivers the specific segmentation volumes, competitive share analysis, and future trajectories necessary to optimize your portfolio and entry strategies. ## Market Trajectory and Scale: A Decade of Expansion The diabetes drugs market has demonstrated consistent resilience and growth over the past half-decade, establishing a robust foundation for the forecast period extending through 2032. Between 2020 and 2025, the market experienced significant expansion, with revenues rising from 51.0 billion USD to 75.9 billion USD. This historical performance underscores the inelastic demand for chronic care solutions and the rapid adoption of newer therapeutic classes. Looking forward, the market is projected to sustain a Compound Annual Growth Rate (CAGR) of 6.5 percent during the 2026 to 2032 forecast period. This trajectory suggests that the market will surpass the 100 billion USD milestone shortly after the turn of the decade, reaching approximately 117.7 billion USD by 2032. Such growth is not uniform; it is fueled by specific innovation waves and regional dynamics that require careful unpacking. While the top-line figures indicate a healthy sector, the distribution of this growth across drug classes, diabetes types, and geographic regions reveals critical niches where value is being created and captured. Understanding where the revenue streams are concentrating is vital for resource allocation, yet these specific breakdowns are detailed within our full proprietary dataset. ## The Innovation Engine: Drug Classes and Therapeutic Shifts The competitive battlefield is defined by the performance of distinct drug classes, each carrying different risk profiles, pricing power, and patient adherence rates. The market has seen a pronounced pivot toward incretin-based therapies, which have reshaped expectations for glycemic control and weight management. Conversely, traditional insulin markets remain foundational but face pressure from biosimilar competition and novel delivery mechanisms. Recent regulatory milestones highlight the pace of innovation. In March 2026, Novo Nordisk received FDA approval for Awiqli (insulin icodec-abae), a once-weekly insulin designed to improve glycemic control for type 2 diabetes. This approval represents a significant advancement in patient convenience and potentially adherence, disrupting the daily injection paradigm. Alongside such developments, the market landscape is being reshaped by key industry players who are leveraging distinct portfolios to capture share. Our report provides an in-depth profiling of the entities driving these changes. Leading manufacturers such as Novo Nordisk A/S, headquartered in Bagsværd, Denmark, continue to dominate with a strong lineup including Ozempic, Wegovy, and Rybelsus. Their strategy focuses heavily on the intersection of diabetes and obesity management. Similarly, Eli Lilly and Company, based in Indianapolis, Indiana, USA, is pushing the envelope with GLP-1 and GIP receptor agonists, including Mounjaro, Zepbound, and the investigational orforglipron, targeting both glycemic control and obesity-related metrics. Traditional insulin leaders remain relevant through formulation innovation. Sanofi, headquartered in Paris, France, maintains a strong presence with long-acting insulins like Lantus and Toujeo. Meanwhile, the SGLT2 inhibitor space is contested by developers like Boehringer Ingelheim, based in Ingelheim am Rhein, Germany, with products such as Jardiance, and Janssen Pharmaceuticals, located in Beerse, Belgium, offering Invokana for type 2 diabetes management. The interplay between these giants involves patent cliffs, pipeline Succession, and strategic partnerships that are meticulously analyzed in our full report to help you anticipate market share shifts. ## Geography and Patient Segmentation: Where the Revenue Lies Revenue distribution is not homogeneous across the globe. Certain regions exhibit higher purchasing power and faster adoption rates for premium therapies, while others offer volume growth potential driven by prevalence rates and improving healthcare infrastructure. The concentration of value in specific geographic zones creates distinct regulatory and pricing challenges for multinational strategies. Similarly, the patient base is segmented by diabetes type, with the vast majority of therapeutic spend directed toward Type 2 diabetes management, reflecting the global burden of metabolic syndrome. Type 1 diabetes, while smaller in terms of total revenue volume, represents a critical area for innovation in insulin delivery and immunosuppression therapies. The nuances of how these segments interact with drug class preferences—for instance, the preference for SGLT2 inhibitors in specific comorbidity profiles versus insulin dependence in advanced cases—require detailed modeling. Our research breaks down these segments to identify high-growth pockets that are often obscured in aggregate market figures. Access to the full segmentation data allows stakeholders to pinpoint exactly where their products fit within the current hierarchy of treatment guidelines. ## Market Concentration and Competitive Intensity The diabetes drugs market is characterized by a moderate level of concentration, suggesting room for niche players while maintaining strong barriers to entry for complex biologics and patented formulations. The top three companies hold a significant portion of the market share, collectively accounting for approximately 50 percent of revenue. Expanding the view to the top five players, the concentration rises to 65 percent. This structure indicates a market dominated by well-capitalized incumbents with extensive distribution networks and regulatory expertise. However, concentration does not imply stagnation. The remaining 35 percent of the market is highly competitive, with opportunities arising from generic entry, biosimilar development, and novel mechanisms of action. Strategic decisions regarding M&A, licensing, or organic pipeline development must account for this concentration risk. Entering a market segment dominated by the top five requires a differentiated value proposition, whether through superior clinical outcomes, cost efficiency, or delivery convenience. Our competitive landscape analysis dives deeper into the strategic moves of these key players, evaluating their R&D pipelines, litigation status, and global expansion strategies to provide a clear picture of the barriers and opportunities ahead. ## Supply Chain and Regulatory Dynamics: Navigating Risk in 2026 Beyond the clinical data and revenue projections, the operational environment for diabetes drugs is fraught with logistical and regulatory complexities. Supply chain resilience has emerged as a critical strategic pillar, particularly concerning the sourcing of key starting materials and active pharmaceutical ingredients (APIs). Recent analysis by the United States Pharmacopeia (USP) highlights a significant vulnerability: nearly half (48 percent) of key starting materials for drugs on the USP vulnerable medicines list are solely manufactured in a single country. This concentration poses acute and chronic risks to the supply of diabetes medications should disruptions occur. Furthermore, the USP emphasizes that upstream starting material sourcing bottlenecks could impact the availability of essential medicines. In the context of raw materials, 48 percent of global API Drug Master Files (DMFs) originate from India. This heavy reliance underscores the need for diversified sourcing strategies and robust contingency planning. Regulatory and reimbursement landscapes are also shifting dynamically. The Centers for Medicare & Medicaid Services (CMS) has introduced the GLP-1 Bridge model, providing access at a $50 copay for eligible Medicare beneficiaries with standardized coverage criteria. Additionally, the Medicare GLP-1 Bridge program offers eligible Part D beneficiaries $50 monthly access to certain GLP-1 medications beginning July 1, 2026. These initiatives are designed to improve patient access but introduce new variables for pricing strategy and demand forecasting. Stakeholders must understand how these reimbursement changes affect volume projections and manufacturer rebates. Our report synthesizes these regulatory developments with market demand models to predict how policy shifts will alter consumption patterns and profitability across different payer segments. ## Strategic Implications for Industry Stakeholders The convergence of robust market growth, therapeutic innovation, and supply chain fragility creates a complex decision matrix for 2026. Manufacturers must balance the urgency of launching new formulations against the risk of supply disruptions. Investors need to discern which drug classes will sustain premium pricing versus those facing imminent generic erosion. Policymakers and payers are grappling with the cost implications of widespread GLP-1 adoption while trying to expand access. To navigate this environment, organizations require more than just top-line growth numbers. They need a granular understanding of how segmentation splits interact with regional regulations, how competitive concentration affects pricing power, and how supply chain dependencies impact product availability. The data provided in public summaries often lacks the depth required to model these scenarios accurately. For instance, knowing the overall market size is useful, but understanding the specific revenue contribution of SGLT2 inhibitors versus GLP-1 receptor agonists in North America versus Asia Pacific is essential for regional market entry or expansion plans. ## Conclusion: The Value of Granular Intelligence The diabetes drugs market is poised for significant expansion through 2032, driven by a CAGR of 6.5 percent and evolving therapeutic standards. However, realizing value in this market requires precise intelligence. The interplay between major pharmaceutical players, regional demand variations, drug class performance, and regulatory policies creates a landscape where general knowledge is insufficient for competitive advantage. Our comprehensive Diabetes Drugs Market research report goes beyond the macro trends to provide the detailed segmentation data, competitive profiles, and strategic analysis necessary for informed decision-making. By uncovering the specific revenue splits, concentration metrics, and dynamic risk factors, this report equips stakeholders to mitigate risk and capitalize on growth opportunities with confidence. We invite you to explore the full findings to gain the actionable insights needed to thrive in this evolving sector.
Diabetes Drugs Market
Fertility Drugs Market
For detailed analysis of this topic, please visit the official page: Diabetes Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


