



PW Consulting: PVDF Market Hits $1.37B in 2025, Surging to $2.48B by 2032 on 8.8% CAGR

Strategic Intelligence for the Polyvinylidene Difluoride Market 2026-2032
As global industries navigate a period of rapid technological transition, supply chain recalibration, and evolving regulatory landscapes, Polyvinylidene Difluoride (PVDF) has emerged as a critical enabler across energy storage, advanced chemical processing, and high-performance filtration. For executives, supply chain leaders, and R&D directors, understanding where this market is headed is no longer optional—it is foundational to capital allocation, capacity planning, and competitive positioning. Our latest comprehensive research delivers the strategic intelligence required to make informed decisions in 2026 and beyond.
Over the past half-decade, the PVDF sector has demonstrated remarkable momentum, driven by expanding demand from lithium-ion battery manufacturing, next-generation water treatment infrastructure, and specialized high-purity coatings. Historical trajectory data reveals a clear upward arc: the market generated approximately 800 million USD in 2020, gradually climbed past the 920 million USD threshold in 2022, crossed the 1,200 million USD milestone by 2024, and reached an estimated 1,372 million USD by 2025. This established baseline sets the stage for what analysts project will be a sustained growth phase. Looking ahead to the 2026-2032 forecast window, the market is expected to scale from roughly 1,497 million USD in 2026 toward nearly 2,479 million USD by the close of the decade. This trajectory translates to a compound annual growth rate of 8.8 percent, positioning PVDF as one of the most structurally resilient specialty polymer segments in the broader advanced materials landscape.
For enterprise leaders, these figures are more than retrospective benchmarks—they are strategic signals. An accelerating growth rate of this magnitude implies tightening supply-demand balances, heightened competition for qualified raw material streams, and an urgent need to secure reliable downstream partnerships before capacity constraints or pricing volatility erode margins. Companies that approach 2026 without a clear view of regional demand nodes, application-specific consumption patterns, and evolving cost structures risk reactive decision-making in a market that rewards foresight.
Decoding the Operating Environment: Dynamics Shaping 2026
No market strategy is complete without a granular understanding of the operational forces currently reshaping PVDF supply chains. Several intersecting dynamics are already influencing production economics and demand trajectories, and their cumulative impact will define competitive outcomes throughout the forecast period.
On the raw material front, the sector has faced notable supply pressure. A pronounced shortage of hydrogen fluoride during the second quarter of 2025 forced approximately ten percent production cuts across several Chinese PVDF plants, triggering a rapid elevation in global spot prices. Compounding this vulnerability is the broader chemical input environment: a twelve-fold surge in R-142B pricing between 2023 and 2024 pushed PVDF production costs upward by 18 to 25 percent, disproportionately squeezing smaller manufacturers with thinner balance sheets. Adding another layer of structural complexity, China currently controls over three-quarters of global VDF production capacity. Recent environmental clampdowns in Jiangsu and Shandong provinces have already driven 10 to 12 percent cost spikes on a quarter-on-quarter basis, underscoring how tightly coupled regional compliance enforcement is with global cost curves.
Simultaneously, regulatory evolution is introducing profound uncertainty and opportunity. Europe has moved closer to a potential blanket restriction on PVDF membranes following an updated dossier from the European Chemicals Agency (ECHA) that explores banning the manufacture of all per- and polyfluoroalkyl (PFAS) substances. While the final scope and timeline remain under active review, the mere trajectory of this regulatory conversation is already prompting downstream adopters to re-evaluate supplier diversification, material substitution pathways, and long-term procurement commitments. In markets where compliance timelines intersect with capital-intensive production cycles, anticipating regulatory inflection points is a decisive competitive advantage.
The strategic takeaway is clear: cost volatility, regional capacity concentration, and evolving chemical regulations are not peripheral concerns. They are central to pricing strategy, supplier negotiations, and geographical expansion planning. Companies that map these dynamics to their specific operational footprints will be positioned to manage risk proactively rather than react to margin compression after the fact.
Polyvinylidene Fluoride (PVDF) (PVDF Resin) Market
Mapping Competitive Forces and Industry Structure
The PVDF market exhibits a moderately concentrated competitive structure, with the top three players collectively commanding approximately 55 percent of market share and the leading five firms extending their combined presence to roughly 65 percent. This concentration pattern reflects decades of technical specialization, established fluoropolymer processing expertise, and long-term relationships with high-specification end users. Yet the landscape is far from static. The remaining market share is distributed across a mix of regional specialists, application-focused innovators, and emerging capacity builders, all of whom are actively carving out positions through targeted product development and strategic manufacturing investments.
Several established multinational and regional players define the current industry architecture. Arkema S.A., headquartered in Colombes, France, has been actively strengthening its PVDF footprint, most notably through its Kynar brand. In March 2026, Arkema announced a 20 percent capacity expansion at its Changshu site in China, with startup scheduled for 2028. This expansion is explicitly designed to support surging demand across lithium-ion batteries, energy storage systems, high-performance coatings, chemical processing, semiconductors, water filtration, and wire and cable applications. Solvay S.A., based in Brussels, Belgium, maintains a differentiated position through its advanced specialty polymer portfolio, leveraging deep formulation expertise and global technical service networks. Kureha Corporation, situated in Tokyo, Japan, brings longstanding fluoropolymer engineering heritage and a strong presence in high-purity industrial applications. Daikin Industries, Ltd., also headquartered in Osaka, Japan, continues to invest in fluorine chemistry capabilities that underpin high-performance membrane and coating solutions. In China, Shanghai Huayi 3F New Materials Co., Ltd. and Shanghai Ofluorine Chemical Technology Co., Ltd. represent rapidly scaling domestic players that are expanding their technical portfolios and aligning closely with regional demand surges, particularly in energy storage and industrial processing. Rounding out the competitive set, 3M Company, based in St. Paul, Minnesota, United States, applies its broad materials science platform to specialized PVDF-enabled solutions across filtration, electronics, and industrial coatings.
Recent corporate activity underscores how aggressively incumbents are positioning for the next demand cycle. Capacity additions, formulation upgrades, and regional manufacturing investments are no longer isolated R&D projects—they are strategic infrastructure plays designed to lock in supply preference with high-growth end markets. Understanding the timing, scale, and geographic focus of these moves is essential for any organization evaluating partnership opportunities, assessing competitive exposure, or planning its own capacity strategy.
Inside the Research: What Decision-Makers Will Find
A market report of this scope must do more than chart growth curves. It must translate macro trends into operational intelligence that can be actioned across procurement, product development, sales strategy, and investment planning. Our analysis is structured to deliver precisely that bridge between high-level market intelligence and day-to-day strategic execution.
The research framework begins with a robust historical reconstruction spanning 2020 through 2025, establishing baseline consumption patterns, pricing behavior, and demand composition before projecting forward across the 2026-2032 window. From there, the analysis segments the market across multiple structural dimensions, allowing readers to isolate the specific demand drivers, application growth rates, and product-type dynamics that matter most to their business models. Rather than presenting a single aggregate number, the report unpacks how different segments reinforce or diverge from the overall growth trajectory, enabling executives to identify where capital deployment will yield the strongest returns and where latent demand risks may be underestimated.
Beyond segmentation, the publication delivers a comprehensive competitive mapping exercise. It profiles the operating strategies of key market participants, evaluates recent capacity and investment announcements, and contextualizes each player’s positioning relative to regional demand centers and technical differentiation. This competitive layer is paired with a supply chain and cost structure assessment that traces input dependencies, highlights vulnerability nodes, and identifies where margin pressure is most acute. Given the raw material sensitivity documented in recent quarters, this dimension alone can materially improve procurement negotiation leverage and inventory planning accuracy.
The regulatory and compliance landscape receives dedicated analytical treatment as well. With evolving chemical governance frameworks intersecting with long-lived infrastructure and capital equipment decisions, the report maps potential policy trajectories, evaluates downstream substitution feasibility, and outlines strategic response pathways. For organizations operating in or selling into European markets, or for those dependent on PVDF-enabled membranes and coatings in regulated environments, this section provides a structured view of compliance risk rather than speculative headlines.
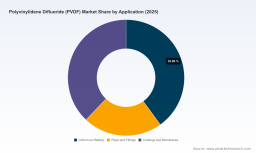
Finally, the research integrates demand-side application intelligence across energy storage, industrial piping and fittings, advanced coatings and membranes, and other high-value use cases. By connecting application growth signals to regional manufacturing footprints, raw material availability, and competitor capacity timelines, the report equips strategy teams to answer a far more valuable question than market size alone: which opportunities are defensible, which are commoditizing, and where should resources be concentrated in 2026 and the years immediately following?
Polyvinylidene Difluoride (PVDF) Market
Turning Market Intelligence into 2026 Competitive Advantage
The strategic value of this research lies in its ability to convert complex, fast-moving market signals into a coherent decision-making framework. In a segment where capacity expansions are being announced years in advance, where raw material cost spikes can compress margins within a single quarter, and where regulatory trajectories can reshape demand assumptions overnight, reactive planning is a structural disadvantage. Organizations that ground their 2026 strategies in verified market sizing, segmentation clarity, competitive intelligence, and dynamic supply chain analysis will enter the forecast period with significantly greater operational confidence.
For procurement leaders, the analysis highlights where long-term contracting, alternate sourcing architectures, and cost-indexing mechanisms can mitigate volatility exposure. For product and R&D teams, it clarifies which application domains are scaling fastest and which technical specifications are becoming table stakes versus differentiators. For commercial and corporate strategy functions, it surfaces where competitive concentration creates partnership opportunities, where regional demand imbalances may justify localized investments, and where regulatory developments may accelerate or decelerate adoption curves. In each case, the underlying market intelligence serves as a shared reference point, reducing internal disagreement and accelerating execution.
Access the Complete Strategic Analysis
The overview presented here reflects the analytical framework, directional market signals, and structural dynamics that define the current PVDF landscape. It is designed to establish the strategic context and demonstrate the depth of insight available to decision-makers who require more than headline figures. However, the full segmentation breakdowns, region-specific demand mapping, product-type growth trajectories, application-level consumption analysis, and detailed competitive profiles are reserved for the complete market research publication.
For organizations preparing capital allocation decisions, supplier negotiations, capacity evaluations, or market entry assessments in 2026, the complete dataset provides the precision necessary to move from directional confidence to executable strategy. We invite you to access the full report to obtain the comprehensive intelligence, granular segmentation detail, and forward-looking scenario analysis required to navigate the next phase of PVDF market evolution with clarity and strategic conviction.
For detailed analysis of this topic, please visit the official page: Polyvinylidene Difluoride (PVDF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


