



PW Consulting: CRO Market Projected to Reach USD 152.6 Billion by 2032, Growing at 8.85% CAGR

Navigating the CRO Landscape: Strategic Intelligence for 2026 Decision-Makers
The global pharmaceutical and biotechnology sectors are entering a period of profound transformation. As research and development pipelines grow more complex, biopharma sponsors are increasingly relying on Contract Research Organizations to manage clinical execution, regulatory navigation, and data-driven trial optimization. PW Consulting's latest CRO Market study delivers a comprehensive, forward-looking assessment of this ecosystem, providing executives with the analytical rigor required to make informed capital allocation, partnership, and operational decisions in 2026 and beyond.
This report is designed not as a static snapshot, but as a strategic navigation tool. It synthesizes historical performance across 2020 through 2025 with a detailed forecast horizon extending to 2032. By mapping growth trajectories, competitive pressures, and structural shifts in service delivery, the study equips leadership teams with the contextual intelligence needed to anticipate market movements rather than simply react to them.
Macro Market Trajectory: Growth Foundations and Forward Outlook
The CRO sector has demonstrated consistent expansion over the past half-decade, evolving from a supportive outsourcing function into a core strategic infrastructure for drug development. Historical data reveals a sector that has repeatedly absorbed volume increases, therapeutic complexity, and regulatory evolution while maintaining secular growth. From a baseline perspective anchored in 2025, the market has already crossed significant valuation thresholds, reflecting sustained sponsor demand for integrated development capabilities, specialized laboratory services, and accelerated trial delivery models.
Contract Research Organization (CRO) Market
Looking toward the forecast window of 2026 through 2032, the market is projected to continue its upward trajectory at a compound annual growth rate of 8.85 percent. This expansion is not uniform across all phases or segments; rather, it reflects selective acceleration in high-complexity areas, sustained demand for late-stage execution, and growing reliance on analytical and data-management services that reduce development risk. The forecast period captures a critical inflection point where operational efficiency, digital trial capabilities, and regulatory alignment become decisive competitive differentiators.
Revenue projections through 2032 illustrate a market that scales materially beyond current levels, reinforcing the strategic importance of early positioning. Organizations that understand where growth concentrates, which service lines command premium value, and how competitive dynamics shift over the forecast horizon will be better positioned to negotiate partnerships, structure internal capabilities, and capture margin resilience in an increasingly contested environment.
Core Dimensions of Market Composition
A clear understanding of how the CRO market is structured is essential for strategic planning. The study examines the industry through multiple analytical lenses, each illuminating a different facet of demand, competition, and value creation.
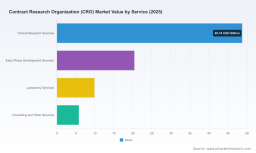
- By service model, the landscape spans clinical research execution, early phase development, laboratory and diagnostic support, and consulting-oriented engagement. Each category carries distinct operating economics, client retention dynamics, and scalability profiles that influence how sponsors select partners and how providers differentiate their offerings.
- By therapeutic focus, demand patterns reflect the scientific and regulatory demands of specific disease areas. Oncology, infectious disease programs, cardiovascular studies, and neurology and related indications each present unique trial design requirements, patient recruitment challenges, and data-generation expectations that shape service utilization and pricing dynamics.
- By geography, regional demand reflects variations in sponsor density, regulatory maturity, trial infrastructure, and cost structures. The study maps where development activity is concentrated, how execution capabilities are distributed, and what this implies for near-term capacity constraints and long-term market entry strategies.
These structural dimensions are examined not in isolation but in combination, allowing decision-makers to see how service demand, therapeutic complexity, and regional dynamics interact to create pockets of opportunity and pressure. Rather than presenting fragmented percentages in isolation, the report integrates these elements into a coherent view of where value is created and where competitive intensity is most acute.
Competitive Landscape: Concentration, Capabilities, and Strategic Positioning
The CRO market is characterized by a meaningful degree of concentration among established full-service and integrated providers, while simultaneously accommodating a diverse set of specialized and regionally focused operators. The study's competitive analysis evaluates how scale, scientific depth, data infrastructure, and therapeutic expertise influence market share, client relationships, and expansion pathways.
Market Concentration and Structural Implications
Concentration metrics indicate that a relatively small group of large providers commands a substantial share of aggregated industry revenue, reflecting the advantages of integrated service portfolios, global trial networks, and established sponsor relationships. At the same time, the remaining market is distributed across mid-tier and specialized firms that compete on speed, therapeutic specialization, regional access, or differentiated scientific capabilities. This dual structure matters for strategy: large providers often compete on breadth and risk-sharing, while smaller and mid-sized firms frequently win on agility, niche scientific expertise, and targeted regional execution.
Key Players and Strategic Profiles
The report profiles a broad set of organizations whose strategies define the current competitive environment. These include full-service clinical development organizations, integrated laboratory and imaging-enabled providers, firms combining trial execution with commercial launch support, and players with strong discovery-to-development or manufacturing-linked capabilities. The profiles assess operating models, service breadth, geographic reach, and the strategic logic behind recent moves in partnerships, acquisitions, and technology integration.
Among the firms analyzed are organizations headquartered across North America, Europe, and Asia-Pacific, reflecting the globalized nature of modern drug development. Their differing emphases illustrate the range of competitive approaches in the market: some prioritize end-to-end clinical delivery and analytics-driven trial management, others emphasize late-stage and government-sponsored research, while still others build value around integrated laboratory services, safety assessment, regulatory solutions, or combined development and manufacturing capabilities. Understanding these strategic orientations helps sponsors and investors evaluate fit, risk, and long-term positioning.
Recent Strategic Moves Shaping the Field
Competitive dynamics are also being reshaped by a series of notable developments that signal where the industry is placing its bets. In late 2025, one major full-service provider was recognized for excellence in clinical development, underscoring the continued premium on execution quality and sponsor trust. Around the same period, a leading laboratory and clinical services organization acquired a digital trial data and management platform for a substantial enterprise value, signaling the strategic importance of data infrastructure, decentralized trial capabilities, and technology-enabled operations.
In parallel, long-term clinical and commercial partnerships between major research organizations and platform technology providers have reinforced the trend toward deeper integration between trial execution and digital ecosystems. Collaborative initiatives involving artificial intelligence have also emerged, aimed at accelerating clinical development workflows, improving data quality, and reducing cycle times. Collectively, these moves highlight an industry in which technology, data, and partnership architecture are becoming as strategically important as traditional scientific and operational capabilities.
Market Dynamics: Technology, Regulation, and Operational Evolution
The CRO sector does not expand in a vacuum. Its trajectory is shaped by intersecting forces that influence how trials are designed, executed, and evaluated. Three dynamics are especially salient for 2026 planning.
Rare Disease CRO Service Market
Technology-Enabled Trial Execution
Digital tools, advanced data management, and AI-assisted workflows are increasingly central to clinical development. Sponsors are seeking partners that can integrate real-world evidence, analytics-driven trial management, and streamlined data capture into the development process. This shift is changing evaluation criteria for service providers, with capability in data integration, operational visibility, and adaptive trial support becoming key differentiators. The market study examines how these technology-oriented demands are influencing service mix, investment priorities, and competitive advantage.
Regulatory Standards and Evaluation Frameworks
Regulatory expectations and consensus standards continue to shape development strategies, particularly for organizations navigating early feasibility, device-related evaluations, and complex clinical assessments. Standards-developing bodies and consensus-standards adoption processes play a pivotal role in defining the quality, risk management, preclinical, and clinical evaluation expectations that sponsors and service providers must meet. Familiarity with these frameworks significantly influences regulatory strategy, especially in early-stage programs where alignment with recognized standards can reduce uncertainty and accelerate progression.
The report contextualizes these regulatory dynamics without treating them as isolated compliance issues. Instead, it frames them as structural drivers of demand for specialized expertise, quality systems, and regulatory-aware trial design. For CROs and sponsors alike, the ability to operate confidently within evolving standards environments is becoming a core strategic capability rather than a back-office function.
Service Integration and Value-Chain Positioning
A broader trend toward integration is evident across the market. Sponsors increasingly prefer partners that can connect clinical execution, laboratory support, imaging, data management, and regulatory consulting within a coherent delivery model. This preference is pushing providers to expand their value-chain footprint, whether through organic build-out, targeted acquisitions, or strategic alliances. The study analyzes how integration affects pricing power, client retention, operational risk, and the ability to support complex programs from early development through later-stage execution.
What the Study Delivers: Operational Content for Decision-Makers
This CRO Market study is built for practical use. Beyond high-level market sizing and growth trajectories, it provides decision-makers with structured analysis that can be applied directly to strategy, sourcing, investment, and competitive planning.
- A forecast-backed view of market evolution from 2026 through 2032, anchored in historical performance from 2020 to 2025, enabling scenario-aware planning rather than single-point estimates.
- Segment-level analysis across service categories, therapeutic areas, and geographic demand patterns, integrated to reveal where growth is most durable and where competitive intensity is rising.
- Detailed competitive profiling of leading and emerging providers, with attention to operating models, capabilities, and the strategic rationale behind recent partnerships, acquisitions, and technology initiatives.
- Assessment of the structural forces shaping the market, including digital trial infrastructure, regulatory-standard alignment, and value-chain integration, framed in terms of their implications for sourcing strategy and long-term positioning.
- Contextual intelligence on the operating environment, including the role of consensus standards and regulatory-review practices in influencing clinical evaluation pathways and early feasibility strategies.
Each section is designed to support concrete decisions: which partners align with a given development strategy, where capacity and expertise are likely to tighten, how service mix may shift as programs become more complex, and which competitive moves are likely to reshape sourcing options over the forecast period.
Strategic Implications for 2026 and Beyond
For executives planning in 2026, the central takeaway is that the CRO market is growing, but growth alone does not guarantee advantage. The real strategic question is how to align internal development ambitions with an external service environment that is becoming more concentrated at the top, more differentiated in the middle, and more technology-dependent across the board.
Organizations that approach CRO engagement strategically, rather than transactionally, will be best placed to manage risk and accelerate delivery. That means evaluating partners not only on cost and timeline, but also on data infrastructure, regulatory fluency, therapeutic depth, and the ability to support integrated development pathways. It also means recognizing that recent industry moves around digital trial capabilities, AI-enabled workflows, and major platform acquisitions are not isolated headlines; they are indicators of where competitive advantage is being built.
Likewise, sponsors and investors should pay close attention to concentration trends and the strategic behavior of leading providers. A market in which a limited number of large firms command a substantial share of revenue will reward early relationship-building, clear capability requirements, and disciplined evaluation of long-term partnership options. At the same time, specialized and regionally oriented providers will continue to offer important alternatives for programs that demand focused expertise or specific geographic access.
Conclusion: From Market Intelligence to Actionable Strategy
The CRO sector is entering a phase in which scale, scientific capability, technological integration, and regulatory alignment converge to define competitive success. PW Consulting's CRO Market study provides the analytical foundation needed to navigate that convergence with confidence. By combining historical context, forecast-driven perspective, and competitive intelligence into a single strategic framework, the report helps executives move from awareness to action.
The full study contains the detailed segmentation analysis, company-specific evaluation, and forward-looking market logic required to translate these insights into concrete decisions for 2026 planning and beyond. For teams seeking a deeper, data-rich view of where the market is headed and how to position accordingly, the complete report offers the comprehensive intelligence necessary to support informed, strategically aligned action.
For detailed analysis of this topic, please visit the official page: Contract Research Organization (CRO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


