



PW Consulting: Low-Speed Vehicle Market Hits $9.2B in 2025, Poised for 8% CAGR Through 2032

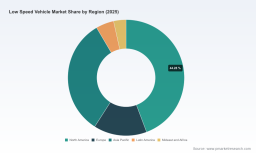
Strategic Horizons: Navigating the Low Speed Vehicle Market in 2026 and Beyond
Executive Overview: The Pulse of a Transformative Sector
The Low Speed Vehicle (LSV) sector has evolved from a niche auxiliary market into a structured component of the broader light electric mobility landscape. Between 2020 and 2025, the industry demonstrated remarkable structural resilience, expanding from a baseline of 6.3 billion USD to an estimated 9.2 billion USD by the close of 2025. This trajectory reflects more than incremental adoption; it signals a fundamental recalibration of how municipalities, commercial operators, and private communities integrate constrained-speed mobility solutions into daily operations. As we look toward the forecast window of 2026 through 2032, the market is projected to surpass 15.7 billion USD, driven by a compound annual growth rate of approximately 8.0 percent. For executive teams and capital allocators, the 2026 inflection point is particularly critical. It represents the convergence of regulatory clarity, supply chain recalibration, and shifting application demands that will define competitive positioning for the remainder of the decade.
PW Consulting’s latest Low Speed Vehicle Market study is designed not as a static data repository, but as a strategic navigation instrument. The report maps historical momentum against forward-looking operational variables, offering decision-makers a structured framework to align product roadmaps, partnership strategies, and regional deployment plans with the realities of an increasingly regulated and technologically maturing market. What follows is a preview of the analytical architecture underpinning this research, highlighting the dimensions that matter most as organizations prepare for the 2026 operating cycle and beyond.
Market Architecture: Historical Momentum and the 2026 Inflection Point
The market’s expansion over the past five years tells a story of consistent, compounding value creation. From 2020 through 2022, growth was characterized by measured adoption within established recreational and resort ecosystems. By 2023, however, the trajectory steepened as commercial and institutional buyers began recognizing the operational efficiencies of purpose-built low-speed platforms. The jump from 7.6 billion USD in 2023 to nearly 8.7 billion USD in 2024 underscores this shift, reflecting both volume expansion and the gradual premiumization of vehicle specifications. Entering 2025, the market closed at approximately 9.2 billion USD, positioning the sector at a threshold where scale, standardization, and supply chain maturity begin to interact in ways that reward strategic foresight.
Looking ahead, the forecast period reveals a sustained upward arc. By 2026, revenue is projected to reach nearly 10 billion USD, with the curve continuing its ascent through 2032. The 8.0 percent CAGR embedded in these projections is not merely a growth indicator; it is a structural signal. It implies that demand drivers are diversifying beyond traditional recreational use cases, regulatory frameworks are stabilizing around recognized safety benchmarks, and manufacturing footprints are adapting to both domestic protection measures and material innovation. Organizations that treat 2026 as a planning anchor rather than a static checkpoint will be best positioned to capture the value embedded in this expansion curve.
Competitive Dynamics: Incumbent Strategies and Recent Market Shifts
The competitive landscape in the LSV space remains moderately fragmented, yet concentration trends reveal clear patterns of consolidation and strategic positioning. Market leadership is distributed across a cohort of established manufacturers with deep roots in electric utility, golf, and neighborhood mobility segments. The top three players collectively account for approximately 24.6 percent of market revenue, while the top five extend that share to 26.2 percent. This distribution suggests that while no single entity commands dominant market control, recognized brands with certified product lines, established distribution channels, and compliance infrastructure retain meaningful advantages in procurement cycles and end-user trust.
Several core companies define the current competitive baseline. Club Car, headquartered in Auburn, Alabama, continues to manufacture street-legal Onward LSV models that align with NHTSA standards and SAE J2358 specifications, offering both electric utility and passenger variants. Textron Specialized Vehicles, operating out of Westerville, Ohio, sustains its presence through E-Z-GO and Cushman platforms engineered to meet FMVSS 500 and NHTSA LSV requirements for neighborhood and utility applications. GEM Products, based in Anaheim, California, assembles electric LSV models across the e2, e4, e6, and eL XD series, with certifications that include roof-crush protection and NHTSA-aligned safety standards. Yamaha Golf-Car Company, located in Cypress, California, leverages an exclusive North American agreement to distribute and support Pilotcar-branded electric LSV models, notably the PC-2 and PC-4 configurations, with street-legal certification. Bintelli Electric Vehicles, based in Charleston, South Carolina, assembles street-legal LSV and electric golf cart models within the United States, maintaining full compliance with federal LSV standards. American Landmaster, operating from Johnson City, Tennessee, produces domestically manufactured LSV and utility vehicle models certified under NHTSA low-speed vehicle classifications.
Recent market developments further illustrate how competitive positioning is being reshaped by partnership structures, regulatory determinations, and adoption trends. In early 2025, Yamaha Golf-Car Company announced exclusive North American distribution rights and wholesale operations for Pilotcar electric LSV models, effective from the first quarter of that year. This move expanded Yamaha’s product portfolio and reinforced its distribution leverage across the region. By the first quarter of 2026, broader industry data had identified a notable surge in street-legal LSV adoption, highlighting new profit opportunities for U.S. manufacturers. That momentum intersected with a significant trade determination in mid-2025, when the U.S. International Trade Commission issued an affirmative final determination in investigations concerning Chinese LSPTV imports, concluding that domestic LSV producers had been materially injured by unfair import practices. The outcome has structural implications for pricing, sourcing strategies, and competitive insulation for American-based manufacturers.
Regulatory and Technological Undercurrents
Regulatory compliance is no longer a peripheral consideration in LSV market strategy; it is a core requirement that shapes product design, certification pathways, and market access. LSVs must adhere to 49 CFR 571.500 FMVSS standards and SAE J2358 performance specifications, which establish baseline expectations for occupant protection, braking capability, and structural integrity. NHTSA certification labels and compliance with occupant protection and brake standards are mandatory for vehicles marketed under the low-speed classification, reinforcing the importance of documented conformity throughout the manufacturing and distribution chain. These requirements create a compliance barrier that favors established producers with mature quality assurance processes while raising the entry threshold for new market participants.
At the same time, material and powertrain transitions are redefining product economics. Lithium-ion batteries are increasingly specified in LSV models, offering extended range and reduced maintenance relative to traditional lead-acid alternatives. This shift affects total cost of ownership calculations, service interval planning, and resale valuation, making battery chemistry a strategic procurement variable rather than a purely technical specification. Complementary design choices also matter. Aluminum chassis components provide rust-proof durability and contribute to maintaining overall vehicle weight below the 3,000 lbs GVWR threshold required for LSV classification. These engineering considerations intersect with regulatory constraints, influencing both manufacturing cost structures and product longevity profiles.
Low Speed Vehicle Market
For strategists, the regulatory and technological landscape presents a dual reality. Compliance frameworks create predictability, enabling long-term capital planning and regional expansion modeling. Simultaneously, material and battery evolution introduce continuous improvement cycles that require manufacturers and buyers alike to stay current with specification shifts. The 2026 environment will reward organizations that integrate compliance readiness with technology roadmapping rather than treating them as separate functions.
What the Report Delivers: A Practical Intelligence Toolkit
This study is structured to move beyond high-level market sizing and into the operational dimensions that drive executable strategy. The analytical framework is organized to support cross-functional use, from product planning and procurement to sales positioning and partnership evaluation. Key components of the report include:
- Comprehensive historical tracking and forward projections that contextualize growth across the 2020 to 2032 window, with explicit attention to the 2026 decision horizon.
- Segmentation analysis that dissects market value across vehicle types, application environments, and regional demand patterns, enabling targeted go-to-market planning without relying on generic industry narratives.
- Competitive profiling of established manufacturers, including product certifications, geographic footprints, and recent strategic actions that illustrate how incumbents are adapting to regulatory and trade dynamics.
- Regulatory and standards mapping that translates FMVSS, NHTSA, and SAE compliance requirements into practical implications for sourcing, labeling, and market entry.
- Material and powertrain trend evaluation, with attention to battery chemistry adoption, chassis material selection, and their impact on weight classification, maintenance cycles, and total cost of ownership.
- Trade and policy context that connects domestic industry protection measures to sourcing strategies, pricing flexibility, and competitive insulation for U.S.-based production.
The objective is to provide decision-makers with a layered view of the market: enough structural context to validate strategic assumptions, and enough granular insight to inform budget allocation, product prioritization, and partnership selection. Readers who engage with the full report will find actionable frameworks rather than abstract trend statements, making the research suitable for use in board-level discussions, product committee reviews, and regional expansion planning.
Strategic Implications for 2026 Decision-Makers
As organizations prepare their 2026 plans, several strategic themes emerge from the market structure and recent developments. First, compliance capability is becoming a competitive differentiator. With clear NHTSA and FMVSS requirements governing occupant protection, braking performance, and certification labeling, manufacturers and distributors that institutionalize compliance verification will reduce time-to-market friction and strengthen credibility with institutional buyers. Second, trade policy is reshaping sourcing logic. The affirmative determination on Chinese LSPTV imports creates a protective environment for domestic producers, but it also requires careful evaluation of component sourcing, assembly footprints, and price architecture to fully capitalize on the shifting landscape.
Third, application diversification is accelerating. While golf courses and hotels and resorts continue to represent substantial demand centers, industrial facilities, airports, and other specialized environments are expanding their reliance on low-speed platforms for internal mobility, cargo movement, and personnel transport. Each application brings distinct operational requirements, service expectations, and procurement cycles. A segmented approach to product configuration and sales outreach will outperform one-size-fits-all positioning. Fourth, powertrain and material choices are influencing both economics and classification compliance. The transition toward lithium-ion batteries and aluminum chassis components is not merely an engineering preference; it affects vehicle weight, durability, maintenance planning, and lifecycle cost. Organizations that align procurement strategy with these shifts will gain advantages in total cost of ownership and end-user satisfaction.
Finally, the moderate concentration of the market, combined with active partnership activity and product portfolio expansion, suggests that 2026 will be a year of strategic realignment rather than passive growth. Companies that define clear positioning around compliance readiness, application specialization, and domestic production advantages will be better equipped to capture share in a market that is large enough to accommodate multiple winners but structured enough to reward discipline.
L7 and L6 Quadricycles Market
Closing Perspective
The Low Speed Vehicle market in 2026 stands at the intersection of regulatory maturation, material innovation, and expanding application demand. The projected trajectory from roughly 10 billion USD in 2026 toward more than 15.7 billion USD by 2032 reflects a sector that is consolidating its operational logic while continuing to open new revenue pathways. Success in this environment will depend on the ability to translate market scale into targeted execution: choosing the right compliance pathways, aligning product specifications with application realities, and positioning supply chains to benefit from the evolving trade and production landscape.
PW Consulting’s full Low Speed Vehicle Market study provides the depth, segmentation, and competitive intelligence required to make those decisions with confidence. The analysis presented here offers a structural preview, but the complete report contains the detailed breakdowns, company-level assessments, and forward-looking scenarios that equip leadership teams to move from awareness to action. For executives, planners, and investors seeking to navigate the 2026 landscape with precision, the full research deliverable is the essential next step.
For detailed analysis of this topic, please visit the official page: Low Speed Vehicle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


