



OLED Lighting Panels Market to Hit $127.13M by 2032, PW Consulting Reports

Illuminating the Future: Strategic Insights into the OLED Lighting Panels Market Through 2032
The transition from traditional illumination to advanced organic light-emitting diode (OLED) technology represents more than a technological upgrade; it signifies a fundamental shift in how industries approach design, efficiency, and user experience. As we navigate the complexities of the global lighting landscape in 2026, understanding the trajectory of OLED lighting panels is critical for stakeholders aiming to capitalize on emerging opportunities. Our latest market research study provides a comprehensive analysis of this evolving sector, offering the data-driven intelligence necessary to formulate robust strategies for the coming years.
This report serves as a definitive guide for executives, investors, and product developers who need to navigate the interplay between technological innovation, regional demand shifts, and competitive dynamics. By examining historical performance from 2020 through 2025 and projecting forward to 2032, we uncover the underlying forces shaping the market value and growth potential. The following analysis highlights the strategic value of this research and outlines the key themes that will define the industry landscape in the immediate future.
Market Trajectory and Growth Horizons
The global OLED lighting panels market has demonstrated resilient growth over the past half-decade, recovering from initial deployment challenges to establish a steady upward curve. Our analysis tracks revenue progression from approximately 67.1 million USD in 2020 to an estimated 87.7 million USD in 2025. This historical baseline provides crucial context for understanding the momentum entering the forecast period. The market is projected to continue its expansion through 2032, driven by increasing adoption in commercial, automotive, and specialized industrial applications.
Forecast data indicates a compound annual growth rate (CAGR) of 5.56 percent during the 2026 to 2032 period. This growth rate suggests a mature yet expanding market environment where incremental gains are driven by technological refinements and broader acceptance rather than volatile speculation. By 2032, the market revenue is expected to reach significant milestones, reflecting the cumulative effect of investment in manufacturing capacity and the penetration of OLED solutions into mainstream lighting sectors. Understanding these top-line figures is essential for capacity planning and investment timing, but the true value lies in dissecting the drivers behind these numbers.
Worldwide LED Panel Lights Market
Segmentation Dynamics and Application Shifts
The market is not monolithic; it is defined by distinct segments that exhibit varying growth characteristics and strategic priorities. Our research dives deep into the breakdown of the market by type and application, revealing where the highest value creation is occurring. For instance, the balance between flexible and rigid panel technologies highlights the industry's pivot toward design versatility. The data suggests that flexible solutions are capturing a substantial share of the landscape, reflecting the demand for form factors that can be integrated into curved surfaces and innovative architectural designs. Rigid panels continue to hold significant ground, particularly in applications where structural stability and uniform illumination are paramount.
Application-wise, the landscape is diversifying. Traditional lighting remains a core pillar, yet the most dynamic growth vectors are emerging from specialized sectors. Automotive lighting represents a key area of expansion, fueled by the broader trend of vehicle electrification and the consumer demand for personalized interior and exterior lighting experiences. Beyond these primary categories, a significant portion of the market is attributed to other specialized uses, indicating that OLED technology is finding niches in industrial inspection systems and high-color-rendering commercial installations. Our report details these splits without obscuring the strategic implications, allowing decision-makers to identify which segments align with their core competencies.
Regional Analysis and Global Supply Chains
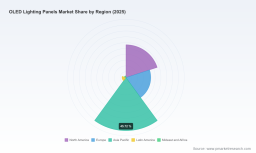
Geographical distribution of demand and production capacity plays a pivotal role in shaping market strategy. The Asia Pacific region stands out as a dominant force in the global landscape, reflecting the concentration of manufacturing infrastructure and rapid adoption rates in key economies. North America and Europe follow as significant markets, driven by stringent energy efficiency regulations and a strong focus on sustainable design in commercial spaces. Emerging regions, including Latin America and the Middle East and Africa, present nascent opportunities that may offer higher growth rates from a smaller base, though they require tailored market entry strategies.
Our analysis examines how these regional disparities influence supply chain logistics and pricing power. The concentration of manufacturing capabilities in specific zones underscores the importance of understanding local regulatory environments and labor dynamics. For example, while advanced production lines offer high precision, they also face challenges related to specialized labor availability and cost structures. By mapping the geographical revenue distribution, companies can better assess where to locate production facilities, where to focus sales efforts, and how to mitigate risks associated with regional economic fluctuations.
Competitive Landscape and Key Industry Players
The OLED lighting panels market is characterized by a mix of specialized manufacturers and large-scale display technology giants. The competitive environment is moderately concentrated, with the top three companies holding a significant share of the market revenue, while the top five players command a majority of the industry value. This structure suggests that while there is room for innovation from smaller players, scale and technological leadership are critical determinants of success.
Several key companies are setting the pace for innovation and commercialization. OLEDWorks, based in Rochester, NY, continues to lead in automotive applications, particularly with its Atala-series panels used for rear lighting and interior personalization. Their focus on high-performance solutions positions them well as vehicle electrification increases the demand for custom lighting profiles. LG Display, headquartered in Seoul, South Korea, brings immense production capacity to the table, with mass production capabilities exceeding 900,000 units annually. Their ability to scale production makes them a formidable player in the commercial lighting space.
In Japan, a cluster of companies is driving technological advancement and material science innovation. Konica Minolta is actively expanding its production capabilities, recently announcing the construction of a new roll-to-roll pilot coating line within its Hino facility in Tokyo. This move signals a commitment to improving manufacturing efficiency and throughput. Lumiotec, located in Yonezawa City, specializes in commercial panels with high color rendering index options, catering to applications where light quality is as critical as efficiency. Kaneka focuses on niche applications, including industrial inspection systems, demonstrating the versatility of OLED technology beyond general illumination.
Furthermore, the supply chain ecosystem is vital. Sumitomo Chemical, also based in Tokyo, provides polymer OLED materials that enable solution-processed panel production using printable ink technology. This material science capability underpins the ability of downstream manufacturers to create flexible and cost-effective panels. NEC Lighting rounds out the competitive landscape by providing panels for commercial and architectural installations, emphasizing the aesthetic and functional integration of OLEDs in built environments.
Recent Developments and Technological Advances
The pace of innovation in 2026 has been particularly brisk, with major players announcing significant milestones that will shape the market for years to come. In March 2026, Konica Minolta unveiled its plans for a new roll-to-roll pilot coating line, a development that promises to enhance production flexibility and potentially lower costs through advanced coating techniques. This infrastructure investment highlights the industry's focus on scaling manufacturing processes to meet growing demand.
May 2026 saw LG Display present next-generation tandem OLED technologies at the SID Display Week. Tandem structures are widely recognized for their potential to improve brightness, efficiency, and lifespan, addressing some of the historical limitations of OLED lighting. This presentation underscored the company's commitment to pushing the boundaries of performance. Following this, in June 2026, OLEDWorks announced advancements in high-performance multi-stack OLED technology. These parallel developments in tandem and multi-stack architectures indicate a industry-wide race to optimize light output and energy consumption, which are critical metrics for both regulatory compliance and consumer acceptance.
Drivers, Restraints, and Market Dynamics
Several macro and micro factors are influencing the market trajectory. Energy efficiency mandates are increasingly driving the adoption of low-power OLED lighting panels in commercial spaces. As governments and building management organizations impose stricter standards on energy consumption, the inherent advantages of OLED technology, such as low heat generation and directional light emission, become more valuable. This regulatory pressure acts as a catalyst for replacing older lighting infrastructure with newer, compliant solutions.
Simultaneously, the automotive sector is undergoing a transformation that benefits OLED lighting. The electrification of vehicles increases the demand for custom OLED lighting panels, as electric vehicle platforms offer more design freedom and require sophisticated lighting signatures for branding and safety. Consumers are increasingly viewing lighting as a key element of vehicle personalization, creating a premium market segment that rewards high-quality, flexible OLED solutions.
OLED Lighting Panels Market
However, challenges remain. The average market price for OLED lighting panels remains a consideration for mass adoption, with industry data indicating prices around 1,600 USD per square meter in 2025. While costs are expected to decrease with scale and process improvements, price sensitivity in certain applications may slow penetration. Additionally, specialized manufacturing faces labor shortages in advanced production lines, which can constrain capacity expansion and increase operational costs. Addressing these constraints requires strategic workforce development and automation investments.
Strategic Recommendations for 2026 and Beyond
For organizations operating in or entering the OLED lighting panels market, the insights from this research point to several actionable strategies. First, understanding the specific needs of high-growth segments is essential. Companies should evaluate whether their portfolios align with the demands of automotive personalization or high-efficiency commercial installations, as these areas show strong momentum. Second, monitoring the technological race between tandem and multi-stack solutions is crucial. Early adoption of next-generation architectures could provide a competitive edge in performance and efficiency, distinguishing products in a crowded marketplace.
Third, supply chain resilience must be prioritized. Given the concentration of manufacturing in specific regions and the reliance on specialized materials from key suppliers, diversifying sourcing and investing in vertical integration where feasible can mitigate risks. Finally, keeping a close watch on regulatory developments regarding energy efficiency will allow companies to anticipate demand shifts and position their products as compliance-ready solutions.
Conclusion
The OLED Lighting Panels Market is at an inflection point where technological maturity meets expanding application scope. The projected growth through 2032 offers substantial opportunities for those equipped with the right intelligence. Our comprehensive market research study provides the detailed segmentation data, competitive profiles, and forward-looking analysis required to make informed decisions. We invite industry leaders to explore the full report to gain access to the granular data and strategic frameworks that will define success in this illuminating sector.
For detailed analysis of this topic, please visit the official page: OLED Lighting Panels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


