



PW Consulting: Education Software Market Hits $89.3M in 2025, Poised for $190.8M by 2032

Navigating the Next Wave: Strategic Intelligence for the Education Software Market (2026–2032)
The global education software landscape is undergoing a structural transformation that demands more than passive observation from enterprise leaders. As digital learning ecosystems mature, the convergence of adaptive technologies, regulatory scrutiny, and shifting institutional procurement models is redefining competitive advantage. PW Consulting’s latest market intelligence study on the Education Software Market is engineered to equip executives, investors, and product strategists with the analytical clarity required to navigate this inflection point. Rather than offering a static snapshot, this research delivers a forward-looking operational framework calibrated to the decision cycles of 2026 and beyond.
Industry participants today face a dual mandate. They must scale technology deployments while simultaneously defending against rising compliance costs, data governance risks, and intensifying vendor consolidation. The market has already demonstrated considerable momentum, with global revenue climbing from approximately 52.3 million USD in 2020 to an estimated 89.3 million USD by 2025. More importantly, the trajectory ahead points to sustained expansion at a compound annual growth rate of 11.5 percent through 2032. Such growth is not uniform across all cohorts. It is increasingly concentrated among organizations that can integrate data-driven personalization, responsible artificial intelligence, and resilient security architectures into their core offerings. Enterprises that treat these capabilities as optional enhancements will find themselves structurally disadvantaged as procurement standards tighten and end-user expectations accelerate.
The strategic value of this publication lies in its refusal to simplify complexity. By anchoring analysis in rigorous historical baselines and forward projections, the report translates macro-level momentum into actionable Go-to-Market considerations. Leaders evaluating product roadmaps, partnership portfolios, or regional expansion strategies will find a structured lens for weighing trade-offs between rapid innovation and long-term defensibility. The following sections outline the analytical architecture of the study and demonstrate how each component maps directly to the operational priorities shaping 2026 decision-making.
Decoding the 2026–2032 Growth Trajectory
Market expansion in education software is no longer driven by routine digitization alone. It is being reoriented by pedagogical shifts, institutional budget reallocations, and the maturation of cloud-native delivery models. The report’s historical analysis establishes a clear baseline, tracing revenue progression across the 2020–2025 window before projecting sustained acceleration through 2032. This longitudinal view is essential for executives who must distinguish between temporary demand spikes and durable structural growth. A double-digit CAGR environment rewards organizations that can align product cadence with institutional procurement cycles, while penalizing those that over-invest in features without clear instructional or administrative utility.
Forward projections in this study are structured to support scenario planning rather than rigid forecasting. Executives gain visibility into how growth may propagate across different deployment models, usage contexts, and buyer archetypes. This granularity matters because aggregate numbers obscure the operational realities that determine execution success. By mapping demand patterns to underlying adoption drivers, the analysis enables leadership teams to anticipate where procurement emphasis will shift, which performance metrics will gain prominence, and how pricing architectures may need to evolve under increasing competitive pressure.
Education Software Market
Crucially, the report also addresses the cost dynamics that frequently erode projected margins. Ongoing software maintenance, security patching, and continuous functionality updates typically add between fifteen and twenty-five percent of original development expenditure each year. For product organizations and institutional buyers alike, this recurring burden reshapes total cost of ownership calculations and influences long-term vendor selection. The study integrates these operational realities into its strategic assessment, ensuring that growth narratives are grounded in the economics of sustained delivery rather than initial market entry.
Navigating Regulatory Pressures and Competitive Realignment
The sector’s growth trajectory is unfolding against a backdrop of intensifying regulatory scrutiny and restructuring competitive dynamics. Data protection has moved from a compliance checkbox to a strategic differentiator. Recent enforcement actions highlight the reputational and operational stakes involved. For example, the Federal Trade Commission reached a settlement with Illuminate Education requiring the implementation of a comprehensive information security program and the deletion of unnecessary data following a breach that exposed personal information of more than ten million students. Simultaneously, the U.S. Department of Education issued a formal inquiry to Instructure Holdings to verify compliance with the Family Educational Rights and Privacy Act. These developments underscore a broader reality: institutions and enterprise buyers are increasingly evaluating vendors through the lens of data stewardship, security maturity, and procedural transparency.
At the same time, the competitive landscape remains moderately concentrated, with a handful of established players commanding a substantial share of total market revenue. This concentration does not imply stagnation. Instead, it signals a market where differentiation is increasingly derived from pedagogical depth, integration capability, and responsible technology deployment rather than raw feature volume. Several leading organizations are already pivoting toward AI-enhanced learning support, personalized instruction pathways, and credentialing ecosystems that bridge academic and professional outcomes. Recent corporate activity reinforces this direction: one major publisher introduced new AI-driven capabilities within its digital course solution for higher education, emphasizing responsible deployment, real-time student support, and tailored reading experiences. Another prominent language and learning platform reported annual bookings surpassing one billion USD while authorizing a significant share repurchase program, reflecting both commercial scale and strategic confidence. Meanwhile, a personalized K-12 teaching and learning provider garnered multiple industry recognitions for its multilingual, cross-subject instructional solution, highlighting the premium that institutions place on adaptability and breadth of coverage.
These developments are not isolated signals. They illustrate a market where competitive advantage is shifting toward organizations that can harmonize innovation with accountability, demonstrate measurable instructional impact, and sustain trust across highly regulated buyer environments. Executives evaluating partnership opportunities, acquisition targets, or competitive positioning must therefore look beyond headline market share and assess the underlying capabilities that determine long-term resilience.
Inside the Report: Analytical Depth Designed for Execution
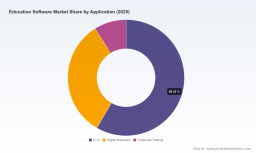
This publication is structured to function as a working reference for cross-functional strategy teams rather than a high-level commentary. The analytical architecture spans multiple interconnected dimensions, each designed to answer a specific class of executive question. Readers will encounter a detailed segmentation analysis that decomposes demand patterns across solution categories, deployment contexts, and institutional adoption profiles. Rather than treating these dimensions in isolation, the report examines how they intersect, enabling leaders to identify where value creation is most concentrated and which buyer segments are likely to drive incremental spend.
The competitive and vendor landscape assessment goes beyond organizational profiling to evaluate strategic positioning, capability alignments, and recent developmental moves that indicate future trajectory. By mapping organizational focus areas against evolving procurement priorities, the study helps teams anticipate which vendors are likely to strengthen their hold on key segments and which may face pressure to reposition. Regional analysis is similarly contextualized, offering leaders a comparative view of demand maturity, institutional procurement behavior, and expansion feasibility without reducing complex markets to oversimplified rankings.
Beyond structural analysis, the report incorporates practical execution considerations. It addresses the total cost implications of sustained software delivery, the operational requirements of responsible AI integration, and the compliance expectations that increasingly shape procurement decisions. These elements are woven into strategic recommendations so that product, commercial, and risk functions can align on a shared operating posture. For organizations evaluating market entry, portfolio expansion, or partnership strategy, the document provides a disciplined basis for comparing opportunity against execution complexity.
Translating Intelligence into 2026 Strategic Action
Market intelligence delivers value only when it informs concrete decisions. For executive teams operating in the education software sector, the 2026–2032 window will reward organizations that can synchronize product strategy with institutional procurement behavior, regulatory expectations, and the economics of long-term service delivery. The study is designed to support that synchronization by converting trend observation into prioritized action pathways. Leaders can use the analysis to stress-test product roadmaps against emerging buyer requirements, evaluate whether current positioning will hold under intensifying competition, and determine where investment should be concentrated to capture durable demand rather than transient attention.
The report also serves as a shared analytical foundation for cross-functional alignment. Commercial teams can calibrate messaging around measurable impact and compliance readiness. Product organizations can benchmark development priorities against the capabilities that are gaining institutional traction. Risk and governance functions can integrate data stewardship expectations into vendor evaluation and internal deployment standards. When these functions operate from a common evidence base, strategic decisions become more coherent, resource allocation more disciplined, and market response more agile.
Ultimately, the Education Software Market will not be defined solely by the speed of technological advancement. It will be shaped by the organizations that can pair innovation with operational discipline, align their offerings with real instructional and administrative needs, and navigate an environment where trust and transparency are becoming core commercial assets. This study provides the structured intelligence necessary to make those judgments with confidence.
Access the Complete Strategic Assessment
The insights summarized here represent only the opening layer of a far broader analytical effort. The full report expands on segmentation dynamics, competitive positioning, regional demand patterns, procurement behavior, and the operational cost structures that shape long-term profitability. It also includes detailed company profiles, recent developmental milestones, and scenario-based considerations that help executives translate market momentum into executable strategy.
Educational and Training Software Market
For organizations preparing investment decisions, product roadmap adjustments, or market-entry evaluations in 2026, the complete publication offers the depth required to move from informed perspective to decisive action. Readers seeking the full dataset, granular segmentation analysis, and extended competitive intelligence are encouraged to access the complete report through the official PW Consulting research portal. The complete assessment is designed to function as a standalone strategic resource, enabling leadership teams to extract the precise intelligence needed for their specific decision context while maintaining a clear line of sight to the broader market trajectory.
For detailed analysis of this topic, please visit the official page: Education Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


