



PW Consulting: Steel Round Bars Market to Hit $326B by 2032, 5.1% CAGR

Navigating the Steel Round Bars Market: Strategic Intelligence for 2026 Decision-Makers
The global steel round bars market stands as a critical backbone for industrial infrastructure, yet its complexity often obscures clear navigational paths for executives. As we move deeper into 2026, understanding the interplay between historical performance and future trajectory is no longer optional—it is essential for maintaining competitive advantage. PW Consulting presents this comprehensive market study to decode these dynamics, offering a granular view of an industry projected to evolve significantly over the next decade.
Market intelligence in this sector must go beyond surface-level trends. Stakeholders require precise data on valuation, growth inhibitors, and competitive maneuvering to allocate capital effectively. This article serves as a strategic preview of our latest deep-dive analysis, outlining the macroeconomic contours and the specific operational insights contained within the full report. The goal is to equip leadership teams with the context needed to validate internal assumptions against external market realities.
Market Trajectory and Valuation Horizons
The financial scale of the steel round bars industry underscores its significance in the global materials landscape. Based on historical data spanning from 2020 through the base year of 2025, the market has demonstrated substantial resilience and expansion. The total revenue generated by this sector has grown from approximately 180.0 USD Billion in 2020 to an estimated 230.0 USD Billion in 2025. This upward trajectory reflects sustained demand across core industrial verticals despite fluctuating economic conditions.
Looking forward, the forecast period from 2026 to 2032 suggests continued growth, with the market size projected to reach 247.98 USD Billion in 2026 alone. The analysis indicates a Compound Annual Growth Rate (CAGR) of 5.1 percent over the forecast horizon, signaling steady consolidation and expansion. By the end of the forecast period in 2032, valuations are expected to climb significantly higher, reflecting long-term confidence in infrastructure development and manufacturing output.
However, raw valuation numbers only tell part of the story. The nuances of year-over-year performance, such as the slight contraction observed in 2024 before recovering in 2025, highlight the volatility inherent in commodity-driven markets. Our study dissects these fluctuations to identify whether they represent temporary supply chain disruptions or structural shifts in demand. Understanding these patterns allows procurement managers and investors to time their entries and exits with greater precision.
Industry Dynamics and Material Flows
Current market dynamics are being reshaped by a confluence of regulatory changes, raw material cost pressures, and logistical adjustments. Recent developments in early 2026 illustrate the volatility that buyers must account for. In April 2026, major producers such as Nucor Bar Mill Group announced price increases for commercial long products and certain large structural sections. Similarly, Gerdau Long Steel North America implemented merchant bar and structural section price increases around the same period. These moves signal upstream pressure on pricing structures that will likely ripple through the supply chain.
Logistical costs are also under scrutiny. In March 2026, Norfolk Southern issued a public tariff announcement adjusting market-based rates for iron, steel, and scrap metal commodities, effective July 1, 2026. Such regulatory adjustments directly impact the landed cost of materials, influencing regional competitiveness and margin structures for downstream manufacturers.
On the raw material front, market intelligence indicates shifting cost bases. As of May 2026, iron ore prices reached levels around 114.7 USD per ton CFR, representing a month-over-month increase. Concurrently, billet prices rose by 10 to 20 USD per ton in regional markets during May 2026. These input cost hikes challenge manufacturers to maintain price stability without eroding profitability. Conversely, long-term forecasts from institutions like the World Bank suggest iron ore prices may decline further in 2026–27, potentially falling below 2019 levels due to expanding supply. This divergence between short-term spikes and long-term outlooks creates a complex environment for hedging strategies.
Furthermore, international trade policies are tightening. Multiple countries, including the EU and Uzbekistan, have introduced export duties or quotas on ferrous scrap in 2025–2026. These restrictions alter the availability of recycled raw materials, impacting electric arc furnace operations and cost structures for producers reliant on scrap feedstocks. Our report details how these regulatory shifts are segmenting regional markets and altering competitive advantages for key players.
Competitive Landscape Overview
The steel round bars market features a diverse mix of global giants and specialized regional distributors, creating a multifaceted competitive environment. Consolidation metrics indicate a moderately concentrated market, with the top three companies holding approximately 38.5 percent of the share, while the top five account for 45.2 percent. This structure suggests that while large players drive significant volume, there remains ample room for niche operators to compete on service, specification, and regional availability.
Leading global entities such as Nucor Corporation and ArcelorMittal continue to anchor the market. Nucor, based in Charlotte, North Carolina, produces and supplies Merchant Bar Quality round steel bars using electric arc furnace technology with high recycled content. ArcelorMittal, headquartered in Luxembourg, operates as a global producer across carbon, stainless, and alloy grades for construction, automotive, and machinery sectors. Their strategies often set the tone for pricing and capacity utilization across regions.
In Asia, major manufacturers like Nippon Steel Corporation and Tata Steel play pivotal roles. Nippon Steel focuses on stainless and carbon round steel bars with an emphasis on high-strength grades for industrial use. Tata Steel, based in Jamshedpur, India, supplies premium round steel bars including specialized series with enhanced machinability for automotive and structural applications. POSCO, from Seoul, South Korea, also supplies round steel bars from carbon to high-alloy grades for global markets, reinforcing the region's manufacturing dominance.
European producers maintain strong positions in specialty segments. Thyssenkrupp AG provides stainless and alloy round steel bars through an integrated production and distribution network, while Outokumpu Oyj remains a leading producer of stainless steel round bars for corrosion-resistant applications in chemical, energy, and food processing. SSAB AB supplies high-strength round steel bars specifically for heavy equipment and construction, catering to demanding engineering requirements.
The Americas host a robust network of distributors and specialized suppliers. Eaton Steel Bar Company in Cleveland specializes in hot-rolled and cold-drawn round steel bars for defense and heavy industry. Gerdau S.A., based in Sao Paulo, manufactures merchant bar quality round steel bars for structural and industrial uses. US-based entities such as Jade Sterling Steel, Chatham Steel, Ohio Bar & Metal, North Shore Steel, Summit Steel Corp, and TW Metals provide critical distribution and processing services, often catering to specific ASTM specifications or defense-related needs. Smaller specialized producers like Virwadia Steels and Vishwa Stainless Pvt. Ltd. in India further diversify the supply base for stainless grades.
Report Scope and Functional Analysis
The complete PW Consulting market study offers significantly more depth than the high-level overview provided here. It delivers a navigational map of the steel round bars ecosystem, breaking down performance metrics without exposing every sensitive figure in this public summary. The report is engineered for practical application by strategy teams, procurement officers, and investors who need actionable intelligence rather than generic trends.
Structural Steel Market
Key components of the full document include a detailed segmentation analysis that isolates performance drivers across different material types and end-use industries. The study examines how specific grade requirements influence supply chain decisions and pricing power. It also provides a comprehensive regional breakdown, evaluating how local industrial policies, infrastructure spending, and manufacturing capacity affect market penetration and growth potential in different geographies.
Segmentation Drivers and Technology Trends
Understanding the split between material types is crucial for sourcing strategies. The market encompasses carbon steel, alloy steel, and stainless steel round bars, each serving distinct functional requirements. Carbon steel remains a workhorse for general structural and industrial applications, while alloy steel offers enhanced mechanical properties for specialized machinery. Stainless steel caters to environments requiring corrosion resistance, such as chemical processing and food manufacturing.
Technological advancements in production methods are also reshaping the landscape. The shift toward electric arc furnace technology, as utilized by producers like Nucor, emphasizes sustainability through high recycled content. This aligns with broader environmental, social, and governance (ESG) mandates that are increasingly influencing procurement decisions. The report analyzes how green manufacturing initiatives are impacting cost structures and customer preference patterns across major consuming sectors.
Regional Nuances and Application Sectors
Regional dynamics vary significantly due to local infrastructure projects, automotive production rates, and energy sector activities. The study provides insights into how regions like North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa are performing relative to global averages. It examines the flow of materials across borders and how tariffs, such as those recently adjusted by Norfolk Southern, impact inland logistics and final delivery costs.
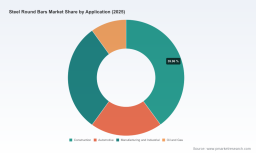
Application-wise, the market serves construction, automotive, manufacturing and industrial, and oil and gas sectors. Each vertical presents unique demand cycles and specification requirements. Construction demand is often tied to government infrastructure spending, while automotive and manufacturing sectors are more sensitive to economic cycles and consumer demand. The oil and gas segment relies heavily on high-grade materials capable of withstanding extreme conditions. The full report delineates how these sectors interact with supply constraints and price volatility.
Strategic Recommendations for Stakeholders
Given the projected market size and growth rate, stakeholders must adopt proactive strategies rather than reactive measures. Procurement teams should consider hedging against raw material price volatility, especially in light of recent billet and iron ore price movements. Diversifying supplier bases across different regions can mitigate risks associated with localized trade restrictions or logistical bottlenecks.
For investors and competitors, monitoring the pricing actions of major players like Nucor and Gerdau provides early signals of margin shifts. Understanding the concentration of market share among top players helps in assessing potential M&A opportunities or identifying vulnerable niche segments. The report includes scenario planning tools to help organizations model the impact of varying input costs and demand fluctuations on their bottom lines.
Steel Round Bars Market
Access to the complete dataset and proprietary analysis models is available through our full market research document. This resource provides the detailed numerical breakdowns, competitor profiling, and risk assessment frameworks necessary to make informed strategic decisions.
The steel round bars market offers substantial opportunities for those equipped with the right intelligence. By leveraging detailed insights on growth rates, competitive moves, and material dynamics, organizations can position themselves to capitalize on the projected expansion through 2032. We invite you to explore the full report to unlock the specific data points and strategic recommendations tailored to your operational needs.
For detailed analysis of this topic, please visit the official page: Steel Round Bars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


