



PW Consulting: Current Sensing Resistor Market to Reach $265.1 Million by 2032, CAGR 5.59%

Strategic Intelligence Report: The Current Sensing Resistor Market Outlook 2026–2032
As the global electronics industry accelerates toward electrification and smarter power distribution, the role of precision current sensing has evolved from a passive compliance requirement to a critical enabler of system efficiency, safety, and performance. PW Consulting presents this executive briefing on the Current Sensing Resistor Market, drawing on comprehensive historical tracking from 2020 through 2025 and detailed forward-looking projections spanning 2026 to 2032. This analysis is designed to equip strategic leaders, procurement directors, and R&D planning teams with the contextual depth needed to navigate supply chain complexities, technology transitions, and competitive shifts in the coming years.
Market Trajectory and Structural Growth Signals
The historical record from 2020 to 2025 reveals a consistent upward trajectory in global revenue for current sensing resistors, reflecting sustained capital investment in power electronics, automotive electrification, and industrial automation. After reaching a baseline level in 2020, the market steadily expanded through 2022 and 2023, driven by early-cycle adoption in automotive battery management systems and data center power infrastructure. By 2024, demand acceleration entered a more pronounced phase, with 2025 closing the historical window at a significantly elevated revenue mark.
Our forecasting model projects continued expansion through 2032, with a compound annual growth rate of 5.59 percent across the full forecast horizon. The progression from the 2025 baseline into the mid-2020s suggests that incremental capacity additions, alongside the phasing in of next-generation powertrain architectures and industrial motor drives, will sustain revenue momentum. As the timeline extends further toward the early 2030s, the growth curve reflects the compounding effect of platform migrations in electric vehicles, the scaling of renewable energy inverters, and the continuous miniaturization of high-power shunt elements. It is important to note that these are structural, ecosystem-level signals: the detailed breakdown of how this growth distributes across specific regional corridors, product architectures, and end-use verticals remains a core deliverable of the full report.
Technology Transitions and the Shift Toward High-Density Shunt Architectures
A defining theme of the 2026–2032 period is the ongoing migration from conventional thick-film platforms toward higher-performance metal-based and sintered shunt technologies. Industry data points to sintered metal current sense chip resistors achieving power dissipation levels significantly above traditional thick-film equivalents while preserving low temperature coefficient of resistance. This material-level advancement allows designers to increase current-carrying capacity within shrinking board footprints, a constraint that has become central to automotive module packaging and compact industrial power supplies.
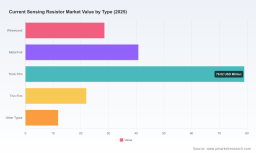
At the same time, metal foil and metal strip architectures continue to hold relevance where ultra-low TCR and long-term stability are non-negotiable, particularly in precision instrumentation and high-reliability automotive traction environments. Wirewound and thin-film solutions occupy adjacent niches, each carrying distinct trade-offs in inductance, power handling, and manufacturing economics. The strategic question for component engineers is no longer which technology dominates in absolute terms, but rather which platform aligns with a given application's thermal, electrical, and qualification requirements at acceptable total cost of ownership. The complete study maps these technology trade-offs against actual design requirements and quantifies the relative revenue share each type commands across the broader product landscape.
Competitive Landscape: Differentiation Through Qualification and Platform Strategy
The current sensing resistor market remains moderately fragmented, with top-three concentration levels indicating that while scale players exert meaningful influence, specialized mid-tier manufacturers retain significant footholds through technical differentiation and regional distribution strength. The competitive battleground has shifted decisively from pure price competition toward qualification readiness, power-density innovation, and application-specific portfolio breadth.
Bourns, Inc. has reinforced its automotive and power electronics positioning with the launch of its CSS4C-1216 Series 4-terminal current sense resistors, designed to meet AEC-Q200 expectations with up to 5 watts of power handling, low inductance, and a compact form factor. This family complements the company's Riedon shunt portfolio, which spans metal strip and thick-film elements tailored for EV battery management and industrial power conversion. In parallel, Vishay Intertechnology, Inc. has expanded its Power Metal Strip lineage with the WSLF1206 and WSBE families, delivering 5-watt capability within a 1206 footprint while maintaining low resistance values optimized for high-efficiency EV power systems and board-space-sensitive designs.
ROHM Co., Ltd. has drawn attention with its UCR10C Series sintered metal shunt resistors, which push rated power to 1.25 W within a 2012 metric size and carry AEC-Q100 qualification for automotive motor control and power electronics applications. This product direction underscores a broader industry trend toward sintered metal platforms as credible alternatives to traditional thick-film offerings in thermally constrained environments. TT Electronics has similarly advanced its SMT shunt portfolio with the LRMAK Series, a 4-terminal family qualified to AEC-Q200 standards, offering resistances down to 500 µΩ and up to 2 watts of power for automotive motor control and industrial current sensing.
Beyond these headline developments, the competitive fabric includes Ohmite Manufacturing Co., whose LVK and PCS Series address low-resistance, high-power, and chip current sense applications with precision thick-film and metal implementations. TE Connectivity Ltd. contributes CGS Series metal chip resistors and high-current shunts positioned for automotive and industrial sensing architectures. KOA Speer Electronics, Inc. maintains a focus on precision low-ohm applications through its KDV and PSJ2 Series metal film and power shunt offerings, while Caddock Electronics, Inc. emphasizes accuracy and stability in precision thick-film current sense resistors intended for instrumentation and power monitoring. In the European precision segment, Isabellenhütte Heusler GmbH & Co. KG supplies precision shunt resistors and metal-based current sensors engineered for high-accuracy demands in EV and power electronics environments.
Collectively, these players illustrate a market where product qualifications, package density, and application-specific support are becoming the primary vectors of differentiation. The full report provides a deeper comparative assessment of competitive positioning, recent product cadence, and the strategic implications of these launches for procurement prioritization and second-source planning.
Regulatory, Qualification, and Supply Chain Considerations as Strategic Filters
Automotive-grade qualification has emerged as one of the most consequential filters shaping demand patterns in the current sensing resistor segment. AEC-Q200 compliance is no longer a peripheral bonus; it is increasingly a prerequisite for participation in EV battery management, traction inverter, and frequency converter designs. This qualification dynamic is visible across multiple recent product introductions, from Bourns' CSS4C-1216 family to TT Electronics' LRMAK Series and Vishay's Power Metal Strip platforms, all of which are positioned with explicit automotive reliability expectations.
Environmental and material compliance further shapes the competitive field. Recent sintered metal shunt introductions, including ROHM's UCR10C Series, are fully lead-free and RoHS compliant, with automotive-grade temperature cycle durability integrated into the product claim set. For supply chain and compliance teams, these specifications reduce integration risk in regions with stringent environmental mandates and simplify multi-source qualification where suppliers must demonstrate equivalent regulatory alignment.
On the commercial side, material cost dynamics are beginning to influence device selection decisions. The emergence of sintered metal current sense chips capable of delivering up to 2x higher power dissipation than traditional thick-film equivalents while maintaining low TCR is prompting a reevaluation of thermal derating margins and board-area budgets. As these products mature into volume production, the cost-per-watt-per-cubic-millimeter calculus may tilt in favor of advanced shunt architectures in high-power applications, even if initial unit pricing remains elevated. The complete study dissects these shifting cost-performance trade-offs and their implications for make-versus-buy, design-in prioritization, and inventory strategy.
Current Sensing Resistor Market
Worldwide Precision Resistors Market
Findings and the Strategic Case for Detailed Market Intelligence
A market growing at a mid-single-digit CAGR over a seven-year horizon does not move by accident. It is propelled by interlocking forces: electrification roadmaps in automotive original equipment manufacturing, the scaling of industrial motor drives and renewable inverters, the push for higher power density in consumer and telecommunications power supplies, and the relentless requirement for more accurate current measurement in closed-loop control architectures. Each of these forces exerts a distinct pull on product type selection, qualification requirements, and regional sourcing patterns.
Yet the headline market trajectory only tells part of the story. The strategic decisions that separate resilient portfolios from vulnerable ones depend on operational intelligence: which product types are gaining share in which applications, how regional demand differs in cadence and qualification emphasis, which manufacturers are converting product launches into validated design wins, and how material and qualification constraints will reshape total cost structures. These are precisely the dimensions that our full Current Sensing Resistor Market research unpacks with granular segmentation, revenue allocations, and forward-looking scenario modeling.
For procurement leaders, the value lies in anticipating qualification shifts, identifying credible second sources before supply constraints materialize, and understanding where thermal-performance breakthroughs are likely to displace incumbents. For R&D and application engineering teams, the value lies in mapping technology trade-offs to actual system requirements and avoiding over-investment in architectures that are losing share in key verticals. For executive planning teams, the value lies in aligning capacity, tooling, and supplier relationships to the demand waves that the forecast period will bring.
PW Consulting's full market study transforms these strategic questions into structured answers. It integrates historical performance, projected revenue paths, segmentation detail across resin types, applications, and regional demand centers, and a competitive profile of the manufacturers reshaping the segment. The report is designed to be immediately usable: a reference foundation for design-in strategy, supplier evaluation, pricing negotiations, and long-range capacity planning.
To access the complete segmentation detail, competitive benchmarking, and full forecast tables that underpin this briefing, please visit the PW Consulting market research portal. The full edition extends well beyond these introductory findings, providing the quantitative and qualitative depth required to convert market trajectory into actionable corporate strategy.
For detailed analysis of this topic, please visit the official page: Current Sensing Resistor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


