



PW Consulting: Face Recognition Market Hits $3.65B in 2025, Projects 14.5% CAGR to $9.36B by 2032

Navigating the Face Recognition Systems Market: Strategic Intelligence for Enterprise Decision-Makers in 2026
Executive Perspective
The face recognition systems market has transitioned from an emerging technology category into a foundational infrastructure layer for enterprise security, identity verification, and operational efficiency. As organizations across sectors reassess their technology portfolios in the wake of shifting regulatory frameworks and accelerated AI maturity, the need for precise, forward-looking market intelligence has never been more critical. This industry insight introduces our latest comprehensive study on the Face Recognition Systems Market, a research product designed specifically for executives who must align technology investment with strategic growth trajectories through 2032.
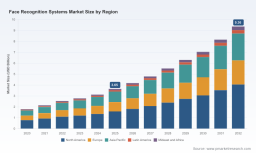
The macroeconomic trajectory underscores the magnitude of this opportunity. From a base valuation of $3.65 billion in 2025, the market is projected to exceed $9.36 billion by 2032, expanding at a compound annual growth rate of 14.5 percent. These figures represent more than raw revenue projections; they signal a structural shift in how enterprises deploy biometric identification, allocate capital toward hardware-software integration, and navigate an increasingly complex competitive landscape. The research accompanying this overview translates these high-level trends into actionable intelligence, enabling leadership teams to separate signal from noise and make informed commitments in a crowded technology ecosystem.
Macro Demand Landscape and Growth Drivers
Market expansion over the past half-decade has been consistently robust. Revenue climbed from $1.8 billion in 2020 through successive annual increases, surpassing the $3 billion threshold by 2024 and reaching $3.65 billion at the 2025 mark. The momentum is expected to maintain its upward trajectory, with forward estimates indicating sustained double-digit growth each year through the end of the forecast window. This growth profile reflects the compounding effect of multiple reinforcing demand drivers rather than reliance on a single deployment vertical.
Enterprise adoption is being accelerated by the convergence of three core catalysts. First, organizations are prioritizing physical access control and identity verification as part of broader zero-trust security architectures. Second, public sector programs continue to expand facial recognition deployments for border management, law enforcement support, and national identity initiatives, creating durable procurement pipelines that stimulate both hardware and software innovation. Third, algorithmic accuracy improvements, supported by standardized evaluation frameworks and computational advances, are lowering the perceived risk profile for enterprise consumers who previously hesitated due to performance or demographic bias concerns.
Hardware and computational requirements add another layer of strategic consideration for procurement teams. High-accuracy identification workflows increasingly depend on GPU or NPU acceleration to sustain performance at scale, while CPU-only configurations are generally constrained to lightweight models with reduced matching fidelity. Understanding where a given deployment falls on this hardware spectrum directly affects total cost of ownership, integration timelines, and long-term scalability. Our research examines these technical interdependencies in detail, providing IT architects and procurement leaders with the context needed to evaluate vendor proposals against realistic infrastructure assumptions.
Regulatory Architecture and Compliance Realities
Any forward-looking market strategy must account for the evolving regulatory environment that shapes procurement approvals, deployment boundaries, and data governance obligations. Regulatory activity across major jurisdictions has intensified, and the cumulative effect is reshaping how vendors position their platforms and how enterprises structure their risk assessments.
In the United States, the Facial Recognition Act of 2025 requires law enforcement agencies using facial recognition technology to undergo annual accuracy and bias testing conducted by NIST, establishing a new baseline for accountability in public sector deployments. State-level mandates add further complexity, such as Virginia law requiring approval for facial recognition technology utilization by local governments, effective July 1, 2026. These domestic requirements create a patchwork that enterprise vendors must navigate carefully, particularly when offering cross-jurisdictional services or multi-agency platforms.
International frameworks introduce additional compliance dimensions. The European Union AI Act classifies real-time facial recognition in public spaces for law enforcement as high-risk, with prohibitions unless authorized for important public security reasons, effectively shaping market participation rules for vendors operating in or serving EU territories. Meanwhile, China's Provisions on Security Management in the Application of Facial Recognition Technology took effect June 1, 2025, establishing data security requirements that influence product design, data handling protocols, and partnership structures within one of the world's largest deployment markets.
Our analysis treats regulatory dynamics not as peripheral background information but as strategic variables that affect pricing power, go-to-market timelines, and competitive differentiation. Companies that integrate compliance readiness into their product roadmaps and contract structures can convert regulatory complexity into barriers to entry, while those that treat it as an afterthought risk stalled deployments and reputational exposure.
Competitive Field and Differentiation Vectors
The competitive environment reflects a mix of specialized biometric technology providers, large industrial technology firms, and AI-native algorithm developers. Market concentration remains pronounced, which has direct implications for procurement leverage, partnership options, and the feasibility of vendor diversification strategies. Understanding the positioning of leading players helps organizations assess where consolidation pressure is strongest and where niche differentiation still creates room for specialized suppliers.
Several firms illustrate the diversity of competitive strategies currently shaping the market. Clearview AI provides facial recognition platforms and commercial access to large-scale image databases for law enforcement, border control, and investigative applications. Its recent track record includes a one-year contract valued at $225,000 with U.S. Customs and Border Protection for facial recognition services in border screening and tactical targeting, alongside a SOC 2 attestation with zero exceptions validating data security and privacy standards. These developments reflect a dual emphasis on operational scale and compliance credibility.
Face Recognition Device Market
NEC Corporation offers NeoFace facial recognition systems and platforms for public safety, law enforcement, and national ID programs. Its technology has been recognized as ranked the world's most accurate in the latest NIST FRTE 1:N identification test using a 12 million person database, an achievement that highlights the competitive importance of benchmark performance in government and high-stakes enterprise procurement. IDEMIA, headquartered in Paris, delivers biometric identification solutions including facial recognition for border control, law enforcement, and government identity programs, while Thales Group provides facial recognition and biometric systems for law enforcement, aviation security, and public safety applications. These two European-based organizations underscore the strategic role of government-adjacent identity infrastructure in sustained demand.
On the industrial and machine vision side, Cognex Corporation manufactures and sells machine vision and 3D vision systems integrated with facial recognition for industrial, security, and access control uses, demonstrating how recognition capability is increasingly embedded within broader automation ecosystems. Panasonic supplies facial recognition hardware and software solutions for surveillance, access control, and border security, reinforcing the hardware-software integration thesis across multiple deployment settings.
AI-native companies are pursuing differentiation through algorithmic precision and responsible deployment framing. Paravision develops and commercializes AI-powered facial recognition algorithms optimized for accuracy and ethical deployment in enterprise and security sectors, a positioning that aligns with growing procurement emphasis on bias performance and governance assurances. On the Asia-Pacific side, SenseTime Group offers facial recognition and AI vision systems deployed in smart cities, law enforcement, and public security applications, while Megvii Technology develops Face++ facial recognition technology and platforms for identity verification, security, and commercial use. Both illustrate how regional deployment ecosystems and large-scale public security programs shape product roadmaps and commercial scale.
Testing Benchmarks and Performance Standards as Market Signals
Independent evaluation frameworks increasingly function as market signals that influence purchasing decisions, vendor comparisons, and product development priorities. NIST activity in 2026 underscores the centrality of standardized testing to market confidence. In January 2026, NIST issued an FRTE 1:1 report with comprehensive accuracy metrics including demographic performance and provisional duration updates for algorithms submitted since September 2025. In May 2026, NIST released an updated FRTE 1:1 Verification report with participation statistics and performance benchmarks across algorithms. These recurring updates give procurement teams and technical evaluators a structured basis for comparing vendor claims against reproducible performance data.
For enterprise strategists, benchmark performance is not merely a technical metric; it is a procurement catalyst that can shorten evaluation cycles, support internal approval processes, and reduce perceived deployment risk. At the same time, performance claims must be evaluated in the context of specific use cases, population demographics, environmental conditions, and matching configurations. Our research dissects how testing outcomes translate into commercial messaging, where benchmark leadership translates into procurement advantage, and where gaps between test conditions and operational realities create opportunities for differentiated positioning.
Applied Deployment Domains and Segment Considerations
Demand is distributed across multiple functional applications, each with distinct performance requirements, procurement rhythms, and integration constraints. Access control remains a dominant use case, driven by organizations seeking to replace or augment physical credentialing systems with biometric verification that reduces credential leakage and streamlines entry workflows. Security and surveillance applications extend recognition capability into broader monitoring and situational awareness contexts, where throughput, false-positive tolerance, and operator support requirements shape system selection. Face identification use cases, including 1:1 verification and 1:N identification workflows, introduce different computational demands and accuracy expectations, and they often intersect with compliance frameworks that vary by jurisdiction and end-user type.
Technology architecture choices further influence competitive positioning and procurement decisions. Decision-makers must evaluate the trade-offs across recognition modalities and understand how each maps to cost, accuracy, and deployment environment. The shift from single-modality deployments to multi-layered recognition strategies is becoming more visible as organizations seek redundancy, improved resilience, and broader coverage across lighting, distance, and pose variation conditions. Segmentation choices also affect hardware procurement, integration complexity, and long-term maintenance commitments, all of which should be factored into enterprise budgeting and vendor evaluation.
What the Research Delivers
This study is structured to provide executive and technical audiences with actionable intelligence rather than abstracted trend summaries. The report combines quantified market sizing, forward forecasts, and segment-level analysis with qualitative assessments of competitive behavior, regulatory exposure, and technology adoption patterns. Readers will find detailed coverage of demand drivers, deployment contexts, hardware and algorithmic considerations, and the strategic implications of benchmark performance and compliance requirements.
The analysis is designed to support multiple decision contexts. Product leaders can use the findings to align roadmaps with demand concentration and performance expectations. Procurement teams can leverage the competitive and segment analysis to sharpen evaluation criteria and negotiation positioning. Investment and strategy functions can draw on the forecast trajectory and market concentration insights to assess growth pathways and consolidation risk. Policy-aware organizations can use the regulatory mapping to anticipate approval friction, data handling obligations, and the operational implications of jurisdiction-specific mandates.
Strategic Imperatives for 2026 and Beyond
The face recognition systems market presents a rare combination of expanding demand, performance-driven competition, and regulatory recalibration. For enterprises planning capital allocation and technology strategy in 2026, the strategic question is not whether facial recognition will continue to gain adoption, but how to engage with the market in a way that balances growth opportunity against compliance exposure, integration complexity, and competitive dependency.
Face Recognition Systems Market
Organizations that approach this market with structured intelligence can make more disciplined choices about vendor selection, deployment sequencing, hardware investment, and compliance readiness. They can also better anticipate where consolidation, benchmark leadership, and regulatory pressure will reshape supplier dynamics over the next several years. The full study expands on these themes with detailed market projections, segment analysis, competitive profiling, and scenario considerations intended to support concrete planning decisions.
This overview has been crafted to provide a credible, professional foundation for understanding the market's direction and the strategic stakes involved. To access the complete dataset, segment-level breakdowns, competitive mapping, and forward forecasts that support enterprise planning through 2032, we invite decision-makers to consult the full market research publication.
For detailed analysis of this topic, please visit the official page: Face Recognition Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


