



PW Consulting: APU Market Hits $200M in 2025, Projected 5.2% CAGR Through 2032

Strategic Imperatives in the Aircraft Auxiliary Power Unit Market: Navigating Growth and Innovation Through 2032
The global aviation landscape is undergoing a profound transformation. As airlines balance operational efficiency with rigorous environmental mandates, the Aircraft Auxiliary Power Unit (APU) has emerged as a critical component in the aerospace value chain. Far more than a simple engine starter, the modern APU serves as a versatile energy hub, providing bleed air, electrical power, and engine starting capabilities essential for ground operations and emergency backup in flight. For strategic decision-makers, understanding the trajectory of this market is no longer optional; it is a prerequisite for capitalizing on upcoming shifts in manufacturing, aftermarket services, and technological integration.
PW Consulting's latest comprehensive analysis, Aircraft Auxiliary Power Unit (APU) Market , offers a detailed roadmap of this sector from a base year of 2025 through a forecast period extending to 2032. This report is designed not merely as a statistical digest but as an actionable intelligence tool. It synthesizes historical performance data with forward-looking projections to help stakeholders navigate an environment defined by consolidation, regulatory pressure, and rapid technological evolution. The following overview highlights the strategic value embedded within this research, illustrating why it is essential reading for executives in aerospace manufacturing, aviation services, and investment firms.
Market Trajectory and Quantitative Context
Understanding the scale and momentum of the APU market provides the foundation for any strategic planning exercise. Over the historical period spanning 2020 to 2025, the industry demonstrated resilience and steady expansion despite global supply chain disruptions and fluctuating flight volumes. The market valuation in 2020 stood at 150.0 million USD, reflecting the initial impact of reduced travel demand. However, recovery drove valuations upward, reaching 158.35 million USD in 2021 and climbing to 172.38 million USD in 2022. By 2023, the market had surpassed the 180 million USD threshold, recording 184.45 million USD, before settling at 186.62 million USD in 2024 as manufacturers optimized production schedules.
The base year of 2025 marks a significant inflection point, with the market reaching 200.0 million USD. This milestone underscores the renewed confidence in aviation infrastructure and the increasing reliance on reliable auxiliary power systems for both new aircraft deliveries and fleet sustainment. Looking ahead, the forecast period from 2026 to 2032 projects sustained growth. The year 2026 is anticipated to open at 206.33 million USD, followed by progressive increments leading to 219.7 million USD in 2027 and 224.92 million USD in 2028. As the decade progresses, the valuation is expected to approach 234.8 million USD by 2029 and cross the 255.1 million USD mark by 2030. The final years of the forecast horizon show the market stabilizing near its peak potential, with projections of 268.5 million USD in 2031 and 270.0 million USD in 2032.
This growth trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 5.2 percent over the forecast period. While this rate indicates steady expansion, it also masks the underlying complexities of regional performance, technological shifts, and competitive dynamics that drive the aggregate number. Stakeholders must look beyond the headline figures to understand where value is being created and how to position their portfolios accordingly.
Segmentation Dynamics and Structural Shifts
The APU market is not a monolith. It is segmented by type, application, and geography, each presenting distinct opportunities and challenges. Our analysis delves into the nuanced performance of these segments without merely presenting isolated percentages. Instead, we examine the structural forces reshaping demand.
In terms of technology, the market is currently anchored by traditional gas turbine solutions, which continue to dominate due to their proven reliability and high power-to-weight ratios in established airframe configurations. However, the research highlights a gradual but decisive shift toward alternative propulsion technologies. Electric and fuel cell-based APU concepts are gaining traction, driven by the industry's decarbonization goals and the specific needs of newer aircraft designs. The interplay between legacy gas turbine offerings and emerging electric architectures is a key theme explored in depth, providing insights into where R&D investments should be directed to future-proof product lines.
Application-wise, commercial aviation remains the primary driver of volume, reflecting the sheer scale of the global passenger fleet. Military aviation represents a specialized but high-value segment, often characterized by stringent performance requirements and long-term support contracts. Business and general aviation contribute additional layers of demand, often serving as early adopters of new technologies or niche configurations. Understanding the relative weight and growth characteristics of these applications is vital for companies deciding whether to focus on high-volume commercial platforms or high-margin specialized military and business jet solutions.
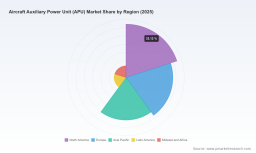
Geographically, the market exhibits a diversified footprint. North America, Europe, and Asia Pacific represent the bulk of revenue generation, reflecting the concentration of aircraft manufacturers, major operators, and maintenance hubs in these regions. Latin America and the Middle East and Africa also contribute to the global total, often linked to specific fleet modernization programs or growing regional connectivity. The report provides a granular view of how regional procurement cycles, fleet age profiles, and local regulatory environments influence revenue streams, enabling clients to tailor their market entry or expansion strategies with precision.
Competitive Landscape and Strategic Consolidation
The APU market is characterized by a high degree of concentration. Market data indicates that the top three competitors hold a combined share of approximately 55.0 percent, while the top five players command around 70.0 percent. This oligopolistic structure suggests that barriers to entry are significant, particularly in the civil sector where certification hurdles are substantial. In fact, industry data confirms that only four companies worldwide are currently authorized to develop and certify civil APUs, creating a tightly controlled environment for new market entrants.
Several key players define the current competitive arena. Pratt & Whitney, headquartered in East Hartford, Connecticut, maintains a robust portfolio including the APS5000 all-electric series, APS3200, PW980, and APS2100. Their strategic movements are closely watched, particularly their recent cooperation agreement signed in September 2025 with PBS Group to develop next-generation APUs with the highest power density and reduced form factors for both civil and military aviation. This collaboration signals a clear intent to lead in efficiency and compactness. Furthermore, the March 2026 supply agreement between VSE Aviation and Pratt & Whitney Canada for over 2,500 aftermarket parts covering APS1000, APS2000, and APS2100 units highlights the enduring value of the aftermarket ecosystem and the importance of long-term distribution partnerships.
Honeywell International Inc., based in Charlotte, North Carolina, remains a formidable competitor with its GTCP series, including the GTCP331 and HGT1700, as well as the 36-150 and Micro Power Unit lines. Honeywell's selection of the 36-150 APU by Bell Textron for the Future Long-Range Assault Aircraft (FLRAA) program in June 2025 demonstrates the company's ability to secure critical platforms in the defense sector, reinforcing its position as a provider of mission-critical power solutions.
Safran Power Units, located in Bordeaux, France, continues to leverage its SPU series for both civil and military aircraft. The company's expansion of its partnership with Lufthansa Technik in October 2025 for APU generator maintenance and overhaul on Airbus A320 aircraft illustrates the growing emphasis on integrated maintenance solutions and lifecycle support. This trend toward closer collaboration between OEMs and MRO providers is a recurring theme that affects margin structures and customer lock-in strategies across the industry.
Other notable entities include PBS Aerospace in Prague, known for its APU systems from Velká Bíteš; Kinetics Ltd. in Israel, focusing on auxiliary power units for military applications; AEGIS Power Systems, Inc. in the United States, specializing in aircraft power supplies and related APU components; and AMETEK Airtechnology in the United Kingdom, which is pushing boundaries with hydrogen-powered APU thermal management and electric power units. The presence of these diverse players underscores the breadth of innovation occurring across different technologies and end-use sectors.
Aircraft Auxiliary Power Unit (APU) Market
Industry Dynamics and Regulatory Catalysts
Market growth does not occur in a vacuum. It is shaped by a complex web of regulatory requirements, material cost fluctuations, and airframe design changes. One of the most significant regulatory pressures currently affecting the industry is the phase-out of Halon in airplane applications per ICAO deadlines. This transition forces manufacturers and operators to seek alternative fire suppression and cooling solutions within APU systems, driving design modifications and potentially altering component costs. The FAA Q1 2026 Transport Airplane Issues List highlights this issue alongside special conditions introduced by Airbus and Boeing for automatic speed protection systems that reduce airplane structural loads. These airframe-level changes can indirectly influence APU requirements, particularly regarding mounting, vibration tolerance, and integration with flight control systems.
On the material and manufacturing front, the adoption of additive manufacturing for hot-section components is yielding tangible benefits. Sector analysis from 2025 indicates that this technology has reduced APU part lead times by 15 to 25 percent and lowered inventory requirements. For operators, this translates to improved fleet availability and reduced downtime. For manufacturers, it offers a pathway to optimize supply chains and respond more rapidly to aftermarket demand. However, the integration of additive manufacturing also raises questions about certification standards, quality control, and long-term durability, all of which are examined in the report.
Auxiliary Power Units (APU) Market
The concentration of certification authority in the hands of a few entities adds another layer of strategic consideration. Companies must navigate a rigorous approval process to bring new civil APUs to market. This reality favors established players with deep regulatory expertise and long-standing relationships with certification bodies, while also creating opportunities for partnerships that can share the burden of compliance. The report explores how these dynamics influence competitive positioning and the pace of innovation.
Operational and Financial Implications for Decision-Makers
For executives and investors, the APU market presents a mix of steady revenue streams and pockets of high growth potential. The aftermarket segment, in particular, offers recurring revenue opportunities tied to the extensive operational life of aircraft fleets. With thousands of units in service and ongoing support agreements, the lifecycle value of an APU extends far beyond the initial sale. Companies that can secure exclusive distribution rights or forge strong MRO partnerships, as seen in recent developments, are well-positioned to capture a disproportionate share of this value.
Conversely, the transition toward electric and hydrogen-based technologies introduces uncertainty and opportunity in equal measure. Early movers in these areas may gain competitive advantages, but they also face higher R&D costs and the risk of shifting standards. The report assesses the maturity of these technologies, the likely adoption timelines, and the potential impact on incumbent gas turbine markets. This analysis helps clients evaluate whether to invest in incremental improvements to existing platforms or to pursue disruptive innovations that could reshape the market landscape.
Cost management is another critical area. Material costs, supply chain resilience, and manufacturing efficiency all play a role in determining profitability. The insights on additive manufacturing and inventory optimization provide actionable levers for reducing operational expenses. Additionally, understanding regional variations in demand and regulatory requirements enables more accurate capacity planning and resource allocation.
What the Full Report Delivers
The Aircraft Auxiliary Power Unit (APU) Market research publication is structured to provide a holistic view of the industry. Beyond the high-level market sizing and trajectory discussed here, the full report contains detailed segmentation analysis, competitive benchmarking, and scenario-based forecasting. Readers will find comprehensive profiles of key companies, including their strategic positioning, product portfolios, and recent developments. The report also examines the interplay between airframe manufacturers, airlines, defense contractors, and regulatory bodies, offering a 360-degree perspective on the forces shaping the market.
Specific deliverables include an in-depth examination of type-based segmentation, covering gas turbine, electric, and fuel cell technologies, with analysis of their respective growth drivers and constraints. Application-based analysis breaks down demand across commercial, military, business, and general aviation, highlighting the unique requirements and revenue characteristics of each segment. Regional analysis provides a nuanced view of market performance across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, factoring in local fleet dynamics and procurement trends.
Furthermore, the report includes a thorough assessment of market concentration, analyzing the market share held by leading players and the implications for competition and pricing. It also explores the impact of recent developments, such as cooperation agreements, supply contracts, and technology selections, to illustrate how strategic moves are reshaping the competitive landscape. Regulatory and technical factors are woven throughout the analysis, ensuring that readers have a complete understanding of the external environment in which they operate.
Conclusion: Actionable Intelligence for a Complex Market
The Aircraft Auxiliary Power Unit market stands at a crossroads. Steady demand from commercial and military fleets provides a solid foundation for growth, while environmental regulations and technological advancements are pushing the industry toward new paradigms. Success in this environment requires more than a surface-level understanding of market size and CAGR. It demands a deep appreciation of segmentation dynamics, competitive pressures, regulatory constraints, and the evolving nature of value capture across the product lifecycle.
PW Consulting's comprehensive market research equips stakeholders with the knowledge needed to make informed decisions. Whether the goal is to identify new market entry opportunities, optimize existing product lines, forge strategic partnerships, or assess investment potential, the report delivers the granular insights necessary to navigate complexity and seize opportunity. The data presented in this preview serves as a reminder of the scale and momentum of the sector, but the full intelligence contained in the report is essential for translating that momentum into actionable strategy.
For organizations committed to staying ahead in the aerospace sector, this research represents a vital resource. It bridges the gap between broad market trends and specific operational decisions, providing the clarity needed to thrive in a competitive and rapidly changing industry. We invite readers to explore the complete analysis to unlock the full strategic potential of the APU market outlook through 2032.
For detailed analysis of this topic, please visit the official page: Aircraft Auxiliary Power Unit (APU) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


