



PW Consulting: Edge Protection System Market to Reach $344.8M by 2032

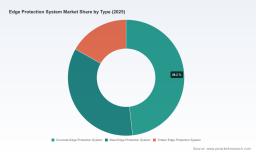
Strategic Imperatives in the Edge Protection System Market: A 2026 Outlook
Executive Summary: The Case for Precision Intelligence
As the global construction sector enters a phase of recalibrated growth, the Edge Protection System Market stands at the intersection of regulatory tightening, material cost volatility, and evolving site safety expectations. For corporate strategists, procurement leaders, and risk management executives, navigating this landscape requires more than generalized trends. It demands a structured, forward-looking view of how market size trajectories, segment performance, and competitive positioning will unfold through the end of the decade.
Our latest Edge Protection System Market research has been designed specifically for 2026 decision-making. It converts historical performance data, forecast modeling, and competitive intelligence into an actionable framework that supports capital allocation, supplier negotiation, product development prioritization, and geographic expansion strategies. This article serves as a strategic preview of the report's scope, analytical depth, and practical utility, while preserving the full dataset and granular breakdowns for clients who require it.
From Retrospective Tracking to Forward-Looking Strategy
Over the historical window of 2020 through 2025, the market demonstrated steady expansion supported by sustained demand for temporary work-at-height safety solutions across commercial, infrastructure, and industrial projects. Revenue moved from approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025, reflecting a pattern of resilient demand even as contractors navigated supply chain disruptions, labor constraints, and shifting project pipelines.
Looking ahead to the forecast period of 2026 through 2032, the market is projected to continue its upward arc, reaching an estimated 344.8 million USD by 2032. This trajectory implies a compound annual growth rate of 6.98 percent, a pace that signals more than cyclical recovery. It points to structural demand drivers tied to stricter site safety enforcement, increased adoption of modular and integrated protection solutions, and growing contractor emphasis on reducing on-site incident exposure.
For strategists, the significance of this growth path lies not only in its direction but in its composition. Growth is unlikely to be distributed evenly across product categories, end-use verticals, or geographies. Some segments will benefit from regulatory momentum and specification-driven purchasing. Others will face margin pressure from raw material cost volatility and intensifying competition. Understanding where value is created, where pricing power is eroding, and where adoption is accelerating is precisely the kind of intelligence that separates reactive planning from proactive positioning.
Edge Protection System Market
Why 2026 Decisions Require Segment-Level Clarity
The market's evolution through 2026 and beyond will be shaped by a combination of technical, regulatory, and commercial forces. Several dynamics deserve close attention as companies frame their near-term strategy:
- Regulatory and standards evolution is reshaping specification behavior. Updated product specification and test methods for temporary edge protection systems are elevating expectations around energy absorption, arrest functions, and performance verification. These changes are not abstract compliance issues; they influence which systems can be specified on demanding projects, how manufacturers differentiate their offerings, and how quickly new designs can gain market acceptance.
- Material cost pressure continues to affect installed economics. High steel and timber costs remain a relevant factor in the total installed cost of edge protection systems across global markets. For contractors and distributors, this affects bid pricing, supplier selection, and the attractiveness of alternative system designs. For manufacturers, it reinforces the importance of engineered efficiency, reusable components, and total-cost-of-ownership messaging.
- Safety adoption is increasingly linked to project procurement logic. In several major construction markets, temporary edge protection is no longer treated as an optional add-on but as a baseline expectation embedded in contractor qualifications, site planning, and insurance considerations. This shift expands addressable demand but also raises the competitive bar for product reliability, deployment speed, and integration with formwork or scaffolding workflows.
- Competitive intensity is rising among established and specialist players. The market remains relatively fragmented at the top, with a concentrated group of leading firms holding meaningful but not dominant share. That structure creates room for differentiation through product innovation, regional service capability, and partnership-driven distribution, while also making margin defense more dependent on value proposition than on scale alone.
Each of these forces affects a different part of the value chain. A company evaluating its 2026 roadmap needs to know not just that demand is growing, but which solution types are gaining share, which application areas are driving specification changes, and which regions present the strongest risk-adjusted opportunities. The full report addresses those questions with structured segmentation analysis that avoids broad generalizations and instead maps where growth is concentrated and why.
Wall Protection Market
What the Research Delivers: An Operational Toolkit
This study is built to support concrete strategic actions rather than high-level observation. Its architecture is intended to help teams translate market intelligence into procurement planning, product portfolio decisions, sales targeting, and competitive benchmarking. The report includes:
- A long-horizon market size and forecast framework that traces historical performance into the 2026 to 2032 period, giving executives a consistent baseline for scenario planning and investment prioritization.
- Segment-level analysis across type, application, and region that reveals how demand patterns differ by solution category, project environment, and geographic context. This allows readers to assess which segments are most exposed to regulatory tailwinds, material cost sensitivity, or competitive crowding.
- Competitive landscape profiling of leading participants across multiple headquarters markets, with attention to product focus, system integration strategies, and the kinds of applications each company is positioned to serve.
- Recent industry developments and standards-related updates that matter for procurement timing, product conformance, and specification risk, including emerging documentation and testing expectations affecting edge protection systems.
- Market concentration context that helps frame the balance between fragmented opportunity and consolidated influence, supporting realistic assessments of bargaining power, substitution risk, and market entry difficulty.
Importantly, the report is structured to support comparison and prioritization. Rather than presenting a single narrative line, it gives decision-makers a way to test assumptions against market evidence: Which solution categories are expanding most reliably? Which end-use environments are absorbing the highest value of protection work? Where do leading suppliers appear strongest, and where are gaps still present? These are the questions that determine whether a company's 2026 plan is robust under different demand and cost scenarios.
Competitive Landscape: Differentiation in a Fragmented Market
The edge protection sector includes a diverse set of manufacturers and suppliers spanning concrete, steel, timber, and modular construction applications. The marketplace is not defined by a single dominant architecture; instead, it features several companies competing on system design, integration with formwork and scaffolding, speed of deployment, and compliance with evolving safety expectations.
Leading participants illustrate the breadth of strategic approaches in the market. Some organizations emphasize rapid-deployment edge protection systems engineered for concrete, timber frame, and steel frame applications, often aligning product design with repeatability and site efficiency. Others integrate edge protection into broader formwork and scaffolding platforms, positioning safety as part of a unified workflow rather than a standalone purchase. A further group focuses on modular or mesh-based barrier solutions, perimeter safety screens, or roof-edge applications designed for specific project conditions.
Geographic diversity is also significant. Suppliers headquartered in the United States, Germany, Austria, France, Spain, the United Kingdom, Norway, Sweden, India, and China each bring different distribution strengths, regional specification relationships, and product specialization. In practice, this means the competitive picture varies by market: in some regions, integrated system providers may hold an advantage through incumbent project relationships; in others, specialist manufacturers may compete effectively through compliance leadership, lightweight design, or adaptability to local construction methods.
Strategic relevance comes from understanding how these players are likely to respond to the next phase of market development. Companies that can combine conformance with updated testing expectations, cost-effective material engineering, and flexible deployment models are better positioned to capture specification share. At the same time, the presence of multiple capable suppliers means that buyers have increasing leverage to compare total cost, lead time, and integration fit rather than accept a narrow set of options.
Recent activity underscores how quickly the compliance and product refresh cycle is moving. Updated standards documentation and revised product catalogs have already begun to reshape how suppliers present system classes and performance characteristics. For buyers, this creates both a conformance checklist and a competitive signal: manufacturers that move promptly to align documentation, testing, and system configuration with current specifications may gain an advantage in tenders and design reviews, while slower responders risk being excluded from increasingly specification-driven projects.
Using This Intelligence for 2026 Strategy Design
The strategic value of the full report lies in its ability to connect market structure to operational choices. Depending on a company's role in the value chain, the research can support several distinct decision paths:
- For manufacturers and product developers, segment trends and regulatory developments can inform portfolio focus, engineering priorities, and the relative merit of investing in modular, integrated, or application-specific designs.
- For distributors and procurement leaders, market size paths and competitive profiles can guide supplier diversification, inventory planning, and negotiation strategy in an environment where material costs and specification requirements both matter.
- For contractors and project organizations, the report can help clarify where safety system selection influences bid competitiveness, site risk posture, and compliance readiness, especially as standards-related expectations become more explicit.
- For investors and market entrants, concentration metrics, regional differences, and the mix of established and specialist competitors provide a realistic basis for assessing where differentiation is possible and where barriers are higher.
In each case, the goal is the same: reduce uncertainty enough to make better resource decisions without overgeneralizing from aggregate totals. The macro forecast provides the direction of travel. The segmentation, competitive, and standards context explains the mechanism beneath that direction. Together, they create a more reliable foundation for planning than headline growth figures alone.
Accessing the Full Strategic View
This preview has outlined the market's direction, the forces shaping its 2026 evolution, and the competitive logic that will influence decision-making through the forecast period. It has also described the operational scope of the research and the kinds of questions it is built to answer. What it has not done is release the full segmentation data, regional breakdowns, application splits, or company-level comparisons that make the analysis directly usable for internal planning.
Those details are reserved for the complete Edge Protection System Market report. They are structured to support detailed scenario work, supplier evaluation, and segment prioritization without requiring teams to reconstruct the underlying logic from broad market summaries. For executives and analysts who need to move from directional confidence to specific action, the full report provides the evidence base required to justify investment choices, procurement strategy, and competitive positioning in the year ahead.
In a market defined by changing specifications, material cost pressure, and rising expectations for site safety performance, the most valuable intelligence is not simply that growth is occurring, but where, why, and with what competitive implications. The complete research is designed to answer those questions in a format that supports disciplined 2026 decision-making across the construction safety value chain.
For detailed analysis of this topic, please visit the official page: Edge Protection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


