



PW Consulting: Conductive Polymers Market to Hit $344.8M by 2032 at 6.98% CAGR from 2026

Industrial Metamorphosis: Navigating the Next Wave of the Conductive Polymers Market
Executive Overview: The Strategic Imperative for 2026
The conductive polymers landscape is undergoing a quiet yet profound industrial metamorphosis. Far from being a niche chemical segment, this market now sits at the intersection of advanced electronics, sustainable manufacturing, and next-generation functional materials. Our latest Conductive Polymers Market research synthesizes seven years of historical tracking alongside a seven-year forward outlook, delivering a decision-grade intelligence framework engineered specifically for corporate strategy, procurement, and R&D leadership navigating 2026 and beyond.
Market valuation has tracked a consistent upward trajectory, advancing from approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025. Our baseline projections extend this arc through 2032, positioning the market at 228.07 million USD in 2026 and climbing toward 344.8 million USD by the close of the forecast window. This translates to a compound annual growth rate of 6.98 percent across the 2026–2032 horizon. These figures are not abstract projections; they reflect structural supply chain realignments, accelerating electrification roadmaps, and the tightening integration of functional polymers into mainstream industrial architectures. Understanding where growth concentrates, which material classes command margin resilience, and how competitive dynamics are reshaping procurement leverage requires the granular dissection only our full report delivers.
Conductive Polymers Market
From Baseline to Breakthrough: Decoding the Growth Trajectory
Historical performance reveals an industry moving through phases of stabilization and acceleration. Between 2020 and 2025, the market navigated raw material volatility, regulatory recalibration, and shifting end-use demand, yet consistently expanded its revenue base. The transition from 192.63 million USD in 2023 to 205.66 million USD in 2024, followed by the 215.0 million USD mark in 2025, signals a market that has moved past cyclical recovery and into sustained expansion. Looking forward, our forecast model maps incremental but compounding gains: 238.57 million USD in 2027, 272.15 million USD in 2028, and a sharper inflection toward 273.18 million USD in 2029, ultimately accelerating to 310.23 million USD by 2030 before settling at 331.66 million USD in 2031 and 344.8 million USD in 2032.
This trajectory is not linear by accident. It reflects the cumulative effect of manufacturing automation, material performance improvements, and the broadening application footprint across industrial, electronic, and energy-adjacent sectors. The 6.98 percent CAGR serves as a strategic anchor, but the real value for decision-makers lies in understanding the velocity of adoption across material types, the regional distribution of capacity and demand, and the competitive maneuvers that will determine margin capture. Our complete analysis isolates these drivers, mapping inflection points that generic market summaries consistently overlook.
Competitive Architecture: Who Shapes the Field and How
Market Concentration and the Real Meaning of Fragmentation
The competitive structure of the conductive polymers sector presents a nuanced picture. A CR3 concentration of 25.3 percent and a CR5 concentration of 30.5 percent indicate a market that is moderately consolidated at the upper tier while remaining highly distributed across specialty producers, regional formulators, and application-focused innovators. This fragmentation is not a weakness; it is a structural feature that rewards strategic patience and penalizes undifferentiated pricing approaches. Market leaders compete less on volume alone and more on formulation precision, regulatory compliance readiness, and application-specific performance certification.
Incumbent Profiles and Strategic Positioning
- Premix Group (Finland) operates as a specialty chemicals company delivering conductive polymer compounds and concentrates engineered for ESD protection, EMI shielding, and static control across medical, automotive, electronics, defense, and packaging end markets. Their footprint illustrates how material specialization and application-side integration reinforce pricing power.
- Heraeus Epurio (Germany) remains a pioneer and manufacturer of Clevios PEDOT:PSS conductive polymers, addressing electronics, displays, smart textiles, and thin-film applications. Their technology positioning underscores the ongoing relevance of high-purity, application-tuned conductive systems in advanced manufacturing.
- Eeonyx Corporation (United States) specializes in industrial-scale conductive polymer coatings for nonwoven and woven fabrics as well as staple fibers, positioning itself at the intersection of textile engineering and functional e-textile requirements.
- Agfa-Gevaert Group (Belgium) develops and supplies ORGACON and Orgacon PEDOT-based conductive polymer materials and inks for optical films, printed electronics, and flexible electronics, reflecting the growing convergence of imaging heritage and printed-circuit functionality.
- SABIC (Saudi Arabia) contributes as a global producer of advanced conductive polymer materials, including polycarbonate blends and compounds tailored for electronics and industrial applications, highlighting how large-scale polymer platforms integrate conductive functionalities into broader material portfolios.
- Heraeus Holding (Germany) encompasses Heraeus Epurio and maintains a group-level focus on advanced conductive polymer solutions for electronics, displays, and smart textiles, signaling how parent-company scale and cross-segment coordination shape long-term capability building.
These profiles represent only the visible layer of a more complex ecosystem. Our report dissects supplier capability matrices, regional manufacturing footprints, application-specific qualification pathways, and the strategic rationale behind recent capacity and technology moves. The following recent developments illustrate the pace and direction of competitive evolution.
Recent Competitive Moves Redefining Strategic Options
- June 2025: Premix Group officially inaugurated a new US manufacturing facility producing conductive polymer compounds for medical, automotive, defense, electronics, and packaging applications. The plant integrates AI-driven automation and real-time conductivity monitoring, signaling a decisive shift toward localized production, process transparency, and quality assurance at scale.
- September 2025: Premix Group transformed its conductive polymer manufacturing operations using an AI/ML platform known as PERTTI 3.0, deploying over 20,000 historical recipes for property prediction and automated process optimization. This move demonstrates how formulation heritage and machine learning are converging to compress development cycles and reduce variability.
- September 2025: BASF SE debuted its latest high-performance conductive polymer additive grades at the K 2025 industrial exhibition, reinforcing the ongoing stream of incremental performance upgrades that reshape downstream compatibility and processing windows.
- February 2026: Heraeus Group scaled up its advanced conductive polymer footprint in China by expanding its production facility within the Shanghai Chemical Industry Park, incorporating AI-driven analytics. This expansion reflects both regional demand maturation and the strategic use of data-rich manufacturing to defend margin in high-growth geographies.
Each event carries strategic implications for procurement timing, supplier diversification, and technology roadmap alignment. The full report translates these developments into actionable scenarios, linking corporate moves to market-wide risk and opportunity mapping.
Structural Forces Shaping the 2026–2032 Horizon
Material Economics, Regulatory Architecture, and the Cost of Compliance
Conductive polymer economics do not operate in isolation. High-purity EDOT monomer used in PEDOT:PSS conductive polymers costs hundreds of euros per kilogram, creating persistent sensitivity in formulation cost structures and reinforcing the strategic value of high-yield processing and material recovery. At the same time, volatile aniline and specialty monomer prices exert medium-term pressure with acute effects concentrated in Asia Pacific manufacturing, where input cost transmission can reshape regional competitiveness and delivery economics. These dynamics mean that procurement strategy must be paired with supply chain resilience planning and formulation flexibility.
Worldwide Structural Conductive Polymer Market
Regulatory frameworks are equally consequential. Under REACH regulation, all chemicals including fillers and additives in conductive polymers must be registered to protect human and environmental health. This requirement elevates compliance from a back-office function to a competitive precondition, particularly for manufacturers targeting European and export-sensitive markets. The EU Ecodesign Directive and ESPR further require registration and restrictions on chemicals in electronics and appliances using conductive polymers, tightening the link between material selection, product certification, and market access. The interaction between regulatory timelines, formulation adjustments, and application qualification cycles creates a planning environment where foresight directly translates into commercial advantage.
Application Breadth and the Diversification Imperative
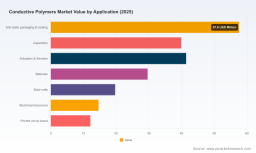
The conductive polymers value chain now stretches across a wide array of functional use cases, from anti-static packaging and coating to capacitors, actuators and sensors, batteries, solar cells, electroluminescence, and printed circuit boards. This breadth is both an opportunity and a strategic stress test. End-use diversification can cushion volatility in any single segment, but it also demands material grades, processing protocols, and qualification frameworks tailored to distinctly different performance criteria. Generalized product offerings increasingly lose relevance against application-tuned solutions that balance conductivity, mechanical properties, environmental stability, and processing compatibility. Our complete report unpacks how these application pathways diverge in growth behavior, margin structures, and competitive intensity, enabling readers to prioritize investments where the highest risk-adjusted returns emerge.
What Our Full Analysis Delivers
This article is an introduction to a deeper intelligence package. The complete Conductive Polymers Market research expands every theme introduced here into a structured, decision-ready format built for executive review, scenario planning, and cross-functional alignment. Inside the full study, leadership teams will find:
- A regionally disaggregated market view that maps demand distribution, manufacturing geography, and growth velocity across major economic zones, enabling localization strategy and supply chain prioritization without relying on aggregate assumptions.
- A material-type dissection that evaluates performance characteristics, cost drivers, and application fit across major conductive polymer classes, helping R&D and procurement teams align formulation strategy with end-use requirements and processing realities.
- An application-level analysis that tracks adoption intensity, qualification barriers, and revenue contribution patterns across functional sectors, supporting portfolio decisions in electronics, energy, automotive, medical, and industrial markets.
- A competitive landscape framework that assesses market positioning, capability differentiation, recent corporate moves, and regional expansion logic, giving strategy teams a clearer view of supplier leverage, partnership opportunities, and displacement risks.
- Integrated regulatory and raw material insights that connect compliance pathways, monomer cost behavior, and regional manufacturing sensitivities to practical planning horizons, allowing leaders to model cost scenarios and supply continuity strategies with greater confidence.
- Forward-looking scenario structures that translate historical trends and 2026–2032 projections into decision trees for capacity planning, supplier selection, and technology investment, rather than leaving the organization with a single-point forecast.
We deliberately avoid publishing the full segmentation percentages and precise regional or application-level revenue breakdowns here. Those figures are central to the report’s competitive value and are reserved for readers who need the complete dataset to support investment committee reviews, procurement negotiations, and strategic planning cycles. The excerpts and directional signals above demonstrate analytical rigor, but the full intelligence—complete with cross-segment comparisons, regional dynamics, and detailed supplier assessments—is available through the complete report.
Strategic Takeaway for 2026 Decision-Makers
The conductive polymers market is no longer defined solely by material science breakthroughs; it is being shaped by the compounding effects of manufacturing digitization, regulatory tightening, monomer cost volatility, and the expanding demand for functional materials in electronics and industrial systems. Organizations that treat this landscape as a static commodity category will misread both risk and opportunity. Those that approach it as a dynamic, application-linked ecosystem can extract meaningful advantage through supplier alignment, formulation strategy, regional capacity planning, and compliance readiness.
Our 2026–2032 outlook, built on a 6.98 percent CAGR trajectory and reinforced by recent corporate expansions, AI-integrated manufacturing, and high-performance product introductions, provides the scaffold for that strategic shift. The market is moving toward 228.07 million USD in 2026 and continues climbing through the end of the forecast window, but value capture will depend on timing, specificity, and operational execution rather than headline growth alone. For leaders who need to convert market directionality into concrete planning decisions, the complete Conductive Polymers Market research offers the depth, structure, and actionable clarity required to move from awareness to advantage.
For detailed analysis of this topic, please visit the official page: Conductive Polymers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


