



PW Consulting: Golf Tourism Market Hits $187.04M in 2025, Projected to Surge at 9.1% CAGR by 2032

The Strategic Imperative of Golf Tourism in 2026: Navigating a High-Growth Landscape
The global golf tourism industry stands at a critical inflection point. As we move beyond the post-pandemic recovery phase, the sector has transformed from a niche leisure segment into a robust economic driver with complex interdependencies across hospitality, travel services, and regional development. For executives, investors, and strategic planners, understanding the trajectory of this market is no longer optional—it is a prerequisite for capital allocation, partnership formation, and competitive positioning.
Our latest comprehensive market research on the Golf Tourism Market is designed to serve as a decision-making compass for 2026 and beyond. This article provides a preview of the analytical depth and strategic frameworks contained within the full report, highlighting the macro trends, competitive shifts, and structural dynamics that will define the industry over the next seven years.
Market Trajectory: From Recovery to Sustained Expansion
The historical data from 2020 through 2025 reveals a story of resilience and accelerating momentum. Following the disruptions of 2020, the industry demonstrated a rapid rebound, with revenue climbing steadily each subsequent year. By the base year of 2025, the global market had established a firm foundation, setting the stage for a pronounced growth phase.
Looking ahead, the forecast period from 2026 to 2032 projects a compelling expansion curve. The market is expected to deliver a compound annual growth rate of 9.1 percent, propelling total revenue from approximately 206.92 million USD in 2026 to an estimated 342.53 million USD by 2032. This trajectory signals more than just linear growth; it indicates a structural broadening of the golf tourism ecosystem, driven by new infrastructure investments, resort package innovations, and a recalibration of traveler preferences toward experiential leisure.
For corporate strategists, these figures are not merely background statistics. They represent a shifting window of opportunity. The speed of expansion suggests that market entry timing, capacity planning, and partnership agreements forged in 2026 will have disproportionate impacts on share capture by the end of the decade. Early movers who align their service portfolios with the projected demand curves will secure advantages that late entrants will struggle to replicate.
Golf Tourism Market
Key Structural Themes Shaping the Forecast
The growth narrative is underpinned by several interconnected dynamics that our research dissects in detail:
- Resort Package Expansion: The bundling of golf experiences with accommodation, dining, and leisure activities has become a primary revenue accelerator. Operators who integrate seamless stay-and-play models are capturing higher per-capita spend and longer booking windows.
- Infrastructure Investment: New course developments, modernization of existing facilities, and enhanced transport linkages are lowering barriers to access in emerging destinations, effectively enlarging the addressable market.
- Cultural and Sustainable Travel: Golf tourism is increasingly recognized as a vehicle for cultural exchange and sustainable practices. Travelers are seeking destinations that offer not only championship play but also local immersion, environmental stewardship, and community engagement.
- Operator-Dependent Booking Channels: A significant portion of golf tourism bookings continues to flow through specialized tour operators, highlighting the enduring importance of B2B distribution networks and curated travel packages.
- Government Incentives: Policy interventions, including tax breaks and targeted infrastructure support, are actively bolstering operator confidence and encouraging destination-level investment in golf tourism infrastructure.
Competitive Landscape: Diversification and Strategic Positioning
The golf tourism market is characterized by a moderately fragmented competitive structure, with a handful of leading players commanding notable but not overwhelming market shares. The top three companies collectively hold a combined market concentration of 24.5 percent, while the top five account for 28.7 percent. This concentration level suggests that while established brands retain influence, there is substantial room for regional specialists, boutique operators, and hospitality giants to differentiate through service quality, destination expertise, and digital integration.
Specialized Golf Travel Operators
A distinct tier of companies has built its identity around curated golf travel experiences. These firms compete on destination breadth, bespoke itineraries, and tournament access.
- PerryGolf operates out of Wilmington, North Carolina, and distinguishes itself through year-round golf and travel experiences spanning more than forty countries across six continents. Its value proposition blends world-class golf with iconic sightseeing and boutique accommodation, appealing to travelers who view golf as part of a broader cultural itinerary.
- Golfbreaks , headquartered in Windsor, Berkshire, focuses on customized golf breaks, holidays, and tournaments paired with 5-star resorts and online tee-time booking functionality. Its model emphasizes convenience, luxury accommodation, and the ability to organize competitive or social tournament formats.
- Your Golf Travel leverages a digital-first approach from London, offering golf holidays and breaks to over 3500 destinations across 24 countries. Its competitive edge rests on guaranteed best prices, app-based rewards, and a broad destination catalog that caters to both casual and dedicated golfers.
- Carr Golf , based in Dublin, positions itself in the premium segment with bespoke luxury golf trips tailored for Ireland, Scotland, and the world's finest golf destinations and tournaments. Its offering targets high-net-worth travelers and groups seeking personalized, high-touch service.
Hospitality and Resort Giants
Major hotel and resort groups have integrated golf into their broader leisure and business portfolios, using championship courses and tee-time access as differentiators within their brand ecosystems.
- Hilton Worldwide Holdings Inc. incorporates golf resorts and hotels with Stay and Play packages, championship courses, and tee-time access at iconic locations. Its scale and loyalty program infrastructure enable cross-selling and repeat visitation across global properties.
- Marriott International Inc. features golf resorts with championship courses, vacation packages, and amenities such as professional lessons and clubhouse dining. Its strategy emphasizes the full guest journey, from booking to on-course experience to post-round hospitality.
- Club Med SAS offers integrated golf and resort packages at all-inclusive destinations, combining on-site courses with a broader suite of leisure activities. This model appeals to families and groups seeking a self-contained vacation experience.
- Accor S.A. provides luxury resorts with direct access to prestigious golf courses under its ALL - Accor Live Limitless collection, positioning golf access as a premium perk within a larger lifestyle and hospitality brand.
- TUI Group delivers golf holidays and packages that pair hotels and villas near top courses in destinations such as Turkey, Spain, and the Algarve. Its strength lies in destination expertise, volume capabilities, and integrated travel logistics.
These competitive archetypes illustrate a market where specialization and scale coexist. Specialized operators compete on authenticity, itinerary depth, and destination knowledge, while hospitality giants leverage brand 신뢰, loyalty ecosystems, and property networks. The full report maps these competitive positions against regional demand patterns, price sensitivities, and service-level expectations to identify where strategic convergence and disruption are most likely to occur.
Industry Events and Recent Developments as Strategic Signals
Recent events in 2026 provide tangible indicators of where attention, capital, and partnerships are flowing within the golf tourism sector.
In May 2026, the European Golf Tourism Convention in Málaga City broke IAGTO records, drawing unprecedented attendance and registrations. This surge signals strong industry appetite for networking, partnership formation, and knowledge exchange in the European market. The convention's scale suggests that stakeholders are actively preparing for continued growth and are seeking structured platforms to align on standards, distribution, and destination marketing.
Earlier in the year, in March 2026, IAGTO announced that the Asia Golf Tourism Convention will head to Kuala Lumpur in 2027 as a record-setting event. This development underscores the rising strategic importance of Asia Pacific as a destination hub and a source market for golf travel. The decision to host a record-scale convention in Kuala Lumpur reflects confidence in the region's infrastructure readiness, demand growth, and potential for cross-border golf tourism collaborations.
On the operational side, January 2026 saw Hyatt announce the reopening of Secrets Playa Mujeres Golf & Spa Resort following renovation. This move highlights the ongoing investment in property refreshes and experience upgrades, reinforcing the notion that golf-adjacent hospitality assets are being positioned for premium segments that value both course quality and resort amenities.
Together, these developments paint a picture of an industry that is actively reinvesting in its physical and relational infrastructure. For decision-makers, they serve as leading indicators of where competitive intensity will rise, where new partnership opportunities may emerge, and which geographic markets are attracting disproportionate industry focus.
Strategic Considerations for 2026 Decision-Makers
The intersection of macro growth, competitive diversification, and event-driven momentum creates a complex environment for strategic planning. Our research translates these dynamics into actionable frameworks across several dimensions:
Market Entry and Expansion Timing
With the forecast indicating sustained double-digit momentum through 2032, the question for many organizations is not whether to engage with golf tourism, but how and where to deploy resources. Timing matters. Destinations and operators that secure distribution agreements, course partnerships, or resort integrations in 2026 can lock in favorable positioning before demand outpaces supply in high-growth corridors. Conversely, delayed moves risk entering markets where pricing power has shifted and customer acquisition costs have risen.
Segmentation Strategy and Value Capture
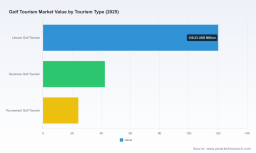
The revenue base is distributed across leisure, business, and tournament golf tourism, as well as across domestic and international tourist flows. While we do not disclose granular split percentages here, the full report provides a detailed breakdown of how these segments interact with pricing elasticity, booking lead times, and service expectations. For operators, the strategic challenge lies in aligning product offerings with the right segment mix. Leisure-focused resorts may prioritize package bundling and family-friendly amenities, while business and tournament segments may demand premium scheduling flexibility, meeting facilities, and high-touch concierge services. Understanding which segments drive margin versus volume is essential for portfolio design.
Regional Dynamics and Destination Positioning
Golf tourism demand is not evenly distributed. Certain regions benefit from established course networks, favorable climate conditions, and mature travel infrastructure, while others are accelerating due to targeted investments and policy support. Government initiatives, such as tax incentives and infrastructure programs, are actively shaping the competitive attractiveness of specific destinations. The full report evaluates how these regional factors influence inbound travel patterns, operator location decisions, and the relative bargaining power of destination marketing organizations versus private operators.
Competitive Positioning and Partnership Architecture
Given the moderate market concentration, partnerships and alliances are becoming increasingly important. Specialized tour operators can add value for hospitality groups seeking to fill tee times and rooms during off-peak periods, while hotel chains can leverage their loyalty bases to drive volume to golf destinations. The report analyzes how leading companies are structuring their offerings, where digital booking and app-based rewards are creating differentiation, and which partnership models are most effective in converting interest into booked revenue.
Risk Awareness and Resilience Planning
Growth brings complexity. Operators must navigate seasonality, weather dependency, geopolitical shifts affecting travel flows, and evolving consumer preferences around sustainability and authenticity. The report incorporates scenario-based considerations to help organizations stress-test their strategies against demand variability, input cost fluctuations, and changes in regulatory or tax environments. Building resilience into pricing models, distribution channels, and destination diversification is a recurring theme for firms aiming to sustain performance through cyclical fluctuations.
Why the Full Report Matters for 2026 Strategy
market intelligence is only as valuable as its relevance to concrete decisions. This Golf Tourism Market research goes beyond high-level sizing to deliver the operational detail that strategy teams need when evaluating investments, partnerships, and service expansions.
The full publication includes deep dives into segmentation structures, regional demand drivers, competitive benchmarking, and forward-looking scenario analysis. It maps how resort package growth, infrastructure investments, and operator distribution models are reshaping the revenue landscape. It also provides context on how consumer habits—such as the preference for culturally immersive travel, sustainable practices, and operator-mediated bookings—are influencing product design and marketing strategies.
Worldwide Culinary Tourism Market
For executives tasked with setting 2026 priorities, the report offers a structured way to assess where to commit resources, which customer segments warrant dedicated offerings, and how to position against both specialized golf travel firms and large hospitality brands. It is designed to reduce uncertainty in capital allocation, guide partnership targeting, and inform product development roadmaps.
Conclusion: Acting with Precision in a Growing Market
The golf tourism sector in 2026 presents a rare combination of strong macro momentum, diverse competitive playbooks, and clear signals from industry events and infrastructure investments. The projected growth path, anchored by a 9.1 percent CAGR through 2032, indicates that the market will continue to expand in both scale and sophistication. Yet growth alone does not guarantee success. The organizations that thrive will be those that combine data-informed market understanding with disciplined execution, thoughtful segmentation, and strategic partnerships.
This introduction has outlined the strategic contours of the landscape. The complete market research fills in the analytical details that turn high-level trends into actionable plans. For decision-makers ready to move from awareness to execution, the full report provides the depth required to act with precision. We invite you to access the complete publication to explore the segmentations, competitive profiles, regional insights, and strategic recommendations that will inform your 2026 golf tourism strategy.
For detailed analysis of this topic, please visit the official page: Golf Tourism Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


