



PW Consulting: Mine Ventilation Market Hits $155M in 2025, 5.9% CAGR to 2032

Strategic Imperative: Navigating the Mine Ventilation Equipment Market Through 2032
The underground mining sector stands at a critical operational inflection point. As global demand for critical minerals accelerates and legacy infrastructure faces increasing regulatory scrutiny, the machinery that sustains underground airflow has evolved from a basic utility into a strategic asset class. PW Consulting’s latest Mine Ventilation Equipment Market research provides a comprehensive, data-driven blueprint for executives, operations directors, and capital allocation teams who must make high-stakes decisions in 2026 and beyond.
This insight brief outlines the macro trajectory, competitive architecture, and regulatory-economic currents shaping the sector. It is designed to demonstrate the analytical depth of our full study while highlighting exactly where targeted intelligence will separate proactive operators from reactive followers.
A Market Defined by Resilient Growth and Structural Complexity
Drawing on historical performance from 2020 through 2025 and extending a forward-looking trajectory through 2032, the market demonstrates a consistent upward arc. The sector moved from a base valuation in the early 2020s to an estimated 155.0 Million USD by 2025. Our baseline projection places the market at approximately 165.46 Million USD in 2026, with sustained expansion carrying it toward roughly 230.98 Million USD by the close of the forecast window. This trajectory reflects a compound annual growth rate of 5.9 percent, a figure that underscores the sector’s resilience against broader commodity cycles.
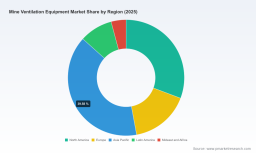
What makes this growth particularly noteworthy is not the headline number alone, but the underlying composition. The equipment base is heavily weighted toward core airflow generation technologies, while thermal management and auxiliary climate control solutions represent a meaningful secondary pillar. Demand distribution across mineral extraction domains reveals a pronounced reliance on coal mining operations, yet metal mining continues to contribute substantial volume as underground metallurgical projects scale. Regionally, the landscape is distinctly multi-polar, with no single geography holding outright dominance, which creates both sourcing flexibility and fragmented go-to-market challenges for global manufacturers.
For decision-makers, these structural patterns carry immediate implications. Capital planning cannot treat ventilation as a uniform procurement line item. Instead, it requires a segmented view that aligns equipment lifecycles with mine-specific operational horizons, regional supply chain realities, and the evolving cost of compliance. Our full report dissects these layers without exposing the granular breakdowns, preserving the analytical edge required to act decisively before competitors recalibrate.
Operational Content Designed for Execution, Not Just Observation
PW Consulting’s research methodology is built around actionable intelligence. Rather than stopping at macro forecasting, the study maps the operational terrain that procurement, engineering, and corporate strategy teams navigate daily. The report delivers a structured, multi-dimensional examination of the market, organized to support parallel workstreams.
- Technology and Product Architecture: A detailed evaluation of the equipment categories that constitute the market, including the performance trade-offs, installation constraints, and maintenance profiles that differentiate core airflow systems from climate regulation solutions.
- Application-Specific Demand Mapping: An exploration of how ventilation requirements diverge across extraction methodologies, with emphasis on the operational intensity, airflow volume targets, and safety specifications that drive procurement cycles in different mining environments.
- Regional Procurement and Deployment Patterns: A geographic assessment that examines supply chain maturity, local content expectations, logistical hurdles, and the varying pace of capital project execution across major mining corridors.
- Pricing, Input Costs, and Margin Architecture: Analysis of how raw material inputs—particularly steel and specialized polymers—interact with manufacturing complexity and after-sales service expectations to shape supplier pricing strategies and buyer negotiation leverage.
- Lifecycle and Total Cost of Ownership Modeling: Frameworks for comparing upfront equipment cost against long-term energy consumption, downtime risk, and retrofit requirements, enabling more accurate capital budgeting and lease-versus-buy evaluations.
Each section integrates primary market logic with observable industry behavior, allowing readers to benchmark internal assumptions against external realities. The report is structured to be referenced during budgeting cycles, vendor evaluations, and risk assessments, rather than read once and filed.
Competitive Architecture and Strategic Positioning
The vendor landscape reflects a blend of entrenched industrial manufacturers, specialized engineering firms, and regionally anchored innovators. Market concentration data indicates a moderately consolidated environment, with the leading trio of players accounting for a substantial share of revenue and the top five collectively representing a majority of market activity. This concentration does not imply static dominance; rather, it highlights the competitive intensity surrounding technology integration, service network coverage, and application-specific customization.
Mining Equipment Market
Several internationally recognized firms anchor the upper tier of the market. Howden, operating from the United Kingdom, continues to leverage deep industrial airflow heritage, with recent field deployments underscore its focus on optimization and site-specific engineering integration. Epiroc and Sandvik, both headquartered in Sweden, bring complementary underground equipment ecosystems that increasingly incorporate ventilation as part of broader mine productivity and safety agendas. TLT-Turbo, based in Germany, has reinforced its technical positioning through smart-controlled fan platforms designed for underground environments, aligning with broader industry moves toward connected equipment. Minetek, with its Australian operational base, has strengthened its product pipeline through the introduction of higher-efficiency fan series, reflecting a clear emphasis on performance gains and energy-conscious design.
Across the Americas, firms such as Twin City Fan & Blower, New York Blower Company, ABC Industries, Chicago Blower, and Hurley Ventilation maintain active roles in addressing regional demand, often competing on engineering responsiveness, component availability, and localized service capacity. In parallel, Australia-based specialists including Zitron and Clemcorp Australia contribute to the market through focused product development and regional project execution. Sibenergomash-BKZ extends the competitive field from Russia, adding geographic and supply chain complexity for operators managing cross-border procurement or evaluating alternative sourcing routes. Parag Fans & Cooling Systems, based in India, reflects the growing relevance of cost-competitive manufacturing and export-oriented capacity within the broader vendor ecosystem.
The recent timeline of product activity reinforces how competition is shifting from pure equipment supply toward performance optimization and digital integration. Howden’s May 2026 ventilation optimization installation for a major gold mining operation illustrates the growing premium on site-tuned airflow management. Minetek’s January 2025 launch of its high-efficiency Raptor Series—along with the simultaneous announcement of efficiency gains—demonstrates how manufacturers are competing on energy performance as a direct value proposition. TLT-Turbo’s January 2025 introduction of a smart fan concept for underground mining further signals that intelligent control, monitoring, and adaptive operation are becoming central differentiators.
For corporate strategy teams, this competitive map raises critical questions. Which vendors can reliably support multi-site deployments? Where do service networks and spare parts availability create long-term risk? Which technology roadmaps align with a mine’s automation trajectory and regulatory exposure? The full report evaluates these dynamics in greater depth, providing comparative context that helps buyers and investors avoid over-reliance on surface-level brand recognition.
Regulatory, Economic, and Operational Currents Reshaping Demand
Market growth does not occur in a vacuum. Several intersecting forces are redefining how ventilation equipment is specified, purchased, and maintained.
Safety Regulation as a Continuous Upgrade Driver
Regulatory frameworks are increasingly prescriptive about underground airflow, methane management, and system reliability. In the United States, MSHA 30 CFR Part 75 Subpart D establishes specific requirements for underground coal mine ventilation to ensure adequate airflow and safety, creating a compliance baseline that directly influences equipment selection and retrofit timing. Beyond individual jurisdictions, broader guidance such as the UNECE’s February 2025 direction on tackling methane emissions from coal mine ventilation systems highlights a global shift toward emissions-conscious ventilation design. These regulatory currents are not limited to compliance checklists; they actively push operators toward system upgrades that can satisfy both safety mandates and efficiency expectations.
Mine Ventilation Equipment Market
Energy Efficiency Mandates and Operational Cost Pressure
Stricter safety standards and energy efficiency mandates require upgrades to ventilation systems in underground mines, a reality that interacts directly with operating cost structures. Ventilation represents a significant share of underground energy consumption, and operators are increasingly scrutinizing fan performance, duct losses, and control logic as part of broader cost-reduction programs. As a result, procurement decisions are moving beyond initial capital cost toward lifecycle energy impact, maintenance intervals, and adaptability to changing mine geometries.
Automation, Labor Dynamics, and Digital Control Demand
Automation and labor shortages drive demand for advanced mine ventilation equipment with digital controls. As mining organizations confront skilled labor constraints and seek to reduce dependence on manual intervention, equipment that supports remote monitoring, automated airflow adjustment, and integrated diagnostics becomes operationally attractive. This trend reinforces the strategic relevance of intelligent fan systems, sensor-driven control architectures, and service models that can sustain performance without expanding onsite labor requirements.
Material Supply and Construction Realities
The physical basis of ventilation equipment remains rooted in durable construction materials. Steel and specialized polymers are primary raw materials for constructing durable mine ventilation fans and ducts, meaning that procurement planning must account for input availability, cost volatility, and lead-time variability. Equipment choices that appear favorable on performance grounds can be challenged by material sourcing constraints, especially when projects span multiple regions or require rapid deployment schedules.
Strategic Decisions That Define 2026 and the Forecast Horizon
The intersection of steady market expansion, concentrated vendor competition, and intensifying regulatory and operational pressures creates a clear strategic mandate: mining organizations must treat ventilation equipment planning as a forward-looking competency rather than a reactive procurement function. The years ahead will reward operators who can align technology selections with compliance trajectories, energy objectives, labor strategies, and project timelines.
Several decision points will be especially consequential:
- When to retrofit versus when to standardize: Operators must evaluate whether existing installations can be optimized through controls and component upgrades, or whether full system replacement offers better long-term alignment with safety and efficiency requirements.
- How to evaluate vendor roadmaps: Selection criteria increasingly include digital readiness, service coverage, parts availability, and the ability to support multi-site standardization without sacrificing site-specific performance.
- Where regional dynamics alter sourcing logic: Differences in supply chain maturity, local content expectations, and deployment pace mean that the optimal vendor or equipment configuration in one corridor may be suboptimal in another.
- How to quantify total cost of ownership under shifting input costs: Energy performance, maintenance burden, and material-driven pricing changes must be modeled together to avoid decisions that optimize only the purchase price.
These are not abstract considerations. They directly affect capital efficiency, operational continuity, and risk exposure across the forecast period. The challenge is that the necessary judgment depends on access to structured, current, and comparison-ready intelligence rather than fragmented market noise.
Access the Full Intelligence Framework
PW Consulting’s complete Mine Ventilation Equipment Market study provides the analytical foundation required to navigate these choices with confidence. The full report extends beyond the macro trajectory and competitive overview presented here, delivering the detailed segmentation logic, regional deployment context, vendor evaluation structure, and forward scenarios that executives need for 2026 planning and multi-year capital strategy.
The market’s direction is clear enough to warrant action, but the precise allocation of resources—by equipment category, application environment, regional pathway, and vendor relationship—requires the deeper breakdown contained in the complete study. For teams evaluating procurement strategy, vendor partnerships, expansion timing, or investment exposure, the full research package offers the level of specificity needed to convert market awareness into executable advantage.
Those seeking the complete dataset, comparative vendor context, and forward-looking scenario detail are encouraged to access the full report through the official PW Consulting market research portal. In a sector where compliance, energy, and operational continuity converge, timely access to structured intelligence is not simply an advantage—it is a prerequisite for sound strategic decisions.
For detailed analysis of this topic, please visit the official page: Mine Ventilation Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


