



PW Consulting: Laser Cladding Market Hits $565.45M in 2025, Poised for 9.46% CAGR Growth Through 2032

Strategic Horizons in the Laser Cladding Material Market: A 2026 Executive Briefing
Setting the Stage for Industrial Transformation
The landscape of industrial manufacturing is undergoing a quiet but profound shift. As asset lifecycles extend and operational efficiency becomes non-negotiable, surface engineering technologies have moved from peripheral maintenance tools to core strategic enablers. Among these, laser cladding stands out for its precision, minimal thermal distortion, and ability to deposit high-performance materials exactly where they are needed. Our latest market research examines the commercial trajectory of laser cladding materials, offering a structured view of how supply, demand, and competitive forces are converging as we enter 2026.
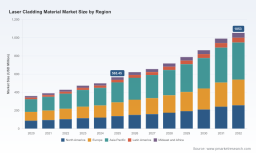
Historical momentum tells a clear story. Between 2020 and 2025, the global market for these specialized materials expanded from approximately 359.71 million USD to 565.45 million USD, reflecting sustained adoption across sectors that prioritize component longevity, performance restoration, and weight-sensitive design. This trajectory is not merely a reflection of cyclical demand; it is anchored in a structural transition toward additive and near-net-shape repair methodologies that reduce downtime and conserve high-value substrates. As organizations map their capital allocation for the coming years, understanding the cadence of this expansion becomes essential.
Looking ahead, the forecast period from 2026 through 2032 projects continued growth, with the market expected to reach an estimated 1,053.0 million USD by the end of the horizon. This expansion is underpinned by a compound annual growth rate of 9.46 percent, signaling a robust and sustained uptake rather than a short-term surge. For decision-makers, such a rate suggests that laser cladding materials will increasingly move from niche applications into broader industrial workflows, reshaping procurement strategies, supplier relationships, and capacity planning across multiple verticals.
The strategic relevance of this research lies in its ability to translate macro momentum into actionable intelligence. By mapping the interplay between material chemistry, deposition performance, regional demand centers, and application-specific requirements, we provide a framework that helps executives anticipate supply constraints, evaluate partnership opportunities, and align R&D investments with emerging use cases. This is not a static snapshot; it is a forward-looking lens designed to support resilient planning in a market defined by continuous technical refinement.
Macro Dynamics and the 2026 Decision Anchor
Entering 2026, enterprises face a dual imperative: capture the upside of accelerating demand while mitigating the risks of an increasingly concentrated supplier landscape. Market concentration data indicates that the top three players account for roughly 49.0 percent of total revenue, while the top five collectively represent 52.0 percent. Such concentration implies that pricing dynamics, technical support capabilities, and supply chain reliability are increasingly shaped by a handful of globally positioned organizations. For procurement leaders and strategy teams, this environment demands a deliberate approach to supplier diversification, qualification pipelines, and long-term offtake agreements.
The material ecosystem itself is evolving in response to performance expectations. Engineers are selecting consumables based on a matrix of deposition efficiency, bond strength, corrosion and wear resistance, and compatibility with specific laser parameters. Nickel-based, cobalt-based, and iron-based alloy families, alongside carbide blends and specialized formulations, each occupy distinct performance niches. The optimum choice depends less on a single metric and more on the intersection of operating environment, component geometry, and post-clad heat treatment requirements. Our research dissects these trade-offs without reducing them to oversimplified rankings, ensuring that decision-makers can match material families to real-world operational constraints.
Regional demand patterns further complicate the planning picture. Industrial activity, regulatory environments, and local manufacturing footprints create uneven adoption curves across geographies. Some markets are driven by heavy industrial repair cycles and energy infrastructure maintenance, while others reflect advanced manufacturing ecosystems with high throughput requirements and stringent quality documentation. Rather than presenting static regional shares, our analysis maps demand intensity against local industrial capabilities, logistics considerations, and technical service availability. This approach helps organizations identify where partnerships, distribution channels, or localized qualification efforts will yield the highest returns.
Application-side demand is equally multifaceted. Aviation, automotive, power generation, oil and gas, mining, and construction each impose distinct performance criteria and lifecycle expectations on clad surfaces. Components in flight-critical environments demand materials that balance strength retention with fatigue resistance. Power generation assets require coatings that withstand thermal cycling and corrosive media. Mining and construction equipment prioritize wear resistance under abrasive conditions. Our report examines how these application profiles shape volume expectations, specification sensitivity, and the pace at which new material grades gain acceptance in qualified workflows.
What the Research Delivers: A Practical Toolkit for Strategy Teams
Comprehensive market intelligence must be usable, not merely descriptive. This report is structured to serve as a working reference for product managers, procurement strategists, R&D leads, and investment analysts. It combines quantitative trajectory analysis with qualitative assessment of technology readiness, qualification barriers, and commercial positioning. The objective is to equip teams with a clear sense of where value is being created, where bottlenecks are likely to emerge, and how to sequence decisions over the 2026 to 2032 window.
Laser Cladding Material Market
The research framework covers the following core dimensions:
- Market Sizing and Trajectory: A year-by-year view of market scale from historical baselines into the forecast horizon, enabling scenario planning around volume growth, pricing environments, and capacity investments.
- Material Family Assessment: An evaluation of alloy and composite categories based on deposition behavior, mechanical performance, and compatibility with common laser cladding systems, helping teams align specification choices with application requirements.
- Application Landscape: A breakdown of demand drivers across major end-use segments, highlighting where performance thresholds, regulatory qualifications, and procurement cycles influence adoption speed.
- Regional Demand Context: A qualitative mapping of geographic demand intensity relative to industrial structure, service infrastructure, and supply chain accessibility, supporting decisions on market entry, distribution, and technical support localization.
- Competitive Positioning: A structured review of key participants, their product architectures, and areas of focus, providing context for partnership evaluation, procurement risk assessment, and benchmarking.
Beyond these structural elements, the report integrates practical aids designed for immediate application. These include supplier evaluation criteria aligned with deposition consistency and particle size control, guidance on qualifying new material grades for recurring repair or production workflows, and a decision lens for balancing standard offerings against custom formulations. For organizations exploring expansion into higher-value component refurbishment or performance-critical coatings, the analysis clarifies where technical barriers are declining and where specialized know-how still commands a premium.
The emphasis throughout is on clarity of implication. Rather than leaving readers with isolated figures, the report connects market movement to operational consequences: how demand intensity affects lead times, how material selection influences process repeatability, and how competitive concentration shapes negotiation leverage. This makes the research suitable for both strategic planning sessions and operational readiness reviews.
Worldwide Wall Cladding Market
Competitive Landscape: Scale, Specialization, and Strategic Positioning
The supplier base in this market reflects a blend of broad-scale material producers and focused specialists. Several organizations have built their positioning around deposition-optimized powders, engineered particle size distributions, and application-specific alloy formulations. Their commercial strategies differ in subtle but important ways, and understanding these differences is critical for procurement planning and technology partnership selection.
Höganäs AB, headquartered in Höganäs, Sweden, has established a recognized presence through its Surfit® family of cobalt-, nickel-, and iron-based overlay welding powders. These materials are designed for high-speed laser cladding deposition, making them particularly relevant for operations where throughput and consistency are prioritized alongside performance. The company's emphasis on deposition efficiency aligns with industrial users seeking to reduce processing time while maintaining coating integrity.
OC Oerlikon Management AG, through its Oerlikon Metco business in Wohlen, Switzerland, supplies MetcoClad™ and MetcoMed™ alloy powders and wires for laser cladding and plasma transferred arc applications. Its portfolio spans multiple alloy families and delivery formats, supporting both industrial repair and specialized coating requirements. The breadth of its offering positions it as a resource for organizations that require a range of material options within a single procurement relationship.
Welding Alloys, based in Redditch, United Kingdom, focuses on laser-cladding-specific cored wires and consumables intended for hardfacing and wear-resistant coatings. Its product design reflects a strong orientation toward durabilty in demanding service conditions, appealing to users in sectors where abrasive wear and surface degradation are primary failure modes.
Wall Colmonoy Corporation, located in Madison Heights, Michigan, USA, produces Colmonoy® nickel-based, Wallex® cobalt-based, and Colferoloy™ iron-based laser cladding powders with tailored particle size distributions. The attention to particle size engineering supports process control and deposition consistency, factors that matter greatly in qualified production environments and precision repair workflows.
American Cladding Technologies, operating in the United States, provides laser cladding materials and systems centered on industrial repair and coating applications. Its more integrated approach to materials and application support can be attractive to organizations seeking to streamline qualification and deployment across recurring maintenance programs.
Alabama Specialty Products, also based in the United States, supplies custom laser cladding powders and materials with a particular focus on aerospace and energy sector component refurbishment. Its specialization underscores the premium that high-compliance sectors place on tailored formulations, documentation, and application alignment.
Together, these participants illustrate the spectrum of commercial approaches in the market: from broad alloy portfolios and deposition-focused product design to custom-formulation expertise and application-integrated support. The presence of meaningful concentration among leading suppliers reinforces the importance of evaluating not only material performance but also technical service, qualification assistance, and supply continuity. Our report examines these competitive dynamics in greater depth, helping teams understand where differentiation is material to outcomes and where standardization may reduce complexity.
Strategic Implications for 2026 and Beyond
For executives planning across 2026 and the subsequent forecast period, several strategic themes emerge. First, the pace of adoption suggests that laser cladding materials will increasingly intersect with broader asset management and predictive maintenance agendas. Components that once moved directly to replacement may now be economically restored, altering the economics of spare parts, inventory, and downtime planning. Organizations that integrate material selection into their reliability strategies can capture cost and performance advantages that are difficult to retrofit later.
Second, the demand for consistent deposition quality is elevating the importance of particle size control, alloy homogeneity, and compatibility with specific laser parameters. As qualification standards tighten and production environments become more automated, the margin for variability narrows. Procurement teams should therefore treat supplier technical capability and process documentation as core evaluation criteria, not secondary considerations.
Third, regional and application-specific demand will continue to diverge. Some markets will expand through heavy industrial repair cycles and energy infrastructure maintenance, while others will grow through advanced manufacturing and performance-driven coating programs. A disciplined approach to market prioritization, supported by clear qualification pathways and service readiness, will separate organizations that capture demand from those that merely monitor it.
Fourth, the concentrated supplier environment calls for deliberate relationship strategies. Long-term collaboration with suppliers that offer reliable quality, responsive technical support, and transparent supply planning can reduce operational risk. At the same time, maintaining qualification flexibility across multiple material families and vendors can protect against disruptions and preserve negotiating balance.
Our full market research translates these themes into detailed projections, segment-level context, and a structured competitive assessment designed to support concrete decisions. The complete dataset, scenario frameworks, and supplier evaluation tools are available in the full report, where we expand on the intersections of material performance, application requirements, and regional demand intensity that shape the 2026 to 2032 outlook.
Obtaining the Full Intelligence Package
The laser cladding material market is entering a phase in which technical precision and commercial strategy are increasingly inseparable. Organizations that approach this landscape with a clear understanding of growth trajectories, material trade-offs, and competitive dynamics will be better positioned to optimize procurement, accelerate qualification cycles, and align R&D with high-value applications. This briefing provides the strategic outline; the complete research delivers the granular intelligence required to act with confidence. We invite strategy, procurement, and engineering leaders to explore the full report for the detailed analysis, extended forecasts, and practical evaluation tools that support informed decision-making throughout the forecast horizon.
For detailed analysis of this topic, please visit the official page: Laser Cladding Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


