



PW Consulting: SST Market to Hit $344.8M by 2032, 6.98% CAGR in Solid State Transformers

Unlocking the Next Grid Revolution: Why the Solid State Transformer Market Demands Strategic Attention in 2026
The global electrification landscape is undergoing a structural transformation that many industry observers have long anticipated but few have quantified with precision. As distributed energy resources, high-density AI data centers, and heavy-duty electric mobility converge, the conventional transformer paradigm is reaching its operational and economic limits. Our latest market research on Solid State Transformers (SST) provides decision-makers with a rigorous, data-grounded view of this inflection point, framed explicitly for strategic planning across the 2026–2032 horizon.
The core value of this analysis lies in its direct alignment with enterprise decision cycles. Organizations evaluating grid-edge infrastructure, energy storage integration, or next-generation charging networks cannot rely on legacy power electronics benchmarks. SST architectures deliver voltage conversion, power factor correction, fault isolation, and bidirectional energy flow within a single compact platform. Yet the commercial trajectory of these systems depends on a complex interplay of manufacturing scale, wide-bandgap semiconductor pricing, regulatory incentives, and application-specific validation. Our research strips away speculative commentary and replaces it with a structured view of where capital, engineering effort, and partnership strategies should be directed in the near term.
Market Trajectory and the Strategic Imperative for 2026 Planning
The SST market has moved beyond early proof-of-concept phases into a period of measurable commercialization momentum. Our historical review from 2020 through 2025 captures a sustained expansion curve, driven by pilot deployments, utility interest, and accelerating demand from power-intensive digital infrastructure. Looking forward, the forecast window through 2032 outlines a market path that compounds at a CAGR of 6.98 percent in USD Million terms. This growth rate is meaningful not because it is explosive, but because it reflects a deliberate industrial scaling process rather than a transient technology fad.
For executives building investment committees or technology roadmaps, the strategic implication is clear. The market is large enough to warrant dedicated resource allocation, yet still fragmented enough that early positioning can shape vendor relationships, standard influence, and deployment backlogs. The revenue progression across the forecast period indicates that SST adoption will not occur as a single step-change event. Instead, it will unfold through sequential waves tied to data center expansion, renewable integration mandates, and commercial heavy-duty charging rollout. Understanding the sequencing of these waves is essential for timing procurement commitments, manufacturing capacity decisions, and partnership negotiations.
It is equally important to recognize that macroeconomic tailwinds alone do not guarantee successful commercialization. The research deliberately avoids presenting oversimplified adoption timelines. Instead, it maps the operational and financial friction points that determine which players convert pilot activity into repeatable revenue. That perspective is what makes the report actionable for 2026 planning: it shows where growth is structurally supported and where it is contingent on cost reduction, supply chain maturity, or regulatory follow-through.
Regulatory Catalysts and Manufacturing Realities Shaping Commercial Viability
Policy frameworks and material economics are exerting simultaneous pressure on the SST value chain. In the United States, the Department of Energy Grid Resilience and Innovation Partnerships program has allocated over USD 10.5 billion toward next-generation distribution infrastructure, creating a public funding layer that can de-risk early deployment and stimulate utility and industrial adoption. At the regional level, state public utility commissions in California, New York, and Texas have moved toward rate-based treatment for solid-state transformer deployments, which directly affects project economics for end users and system integrators.
In Europe, the revised F-gas regulation mandating SF6 phase-out in new medium-voltage switchgear by 2030 has sharpened the search for alternative distribution architectures. This regulatory shift does not automatically translate into SST demand, but it does open a policy-aligned pathway for technologies that can deliver precise voltage control and compact substation footprints without reliance on incumbent insulating gases. The strategic insight for market participants is that regulatory momentum often precedes commercial scale; organizations that anticipate the compliance calendar can align product development and pilot programs ahead of peak procurement windows.
On the supply side, cost dynamics remain a defining constraint. Silicon carbide power devices typically account for 30 to 40 percent of total SST system cost and can cost three to five times more than equivalent silicon counterparts. This material cost structure, combined with the broader reality that SST manufacturing expenses remain two to three times higher than conventional transformers on a per-kVA basis, means that competitiveness will hinge on design optimization, volume production, and application selection. The report examines how different players are navigating this cost equation, not as a generic challenge, but as a differentiated strategic variable across distribution-oriented, power-oriented, and traction-oriented implementations.
Segment Architecture: Where Value Is Concentrated and Where It Is Emerging
A core strength of the research is its structured segmentation framework, which helps organizations translate market size into operational priorities. Rather than presenting isolated share figures, the analysis explains how the market breaks down across type, application, and regional demand patterns, and why those distinctions matter for product strategy and go-to-market design.
By type, the research distinguishes among distribution, power, and traction solid-state transformer pathways. Distribution-focused SST units address localized grid-edge conversion and utility-scale feeder modernization, while power-oriented platforms are increasingly aligned with high-load digital infrastructure and energy storage interfaces. Traction applications, though smaller in current scope, represent a specialist segment tied to rail and heavy-mobility electrification. Each category carries its own qualification requirements, cost curves, and customer procurement cycles, which is why aggregate market forecasts must be interpreted through the lens of segment-specific economics.
By application, the study evaluates how SST technology maps onto renewable energy integration, electric vehicle charging infrastructure, power distribution, and traction use cases. These application segments are not interchangeable. Some demand high reliability and grid-forming capability; others prioritize modular scaling and fast response under intermittent generation. The research highlights how the same underlying SST architecture can be positioned differently depending on the customer’s operational constraints and service-level expectations.
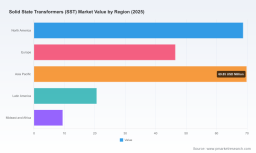
Regionally, the analysis explores how demand intensity varies across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. These geographic patterns reflect differences in grid modernization pace, electrification priorities, and industrial policy. The report does not reduce regional opportunity to a single headline number; instead, it contextualizes each territory’s likelihood of near-term SST integration based on infrastructure urgency, utility business models, and manufacturing or deployment ecosystems. For companies planning export strategy, pilot siting, or local partnerships, that regional nuance is often the difference between a credible market entry and an inflated projection.
Competitive Landscape: Who Is Moving Now and How the Field Is Shaping Up
The SST market remains comparatively concentrated at the top tier, with the top three players accounting for roughly 24.6 percent and the top five for about 26.2 percent of market share. This structure indicates that while the field is open enough for specialist entrants, scale advantages in supply chain, qualification, and customer access are already beginning to matter. The report profiles the companies that are most actively translating technology readiness into commercial positioning, with emphasis on their strategic moves rather than simple corporate descriptions.
DG Matrix, headquartered in Raleigh, North Carolina, has focused its Interport multi-port solid-state transformer platform on AI data centers, electrification, and microgrid applications. Its recent moves suggest a deliberate push to align SST hardware with the power density and flexibility requirements of next-generation digital infrastructure. In February 2026, the company announced a strategic partnership with Exowatt to integrate Interport SST technology into dispatchable renewable systems for gigawatt-scale AI-era infrastructure. That same month, DG Matrix closed a Series A funding round led by Engine Ventures to support commercialization of its multi-port platform. Together, these actions signal a strategy centered on pairing SST capability with renewable dispatchability and data-center demand clusters.
Amperesand, based in Singapore, is developing medium-voltage solid-state transformer platforms for critical infrastructure, AI factories, and grid electrification, with U.S. manufacturing and 2026 commercial deployments in view. In February 2026, the company targeted its first commercial medium-voltage SST deliveries to Fortune 100 customers and hyperscalers. For organizations evaluating supplier options, the notable point is not merely product specification but the combination of regional manufacturing footprint, medium-voltage focus, and direct engagement with large enterprise buyers.
Solid State Transformers (SST) Market
Worldwide Phase-Shifting Transformers Market
Eaton Corporation, headquartered in Dublin, Ireland, has strengthened its position through acquisition, completing the purchase of Resilient Power Systems Inc. in August 2025 to accelerate commercialization of medium-voltage solid-state transformer technology for data centers, energy storage, and EV charging infrastructure. This move illustrates how established power management players are using targeted technology acquisitions to close capability gaps and shorten the path from prototype to deployable product. The strategic lesson is that capability consolidation is already underway, and procurement teams should evaluate not only standalone innovators but also how larger platforms may bundle SST capabilities into broader energy and power services.
WattEV, located in Long Beach, California, is developing modular solid-state transformer solutions for megawatt heavy-duty electric truck charging stations, with production-ready units targeted for 2026. In January 2026, the company unveiled its modular SST technology and confirmed its production-ready deployment timeline. This positioning matters because heavy-duty charging represents one of the most demanding application environments for voltage control, thermal management, and modularity. Companies tracking SST adoption should therefore view WattEV’s trajectory as an indicator of how quickly high-power mobility charging can move from demonstration to operational scale.
Taken together, these developments show a competitive field that is simultaneously specialized and consolidating. Specialist firms are pushing application-specific SST platforms, while larger players are acquiring or integrating medium-voltage capability to serve multi-market demand. The report assesses these patterns not as a static vendor list, but as a moving landscape where partnerships, funding, and customer commitments are becoming as important as product specifications.
What the Report Delivers: Operational Scrutiny for Investment and Deployment Decisions
This market research is designed to support concrete decisions rather than high-level awareness. It synthesizes market sizing, segmentation logic, competitive activity, and regulatory context into a format that can be used by strategy, engineering, procurement, and investment teams. The emphasis is on what organizations can act on in 2026 and beyond.
Key analytical deliverables include:
- A structured view of market evolution across the 2026–2032 forecast period, with historical context from 2020–2025 to ground near-term expectations.
- Segment-level analysis across type and application, showing how demand drivers differ and why the cost and qualification profile of each segment affects adoption timing.
- Regional demand context that helps identify where pilot programs, partnerships, or export strategies are most likely to generate traction.
- A competitive scan of core SST players and recent corporate developments, including acquisitions, partnerships, funding, and product announcements.
- An assessment of regulatory and material-cost factors that shape commercialization risk, including utility rate treatment, gas phase-out mandates, and wide-bandgap semiconductor economics.
- Practical guidance on where SST value is most defensible today and where it remains contingent on manufacturing scale and system-level integration.
Importantly, the report is built to support scenario planning. Because SST adoption is not uniform, organizations benefit from understanding which segments are closest to commercial repeatability and which still require further cost compression or utility acceptance. That distinction helps avoid over-indexing on headline market potential while missing the operational constraints that determine actual revenue conversion.
Strategic Recommendations for Executive Decision-Making
For enterprises evaluating the SST opportunity in 2026, the research suggests a disciplined approach that balances technology optimism with commercialization realism. The market is expanding, but expansion does not automatically translate into profitable participation. The following priorities emerge from the analysis.
- Align SST evaluation with application-specific value creation. The strongest early-case economics are likely where SST delivers multiple functions simultaneously, such as voltage conversion, isolation, and bidirectional control within a compact footprint.
- Track material cost and manufacturing scale as first-order variables. Wide-bandgap semiconductor pricing and per-kVA manufacturing premiums will influence competitiveness until volume production and design standardization reduce premium levels.
- Use regulatory signals as timing indicators rather than guaranteed demand triggers. Public funding programs and SF6 phase-out mandates shape the environment, but actual procurement still depends on utility business models, customer qualification processes, and total cost of ownership.
- Plan for a concentrated but active supplier landscape. Early market leaders are building momentum through partnerships, acquisitions, and targeted funding, so organizations should evaluate both specialist innovators and integrated platform players for fit with their deployment roadmap.
- Focus pilot selection on provable operational outcomes. In a market where premium costs remain significant, pilots that demonstrate reliability, serviceability, and integration value will have stronger positioning than those based solely on technology novelty.
The SST market is entering a phase where strategic clarity matters more than generalized enthusiasm. Companies that understand segment economics, competitive momentum, and regulatory pathways will be better positioned to select deployment opportunities, negotiate supplier relationships, and organize internal investment around realistic commercialization timelines.
Conclusion: From Market Signal to Actionable Intelligence
Solid-state transformers are no longer an abstract power-electronics concept. They are becoming a deliberate option for organizations seeking more controllable, more compact, and more flexible energy conversion at the grid edge and within high-load infrastructure. The question for 2026 is not whether the technology matters, but where it matters first, how quickly cost and scale will improve, and which companies are converting technical capability into commercial execution.
This report provides the structured intelligence required to answer those questions with discipline. It combines market sizing, segment logic, competitive developments, and regulatory context into a decision-oriented framework that can inform capital allocation, product strategy, and partnership planning. For leaders who need to move beyond broad estimates and toward a usable deployment and investment thesis, the full analysis offers the depth, segmentation, and competitive detail that an executive briefing alone cannot provide.
To turn this overview into a workable strategy, we recommend accessing the complete SST market research, where the full segmentation detail, company profiles, regulatory map, and forecast structure are available in their entirety. That is where market potential becomes operational instruction, and where strategic intent can be matched to the commercial realities of building, buying, or partnering around solid-state transformer technology in the years ahead.
For detailed analysis of this topic, please visit the official page: Solid State Transformers (SST) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


