



PW Consulting: Luxury Yacht Market Hits $11.0B in 2025, Poised for 6.98% CAGR Through 2032

Navigating the Blue Horizon: Strategic Intelligence for the Global Luxury Yacht Market in 2026
The global luxury yacht industry stands at a pivotal inflection point as it moves deeper into the second half of the decade. Characterized by high net worth individual demand, complex manufacturing ecosystems, and increasingly stringent regulatory environments, the sector requires more than mere observation. It demands rigorous, data-driven strategic intelligence.
Luxury Yacht Market
This article serves as a comprehensive introduction to PW Consulting latest market research publication: the Luxury Yacht Market Report 2026–2032 . Designed for executives, investors, and industry stakeholders, this study dissects the forces shaping revenue trajectories, competitive positioning, and operational risks across the superyacht value chain. Below, we outline the strategic value proposition of this research, preview the macro-economic landscape, and demonstrate why access to the full intelligence suite is critical for 2026 decision-making.
The Macro Landscape: Growth Trajectory and Market Scale
Understanding the broad contours of the market is the first step toward informed strategy. Based on historical data from 2020 through 2025 and our proprietary forecast models extending to 2032, the luxury yacht sector has demonstrated consistent resilience and expansion, even amidst global economic volatility.
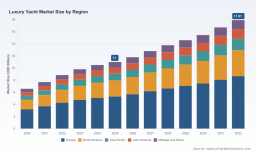
The market has evolved from a revenue base of approximately 6.58 billion USD in 2020 to an estimated 11.0 billion USD by 2025. This expansion reflects not only recovery from pandemic-era disruptions but also a structural shift in high-net-worth consumption patterns, with a marked preference for experiential luxury and asset-based wealth preservation. Looking forward, our analysis projects the global market revenue to reach 17.91 billion USD by 2032.
This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 6.98 percent over the forecast period. Such a rate indicates healthy organic expansion, though it also signals intensifying competition for new builds, charter inventory, and after-sales service contracts. For stakeholders, this trajectory suggests that volume-based strategies must be balanced with margin protection, as raw growth alone will not guarantee profitability in an increasingly sophisticated buyer environment.
Why This Report Matters for 2026 Decision-Makers
Strategic planning in the yacht industry cannot rely on aggregated headlines. Manufacturers, brokers, charter operators, and financial institutions need granular visibility into segmentation dynamics, regional nuances, and competitive maneuvering. Our report is engineered to provide this visibility without overwhelming decision-makers with raw data tables. Instead, it translates complex datasets into actionable strategic narratives.
Comprehensive Coverage of Build, Demand, and Application Segments
The study examines the market through multiple analytical lenses. We analyze the revenue contribution of motor yachts versus sailing yachts, highlighting how design preferences and performance requirements drive distinct supply chains and pricing architectures. The breakdown of yacht size categories—from vessels up to 50 meters to those exceeding 100 meters—reveals shifting demand among owners who increasingly seek both coastal luxury and long-range expedition capabilities.
Furthermore, the report explores application splits between personal use and commercial charters. This distinction is critical as the line between private asset ownership and revenue-generating investment blurs. Understanding the commercialization trends, including crewed charters and corporate hospitality vessels, provides insight into secondary revenue streams that can alter total lifecycle value assessments.
Regional Intelligence and Demand Geography
While the global headline figures provide the macro context, regional demand patterns dictate where investments, showrooms, and service hubs should be located. Europe remains a dominant center of gravity for both manufacturing heritage and high-net-worth buyer concentration. North America represents a significant and growing demand hub, influenced by coastal wealth clusters and regulatory frameworks specific to US imports. Meanwhile, the Asia Pacific region, Latin America, and the Middle East and Africa each present unique growth vectors with distinct client profiles, financing environments, and logistical considerations.
Our regional segmentation analysis avoids superficial generalizations. Instead, it maps demand intensity against supply chain proximity, identifying where market friction—such as import tariffs or fragmented customs regimes—may impact final pricing and delivery timelines.
Competitive Dynamics: An Oligopolistic Battlefield
The luxury yacht manufacturing sector is characterized by high barriers to entry, substantial capital requirements, and long lead times for vessel delivery. These factors have fostered a moderately concentrated landscape, where a select group of established shipyards and brands command a significant share of total revenue.
Our analysis estimates that the top three competitors collectively represent approximately 55 percent of the market, while the top five firms account for roughly 62 percent. This concentration underscores the importance of brand equity, engineering reputation, and the ability to deliver bespoke or semi-custom vessels at scale.
Key Players and Their Strategic Postures
The report provides detailed profiles of the organizations that define the competitive arena:
- Feadship (Makkum, Netherlands) continues to anchor its identity on pure custom creation, a philosophy maintained since its founding in 1949, appealing to ultra-high-net-worth clients who demand unique hull forms and interiors.
- Lürssen (Bremen, Germany) remains a premium builder of complex custom motor and sailing yachts, known for technical sophistication and large-scale project execution.
- Sunseeker (Poole, United Kingdom) leverages its position as a world-leading luxury motor yacht brand with strong emphasis on design and engineering excellence, catering to a broad spectrum of luxury buyers.
- Ferretti Group (Forlì, Italy) operates multiple luxury motor yacht lines, including the Riva and Pershing brands, blending Italian design heritage with diversified product portfolios.
- Sanlorenzo (Viareggio, Italy) and Benetti (Viareggio, Italy) both offer semi-custom and full-custom superyacht solutions, competing on flexibility, quality, and the ability to tailor vessels to specific owner preferences.
- Azimut-Benetti Group (Viareggio, Italy) delivers bespoke and semi-custom vessels, often competing on styling, performance, and integrated ownership experiences.
- Oceanco (Makkum, Netherlands) has carved a niche in advanced expedition and custom motor yachts, focusing on capability and autonomy for long-range cruising.
- Heesen Yachts (Gorinchem, Netherlands) is recognized for aluminum hybrid and custom motor yachts, emphasizing speed, efficiency, and innovative hull construction.
- Gulf Craft (Moss Point, United States) produces luxury megayachts and private cruisers, expanding the reach of American-built or assembled premium vessels.
- Tankoa Yachts (Ancona, Italy), Amels (Makkum, Netherlands), Hakvoort Shipyards (Makkum, Netherlands), and Cantiere delle Marche (Macerata, Italy) each bring specialized expertise in semi-custom designs, large motor yachts up to 100 meters, sail and motor combinations, and custom engineering.
Additionally, the report tracks emerging activity from brands such as Valhalla Boatworks (South Portland, United States), known for luxury powerboats delivering Viking-quality motor yachts, illustrating how specialized builders are capturing niche segments within the broader market.
Recent Moves and Market Signals
The competitive landscape is not static. Recent activity at major industry events underscores the pace of product innovation and brand refreshment. At the Cannes Yachting Festival in September 2025, multiple manufacturers unveiled significant launches. Groupe Beneteau introduced 19 new models and 14 world premieres, including a new Sealoft range for Jeanneau, signaling aggressive portfolio expansion. Tankoa Yachts debuted the T450 luxury yacht, Benetti presented the Class 44M, and Cantiere delle Marche showcased the Prestige M7. Each of these launches reflects strategic efforts to capture shifting buyer preferences, refresh brand relevance, and compete for delivery slots in a market where wait times and customization are key differentiators.
Luxury Furniture Market
Our report goes beyond event summaries. It evaluates how such product launches influence order pipelines, pricing power, and competitive positioning, helping readers assess which manufacturers are likely to gain or lose share in the near term.
Regulatory and Economic Headwinds: Navigating Complexity
While demand fundamentals remain positive, the operating environment is becoming more complicated. Regulatory shifts and macroeconomic pressures are reshaping cost structures, compliance obligations, and market access. The report dedicates substantial attention to these dynamics, as ignoring them can lead to erroneous forecasts and strategic missteps.
Regulatory Evolution and Safety Standards
Regulatory frameworks are tightening across multiple jurisdictions. Malta revised its Commercial Yacht Code (CYC) in 2025, with the updated provisions taking effect on 1 July 2025. This code now governs commercial yachts—typically those carrying up to 12 passengers—through modernized design, safety, manning, and welfare standards. For charter operators and owners operating under commercial registries, these changes directly affect operational compliance and cost.
At the same time, the 2026 Yacht Code took effect from 1 January 2026, applying enhanced safety requirements to all vessels of 500 GT and above. Among the notable updates are mandatory fire safety provisions for lithium-ion equipment storage. As yachts increasingly incorporate advanced battery systems and hybrid technologies, compliance with these provisions becomes a design and procurement imperative rather than an afterthought.
Environmental Pressures and Carbon Pricing
The expansion of the EU Emissions Trading System (ETS) to the maritime sector, rolled out during 2024–2025, now applies carbon pricing to fuel emissions for superyachts operating in EU ports. This development introduces a new cost dimension for operators and owners who frequently navigate European waters. While the full financial implications depend on usage patterns and emission intensities, the directional signal is clear: environmental compliance is moving from voluntary sustainability narratives to hard operational cost factors.
Trade Policy and Regional Fragmentation
Trade dynamics are also adding friction. New US tariffs of 15 percent now apply to most goods imported into the United States, increasing costs for components built outside the country destined for luxury yachts sold to American buyers. For builders that rely on cross-border supply chains, this tariff structure affects both pricing strategies and sourcing decisions. Simultaneously, EU customs rules remain fragmented as of 2026, leaving superyacht owners exposed to potential VAT billing complications on high-value transactions. This fragmentation can complicate cross-border purchases, relocation of vessels, and ownership structuring.
Our report contextualizes these regulatory and trade elements within the broader market narrative, assessing how they interact with demand elasticity, buyer geography, and shipyard sourcing strategies. The full edition provides detailed mapping of risk exposure by region and vessel category.
What You Will Gain from the Full Report
This preview has highlighted the macro trajectory, competitive structure, and regulatory context that define the current luxury yacht market. However, strategic advantage lies in the details that cannot be fully unpacked in an introduction. The complete PW Consulting report delivers:
- Granular segmentation analysis that breaks down revenue contributions, growth rates, and strategic implications across type, size, application, and region, enabling precise go-to-market and investment decisions.
- Deep-dive competitive assessments that evaluate market share movement, brand positioning, product pipeline strength, and operational capabilities of key players, including their recent launches and development trajectories.
- Scenario-based forecasting that links regulatory developments, tariff structures, and carbon pricing mechanisms to financial outcomes, helping organizations model best-case, base-case, and stress-case scenarios.
- Practical recommendations for manufacturers, brokers, charter operators, and financial institutions, covering pricing architecture, supply chain resilience, compliance planning, and market entry or expansion strategies.
- Data-driven insights on how personal use demand and commercial charter dynamics are evolving, supporting asset valuation models and fleet planning decisions.
For organizations operating in or adjacent to the luxury yacht ecosystem, the difference between reactive management and proactive strategy is access to reliable, nuanced market intelligence. This report is designed to bridge that gap.
Conclusion: Positioning for the Next Phase of Growth
The luxury yacht market is on a clear growth path, with revenue expanding from levels observed in the early 2020s toward nearly 18 billion USD by 2032 and a CAGR of 6.98 percent guiding the forecast window. Yet growth alone does not win markets. Success in 2026 and beyond will depend on the ability to interpret segmentation signals, anticipate regulatory costs, navigate trade frictions, and align product strategy with the evolving expectations of high-net-worth buyers and commercial operators.
PW Consulting Luxury Yacht Market Report provides the comprehensive intelligence necessary to make those decisions with confidence. By combining historical context, forward-looking forecasts, competitive analysis, and regulatory assessment into a single cohesive study, it equips stakeholders to move beyond assumptions and act on evidence.
To explore the full segmentation breakdowns, competitive profiles, regional intelligence, and scenario models, we invite you to access the complete report on the PW Consulting portal. The detailed data and strategic frameworks contained within are tailored for decision-makers who require precision, not generalities, as they plan for the years ahead.
For detailed analysis of this topic, please visit the official page: Luxury Yacht Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


