



PW Consulting: Urine Analyzer Market Hits $532M in 2025, Projected to Reach $749M by 2032 at 5.1% CAGR

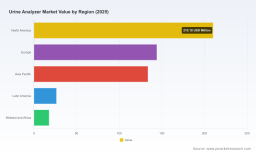
Strategic Intelligence for the Urine Analyzer Market: Navigating Growth and Consolidation Through 2032
The global urine analyzer market stands at a critical inflection point, where technological advancement, regulatory shifts, and evolving clinical workflows converge to reshape competitive dynamics. For executives, procurement leaders, and investment strategists, understanding the trajectory of this segment is no longer a tactical exercise but a core component of long-term capacity planning and portfolio optimization. Our latest market research report, covering the historical period from 2020 through 2025 and extending forecast insights to 2032, provides a rigorous, data-driven foundation for decision-making across healthcare systems, diagnostic networks, and medical device enterprises.
This strategic overview synthesizes the macro-level trends, structural shifts, and competitive intensities that define the urine analyzer landscape. It is designed to equip leadership teams with the contextual intelligence necessary to anticipate demand fluctuations, evaluate partnership opportunities, and align product roadmaps with emerging clinical and regulatory realities. While aggregate metrics offer a high-level view of market directionality, the full depth of segmentation, regional demand patterns, and application-specific growth vectors remains embedded within the complete report. Access to those granular intelligence layers is essential for precise capital allocation and market-entry strategy formulation.
Hematology Analyzer Market
Macro Market Trajectory and Demand Evolution
The urine analyzer sector has demonstrated consistent expansion over the past half-decade, driven by rising prevalence of chronic metabolic and renal conditions, increasing adoption of automated diagnostic workflows, and broader integration of urinalysis into routine preventive screening protocols. Historical revenue data reflects a sector that has moved steadily upward, with base-year valuation in 2025 establishing a clear foundation for forward momentum. Projections through 2032 indicate continued growth, supported by sustained capital investment in diagnostic infrastructure, expanding laboratory networks, and the gradual transition from manual or semi-automated processes to fully integrated digital platforms.
The compound annual growth rate across the forecast window underscores a moderately paced but structurally resilient expansion profile. Rather than exhibiting volatile spikes, the market reflects a measured adoption curve influenced by procurement cycles, regulatory clearance timelines, and institutional budgeting rhythms. For enterprise planners, this growth pattern signals the importance of phased deployment strategies, lifecycle pricing models, and service-contract architectures that align with multi-year adoption timelines. Understanding where volume concentration is likely to emerge, and which clinical environments will drive recurring reagent and consumables demand, requires the detailed breakdown available in the full research publication.
Urine Analyzer Market
Competitive Landscape and Strategic Positioning
The market exhibits a pronounced concentration dynamic, with a limited number of established manufacturers commanding dominant share positions. This consolidation pattern shapes pricing architecture, distribution leverage, and the pace at which new entrants can secure clinical validation and procurement contracts. The leading players have built competitive moats through integrated hardware-software ecosystems, proprietary fluidic and imaging technologies, and long-standing relationships with hospital networks and reference laboratories. At the same time, regional manufacturers are leveraging modular design, AI-assisted sediment recognition, and cost-optimized chemistries to capture share in price-sensitive procurement environments.
Several core enterprises define the current competitive architecture. Sysmex Corporation continues to emphasize workflow optimization through its UN-Series and UF-Series automated platforms, targeting laboratories that prioritize throughput consistency and seamless integration with existing laboratory information systems. ARKRAY, Inc. has focused its engineering efforts on fully automated chemistry and sediment analysis, with instruments such as the AUTION MAX AX-4060 and AUTION EYE AI-4510 designed to reduce manual review burdens while maintaining analytical rigor. Siemens Healthineers maintains a strong presence in point-of-care and mid-volume laboratory settings through semi-automated platforms like the CLINITEK Status+ and Advantus, catering to environments that require flexibility without sacrificing reliability.
Beckman Coulter reinforces its diagnostic portfolio with the DxU Iris Workcell and iQ200 Series, combining automated chemistry and microscopy capabilities to serve high-volume clinical laboratories seeking standardized, reproducible results. In Europe, 77 Elektronika Kft. has carved out a niche with the UriSed 3 PRO sediment analyzer and LabUMat 2 chemistry platform, emphasizing compact footprints and digital workflow integration. Erba Lachema s.r.o. offers the LAURA XL fully automated system alongside the LAURA Smart semi-automated option, addressing facilities that require scalable automation tiers. URIT Medical Electronic Co., Ltd. has expanded its modular AI-driven lineup with the US-2000 and US-1680 platforms, targeting laboratories that value configurable throughput and intelligent image interpretation. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. supports its broader diagnostics ecosystem with the EU-5300Pro and EH-2090, reinforcing its position in automated chemistry and sediment analysis across diverse clinical settings.
These competitive profiles illustrate a market where differentiation increasingly hinges on software maturity, image recognition accuracy, service responsiveness, and total cost of ownership rather than hardware specifications alone. The full report unpacks how these positioning strategies translate into regional share distribution, procurement preference patterns, and emerging vulnerability points for incumbents and challengers alike.
Technology Convergence and Regulatory Catalysts
Innovation in urine analysis is increasingly defined by the intersection of automation, digital imaging, and machine-assisted interpretation. Laboratories are moving toward platforms that minimize operator dependency, standardize sediment classification, and integrate results directly into electronic health record and laboratory information workflows. The shift toward AI-assisted sediment recognition, automated strip chemistry reading, and modular system architectures reflects a broader industry demand for reproducibility, traceability, and reduced turnaround times. For manufacturers, the strategic imperative is not simply to introduce new instruments but to deliver ecosystems that lower validation friction, simplify training, and provide actionable data outputs that clinicians can trust.
Regulatory developments are also reshaping the innovation landscape. In July 2025, the FDA granted Breakthrough Device Designation to the TOBY Test, a noninvasive, AI-powered tool designed for detecting bladder cancer. This milestone signals heightened regulatory openness to intelligent diagnostic approaches and may accelerate downstream interest in analytical platforms capable of supporting advanced biomarker and imaging workflows. Simultaneously, the April 2025 acquisition of Labrador Health by Healthy.io highlights a parallel evolution toward at-home quantitative testing and consumer-facing kidney health monitoring. These developments point to a longer-term expansion of urinalysis relevance beyond traditional laboratory boundaries, with implications for device design, data connectivity, and service delivery models.
For enterprise strategists, these signals suggest that product roadmaps must account for interoperability requirements, software validation pathways, and the potential integration of complementary diagnostic modalities. The complete research publication examines how these regulatory and technology shifts are likely to influence procurement priorities, clinical adoption thresholds, and competitive differentiation across the forecast period.
Operational and Strategic Implications for Decision-Makers
Translating market trajectory into actionable strategy requires a clear understanding of where demand is structurally expanding, which purchasing environments are most sensitive to automation economics, and how service and consumables revenue streams interact with instrument sales cycles. Hospital and clinic networks continue to represent a substantial share of utilization, driven by routine screening volumes, emergency department workflows, and integrated diagnostic pathways. Diagnostic laboratories remain central to the market’s growth equation, particularly as regional networks consolidate and seek standardized platforms that reduce inter-site variability. Additional application environments contribute incremental demand, often shaped by specialized testing requirements and decentralized care models.
From a competitive standpoint, the high concentration among leading manufacturers means that procurement negotiations, service-level agreements, and reagent pricing dynamics often favor organizations that can leverage volume commitments, multi-year contracts, and interoperability requirements. For emerging manufacturers and technology partners, market entry strategies must navigate validation timelines, distributor relationships, and the expectation of robust post-sale support. For investors and corporate development teams, the key question is not whether the market will grow, but how value will be distributed across hardware, software, consumables, and digital service layers over the next several years.
The full report provides the detailed segmentation architecture, regional demand contours, and application-specific revenue mappings required to answer those questions with precision. It also offers scenario-based considerations for capacity planning, portfolio prioritization, and partnership evaluation, enabling leadership teams to align operational decisions with the most probable market trajectories.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle demands a research foundation that balances historical validation with forward-looking scenario clarity. Organizations that rely on aggregated headlines or isolated product announcements risk misjudging procurement timing, overestimating near-term adoption velocity, or underappreciating the service and consumables economics that sustain manufacturer profitability. Our report is structured to eliminate that uncertainty by delivering a comprehensive view of market size evolution, competitive positioning, regulatory catalysts, and workflow-driven demand patterns.
Decision-makers across medical device strategy, diagnostic procurement, healthcare operations, and investment analysis will find the report particularly valuable for evaluating where to concentrate commercial resources, how to structure pricing and service models, and which technological competencies are likely to become table stakes in the coming years. The data framework supports internal scenario planning, competitive benchmarking, and market-entry feasibility assessments without requiring teams to piece together fragmented sources.
The complete intelligence package includes detailed segmentation breakdowns, regional demand distributions, application-level revenue mappings, and comparative profiles of the key enterprises shaping the market. These components are essential for transforming high-level growth awareness into executable strategy. To access the full dataset, segmentation architecture, and scenario analysis that underpin this overview, visit the source page for the complete Urine Analyzer Market research publication.
For detailed analysis of this topic, please visit the official page: Urine Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


