



PW Consulting: Container Leasing Market Hits $9.8B in 2025, Projected to Reach $13.1B by 2032

Strategic Horizons in the Container Leasing Market: Navigating Growth and Consolidation Through 2032
The global logistics infrastructure stands at a critical inflection point. As supply chains recalibrate following years of unprecedented disruption, the container leasing sector has emerged not merely as a support function but as a strategic lever for capital efficiency and operational resilience. PW Consulting is pleased to introduce our latest comprehensive study on the Container Leasing Market, designed to equip executive leadership and investment committees with the actionable intelligence required to navigate the forecast period from 2026 through 2032.
Railcar Leasing Market
This research is not a static snapshot of historical performance. It is a dynamic roadmap built upon rigorous analysis of market trajectories, competitive maneuvers, and macroeconomic shifts. For decision-makers evaluating capital allocation, fleet expansion, or partnership strategies in 2026, understanding the underlying mechanics of this industry is paramount. The following insights offer a preview of the strategic depth contained within our full report, highlighting the forces that will define value creation in the coming years.
Market Trajectory: From Recovery to Steady Expansion
The container leasing market has demonstrated remarkable resilience and growth over the past half-decade. Our analysis tracks revenue trends from 2020 through the base year of 2025, revealing a consistent upward trajectory despite volatile macroeconomic conditions. The market has evolved from a post-pandemic recovery phase into a period of stabilized expansion. Current valuations indicate that the industry has surpassed significant milestones, positioning itself for continued growth as global trade volumes normalize and optimize.
Looking forward, our forecast model projects a compound annual growth rate of 4.3 percent across the forecast horizon. This growth is not linear but is influenced by varying regional dynamics and sector-specific demands. By 2032, the market is expected to reach a substantially higher revenue baseline, reflecting both organic expansion and the compounding effect of strategic consolidations. For stakeholders, this implies that the window for acquiring assets at favorable valuations or securing long-term lease agreements may shift as demand pressures intensify in specific segments.
The revenue projection extends across multiple years, allowing clients to model cash flows and asset depreciation with greater precision. Our data suggests that while growth rates may fluctuate in the short term due to geopolitical or supply chain variables, the long-term fundamental demand for intermodal transport equipment remains robust. The transition from the base year into the forecast period highlights a market that is maturing, where efficiency and scale become increasingly decisive competitive advantages.
Industry Dynamics and Operational Headwinds
No strategic plan is complete without a clear understanding of the forces currently reshaping the operating environment. In 2025, the industry faced a unique confluence of challenges and opportunities. One of the most significant factors was the impact of geopolitical tensions on shipping routes. Attacks on shipping vessels in the Red Sea necessitated major rerouting, which in turn elevated demand for containers as supply chain disruptions forced companies to secure additional equipment to maintain throughput. This surge in demand during 2024 and 2025 altered inventory levels and utilization rates across the global fleet.
Paradoxically, while demand for equipment was elevated due to these disruptions, market leasing rates remained historically low throughout 2025 and into the beginning of 2026. This divergence presents a complex scenario for lessors and lessees alike. For shipping line customers, the reliance on leasing for new container additions decreased significantly amid elevated demand, suggesting a shift in procurement strategies or an increase in owned fleets during this period. Understanding why rates remained suppressed despite high demand is crucial for forecasting future pricing power and lease negotiation leverage.
Operational standards continue to dictate market participation. Containers must meet International Standards Organization criteria for size and gross weight rating to ensure standardization and facilitate container and vessel sharing across transporters. Compliance with these ISO criteria is not just a regulatory hurdle but a prerequisite for interoperability in a globalized network. Any analysis of market entry or fleet modernization must account for the capital intensity required to maintain these standards while adapting to evolving environmental regulations.
Furthermore, specific segments face distinct cost pressures. In the European chemical industry, high energy and feedstock costs, combined with regulatory and environmental pressures and weak downstream demand, have affected competitiveness and resulted in reduced production levels of tank containers. This dynamic illustrates how end-market health directly influences the manufacturing and availability of specialized leasing assets. For investors focused on niche segments such as tank containers, these upstream cost structures are vital indicators of future supply constraints and pricing potential.
Competitive Landscape: Consolidation and Specialization
The competitive structure of the container leasing market is characterized by high concentration and strategic differentiation. Our analysis indicates that the top three players command a significant share of the market, with the top five firms further solidifying their dominance. This concentration suggests that scale advantages in fleet management, depot networks, and customer relationships are difficult to replicate for smaller entrants. However, within this consolidated landscape, distinct strategies are emerging that define the leaders.
Triton International Limited stands as the world's largest lessor of intermodal containers. Headquartered in Hamilton, Bermuda, Triton owns and manages a fleet exceeding 7 million TEU as of December 31, 2025, supported by a global depot network spanning 47 countries. Their primary customers include major shipping lines, and their strategic footprint was recently enhanced when Triton entered an agreement to acquire Global Container International, adding approximately 0.5 million TEU to its fleet. This move underscores a strategy of aggressive capacity expansion to maintain market leadership.
Container Leasing Market
Textainer Group Holdings Limited represents another tier of dominance. Also based in Hamilton, Bermuda, Textainer manages a diversified fleet including dry, reefer, and tank types. In a landmark development during December 2025, Textainer completed the acquisition of Seaco Global. This combination brought their fleets to approximately 8.3 million CEU, making it the world's largest diversified container leasing platform. This consolidation signals a trend where lessors seek to broaden their asset mix to mitigate cycle risks and capture value across different container types.
Specialization remains a key theme for other major players. SeaCube Container Leasing Ltd., based in San Francisco, California, is the world's largest lessor of refrigerated containers. Their focus on cold-chain logistics solutions, portable cold storage, and management contracts differentiates them from generalist lessors. SeaCube has been actively expanding its cold-chain infrastructure, such as establishing a primary depot in Shafter, California, and partnering with The Wonderful Company to support refrigerated container presence in the California Central Valley. These moves highlight the growing importance of temperature-controlled logistics in the overall market mix.
Florens Asset Management Co. Ltd., operating out of Singapore, is one of the world's leading container lessors, leasing, managing, and selling containers worldwide to top 20 shipping companies. Their focus on flexible operating and finance leases allows them to cater to varied customer financial preferences. Recent leadership changes, including the appointment of a new Director and Chairman effective May 2025, suggest a strategic refresh aimed at navigating the next phase of growth.
Other significant participants include CAI International, a major intermodal container leasing provider emphasizing global fleet management and equipment services. Blue Sky Intermodal (UK) Ltd. offers long-term operating and finance leases of ISO marine containers to shipping lines, maintaining a strong presence in the European market. CARU Containers provides standard and specialized container leasing solutions globally, while Noble Container Leasing Limited, based in Hong Kong SAR, focuses on engineering innovation and environmental responsibility in marine container leasing and trading.
The tank container segment features its own set of leaders. Raffles Lease, headquartered in Singapore, is a leader in tank container leasing, providing flexible ISO tank container solutions with offices in key logistics hubs. Eurotainer, with European operations, is a global leader in ISO tank container leasing and logistics solutions, offering temperature-controlled, cryogenic, and food-grade tank containers with updated fleet designs. EXSIF Worldwide Inc. also claims status as a global leader in ISO tank container leasing, managing a fleet of over 70,000 tanks with strategic partnerships and 17 offices worldwide. The differentiation in this segment often revolves around specialized equipment capabilities and geographic reach to serve chemical and food-grade logistics.
Segmentation: Understanding Asset and Application Mix
To fully grasp the investment potential and risk profile of the container leasing market, one must look beyond aggregate numbers. The market is segmented by container type, application, and region, each presenting unique growth drivers and challenges. Our report dissects these segments to reveal where value is being generated.
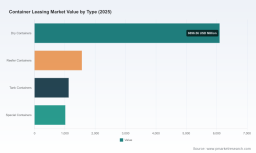
By type, the market encompasses dry containers, reefer containers, tank containers, and special containers. Dry containers continue to represent the bulk of the fleet due to their versatility in general cargo transport. However, the reefer segment is gaining strategic importance as cold-chain logistics become critical for pharmaceuticals and perishable goods. Tank containers serve specialized liquid and gas transport needs, often tied to the chemical and energy sectors, while special containers cater to oversized or unique cargo requirements. The interplay between these types affects fleet utilization rates and residual values.
In terms of application, industrial product transport, consumer goods transport, food transport, and other categories drive demand. Industrial product transport typically correlates with manufacturing output and raw material movement. Consumer goods transport is linked to retail cycles and e-commerce growth. Food transport is sensitive to seasonal factors and cold-chain infrastructure availability. Understanding the mix of these applications within a lessor's portfolio is essential for predicting revenue stability across economic cycles.
Regional dynamics also play a crucial role. The Asia Pacific region remains a central hub for manufacturing and trade, influencing container flows significantly. North America and Europe represent mature markets with established logistics networks but face specific regulatory and cost environments. Latin America and the Middle East and Africa offer emerging opportunities driven by infrastructure development and trade route shifts. Our analysis provides detailed insights into how these regional factors interact with global fleet deployments without exposing specific valuation figures that require deeper consultation.
Strategic Imperative for 2026 Decision-Making
Why does this level of detail matter for your 2026 strategy? The answer lies in the intersection of market timing, asset specificity, and competitive positioning. The forecast period from 2026 to 2032 will likely see continued consolidation among major lessors as they seek to optimize fleet sizes and expand geographic coverage. Companies that understand the implications of recent acquisitions, such as those completed by Triton and Textainer, will be better positioned to anticipate shifts in supply availability and pricing power.
For shipping lines and logistics providers, the decision to lease versus buy is influenced by historical low leasing rates and the availability of owned assets. However, as the market 사이클 matures and demand pressures from geopolitical disruptions persist, the balance may tip. Our report provides the frameworks to evaluate these trade-offs under various scenarios. For investors, the high concentration of the market suggests that private equity and M&A activity will remain vibrant, particularly around specialized firms with strong niche positions in reefers or tank containers.
Environmental regulations and technological innovations are also reshaping the landscape. Newer fleet designs, such as those promoted by Eurotainer and Noble Container Leasing, focus on efficiency and environmental responsibility. These factors are increasingly influencing customer selection criteria and may impact the residual value of older assets. Decision-makers need to incorporate these lifecycle costs and compliance requirements into their long-term planning.
Furthermore, the volatility seen in 2025 regarding leasing rates versus demand highlights the importance of agile fleet management. Companies that can dynamically redeploy assets across regions or container types may capture opportunities that static models miss. Our research offers performance indicators and trend analysis to support such agility.
Accessing the Full Intelligence
This overview provides a foundation for understanding the strategic landscape of the Container Leasing Market. However, the nuances that drive precise valuation, risk assessment, and opportunity identification are contained within the full body of our research. PW Consulting's detailed report includes granular data on market sizing, segmentation splits, competitive profiling, and scenario-based forecasts that are essential for high-stakes decision-making.
We invite stakeholders to leverage this comprehensive intelligence to refine their strategies for 2026 and beyond. By accessing the complete study, you will gain the insights necessary to navigate the complexities of fleet management, capital allocation, and market entry in a consolidating and evolving global industry. The data presented here is a testament to the rigor of our analysis, but the full picture requires a deeper dive into the specific metrics and strategic recommendations available in our finalized market research publication.
For detailed analysis of this topic, please visit the official page: Container Leasing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


