



PW Consulting Report: Speed Reducers Market to Hit $18.79B by 2032, Growing at 8.4% CAGR

Strategic Outlook 2026: Navigating the Speed Reducers Market Landscape
Executive Summary
The global industrial landscape is undergoing a profound transformation, driven by automation, efficiency mandates, and supply chain realignments. At the heart of these mechanical systems lie speed reducers, critical components that ensure precise torque control and operational reliability across diverse sectors. As we move deeper into 2026, understanding the trajectory of this market is no longer optional for strategic planners; it is a necessity. This article serves as a precursor to our comprehensive market research report, offering a high-level view of the forces shaping the industry while highlighting the depth of intelligence available to stakeholders who seek a competitive edge.
The speed reducers market has demonstrated remarkable resilience and growth over the past half-decade. Based on our analysis, the market value reached approximately 10,681.55 million USD in 2025, building upon a steady historical trajectory from 2020. The momentum shows no signs of slowing, with projections indicating a climb toward 18,786.21 million USD by 2032. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 8.4 percent during the forecast period of 2026 to 2032. Such figures suggest more than mere inflation; they point to genuine industrial uptake and technological integration that demands attention from C-suite executives and investment committees alike.
Speed Reducers Market
Market Trajectory and Macro-Economic Drivers
Understanding the historical context is vital for validating future projections. The market valuation has consistently escalated from 7,136.54 million USD in 2020 to the 2025 baseline. This upward curve reflects broader industrial health, yet the forecast period introduces new variables. The growth from 11,235.94 million USD in 2026 to over 18,000 million USD by 2032 implies a significant acceleration in demand. This is not merely a continuation of past trends but suggests a shift in how power transmission systems are valued and utilized in modern engineering contexts.
Several macroeconomic factors are fueling this expansion. The push for energy efficiency in manufacturing plants requires machinery that minimizes power loss during transmission. Speed reducers play a pivotal role here, converting high-speed motor output into high-torque, low-speed application requirements. Furthermore, the ongoing modernization of legacy infrastructure in developed economies, coupled with rapid industrialization in emerging markets, creates a dual-engine growth scenario. However, navigating this landscape requires more than top-line numbers; it requires an understanding of where the value is concentrated and how risks are distributed.
Competitive Landscape and Corporate Intelligence
The market structure is characterized by a moderate level of concentration, indicating a mix of dominant players and specialized niche providers. Our analysis indicates that the top three companies hold a significant portion of the market share, while the top five extend this influence further. This concentration suggests that while there is room for innovation, scale and established distribution networks remain critical advantages. The competitive field is global, featuring legacy manufacturers from Europe and North America alongside agile innovators from Asia.
Prominent entities such as SEW-Eurodrive, headquartered in Bruchsal, Germany, continue to set standards in integrated drive systems. Their focus on combining helical, worm, and bevel-helical reducers with electric motors highlights a trend toward simplification and ease of integration for industrial automation. Similarly, Sumitomo Heavy Industries in Tokyo maintains a strong foothold in heavy-duty sectors, supplying large speed reducers and cycloidal units for mining and steel applications. These companies represent the established backbone of the industry, providing reliability for high-load environments.
On the precision front, Nidec Corporation and Harmonic Drive LLC are pivotal. Nidec Shimpo's focus on planetary and cycloidal reducers for robotics and machine tools aligns with the broader automation surge. Harmonic Drive, based in Peabody, Massachusetts, specializes in strain-wave technology, catering to the stringent requirements of medical equipment and precision machinery. Meanwhile, North American manufacturers like Bonfiglioli, ABB Baldor, Boston Gear, and Nord Drivesystems offer comprehensive solutions ranging from standard components to custom-industrial packages. Companies like Winsmith and Broadwind focus on heavy-duty custom assemblies, ensuring that specific torque and load requirements are met without compromise.
Recent activity among these key players underscores the dynamic nature of the sector. In early 2026, Winsmith announced a new line of aluminum round and square speed reducers, signaling a shift toward lightweight materials and modular housing designs. Participation in major trade events such as IPTEX GRINDEX and AISTech by entities like Regal Rexnord and various gear specialists demonstrates the industry's commitment to showcasing metal industry solutions and high-speed epicyclic units. These developments are not isolated; they are signals of strategic pivots toward material innovation and specific industry vertical solutions.
Segmentation Dynamics: Type and Application
To make informed decisions, one must look beyond the aggregate number. The market is divided by technology type, with gear reducers historically commanding the largest share due to their versatility and durability. Worm wheel reducers, planetary gears, cycloid reducers, and harmonic drives each serve distinct operational niches. For instance, while planetary gears offer high efficiency and compactness suitable for robotics, cycloid reducers are preferred for heavy-duty shock load resistance. Understanding the share and growth potential of each type is crucial for product portfolio planning.
Application sectors also drive demand diversity. The industrial sector remains the primary consumer, reflecting the broad use of speed reducers in general machinery and automation. However, significant volume is also generated by the food industry, mining industry, and construction industry. Each sector imposes unique constraints. Food processing requires hygiene-compliant materials and sealing, mining demands extreme durability under abrasive conditions, and construction needs mobility and ruggedness. A strategic supplier must align its product engineering with these specific application demands. Our research delves into the revenue contribution and growth rates of each application segment, identifying where the highest margins and fastest growth intersect.
Regional Insights and Supply Chain Considerations
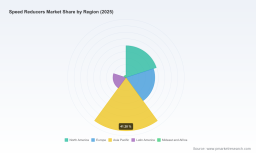
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Asia Pacific represents a massive volume hub, driven by manufacturing capacity and local industrial growth. North America and Europe remain critical for high-value, precision applications and aftermarket services. Latin America and the Middle East and Africa offer emerging opportunities tied to infrastructure projects. However, regional performance is not just about sales volume; it is about supply chain resilience.
The cost of raw materials remains a primary concern. High-grade cast iron, steel forgings, and specialized alloys constitute a significant majority of the manufacturing cost for speed reducers. Volatility in these inputs can compress margins significantly. Strategic procurement and vertical integration are becoming differentiators. Companies that secure stable supply lines for critical alloys or invest in additive manufacturing for complex gear components may gain a cost advantage. Furthermore, logistics and localization strategies are evolving to mitigate geopolitical risks and reduce lead times for customers in critical regions.
Regulatory Frameworks and Technical Standards
Compliance is another layer of complexity defining the 2026 landscape. Technical standards ensure interoperability and safety, but they also act as barriers to entry for non-compliant manufacturers. The American Gear Manufacturers Association (AGMA) continues to provide essential classifications for designing and maintaining reliable power transmission systems. Adherence to these standards is often a prerequisite for tendering in large industrial projects.
Beyond general manufacturing standards, specific operational regulations are coming into force. The ISO 15016:2025 specification for the assessment of speed and power performance by analysis of speed trial data entered into force on May 1, 2026. This regulation impacts how performance is validated, particularly in marine and mobile applications. Additionally, MEPC.403(83) requires EEDI-relevant speed trials for newbuilding vessels to utilize ISO 15016:2025 or specific recommended procedures from the same date. For companies supplying reducers to marine or offshore sectors, alignment with these updated specifications is immediate and critical. Failure to comply can result in exclusion from key contracts or regulatory penalties.
Strategic Implications for 2026 Decision Makers
The convergence of growth, competition, and regulation creates a complex decision matrix for 2026. For investors, the 8.4 percent CAGR presents an attractive entry point, but due diligence must extend beyond top-line growth to assess the competitive positioning of individual firms. For manufacturers, the focus must shift to differentiation through material innovation, such as the aluminum housing trends noted in recent product launches, and precision enhancements in planetary and harmonic technologies.
Procurement leaders face the challenge of balancing cost against reliability. With raw material costs representing a large fraction of manufacturing expenses, supplier stability is as important as unit price. Partners with robust supply chains and adherence to evolving ISO and AGMA standards offer lower risk profiles. Additionally, the regional distribution of revenue suggests that a multi-region strategy may be necessary to hedge against localized economic downturns or supply disruptions.
RV Reducer Market
Conclusion: The Value of Complete Intelligence
The speed reducers market in 2026 is a landscape of opportunity tempered by technical and regulatory complexity. While the macro indicators point to a robust expansion toward nearly 19 billion USD by 2032, the real strategic value lies in the nuances. Which specific technology type is outperforming in the robotics sector? Which region is seeing the fastest adoption of high-efficiency worm reducers? How do the latest regulatory changes specifically impact offshore gear supply contracts?
This article has outlined the framework of the market, highlighting the key players, the regulatory environment, and the macroeconomic drivers. However, actionable strategy requires granular data. Our full market research report provides the detailed segmentation analysis, historical volume data, company profiles, and competitive benchmarking necessary to transform these insights into execution. To access the complete intelligence required for precise planning and investment decisions in this evolving sector, we invite you to explore the full study. The depth of data available there will empower your team to navigate the 2026 landscape with confidence.
For detailed analysis of this topic, please visit the official page: Speed Reducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


