



PW Consulting: Lymphedema Pneumatic Compression Market Hits $1.29B in 2025, Poised for 7.0% CAGR

Strategic Outlook: Navigating the Pneumatic Compression Devices for Lymphedema Market in 2026 and Beyond
The global landscape for pneumatic compression devices designed for lymphedema management is undergoing a structural transformation. As healthcare systems shift from reactive acute care to proactive chronic disease management, the demand for non-invasive, home-enabled therapeutic interventions has accelerated. Our latest research on the Pneumatic Compression Devices for Lymphedema Market provides a rigorous, data-grounded framework for executives, investors, and clinical strategy teams to navigate this growth trajectory with precision. This article sets the stage for the full report, outlining the macro forces, competitive realities, regulatory shifts, and strategic imperatives that will define decision-making through 2032.
A Market Reshaped by Volume, Velocity, and Value
The historical trajectory of this market tells a clear story of steady, compounding expansion. Between 2020 and 2025, global revenue climbed from approximately 925 million USD to nearly 1,300 million USD, reflecting a consistent upward curve driven by rising prevalence of chronic venous insufficiency, increased oncology survivorship rates, and broader adoption of conservative compression therapies as first-line interventions. The momentum does not slow in the forecast period. Projected to reach roughly 1,400 million USD in 2026, the market is positioned to accelerate further, with forward estimates indicating a climb toward 2,070 million USD by 2032. This trajectory translates to a compound annual growth rate of approximately 7 percent across the full forecast horizon, a pace that outstrips many adjacent durable medical equipment segments and underscores a durable demand cycle rather than a cyclical surge.
Pneumatic Compression Devices for Lymphedema Market
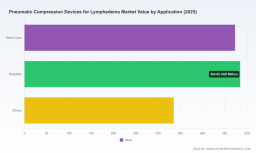
The growth is not merely a function of more units sold. It reflects a fundamental repositioning of pneumatic compression within clinical workflows. Hospitals, outpatient clinics, and home care environments each play distinct roles in the patient journey, yet the segmentation of revenue across these settings reveals an increasingly balanced ecosystem. Similarly, the product landscape continues to differentiate along the lines of segmented and non-segmented architectures, each addressing different clinical protocols and patient compliance profiles. The full report deconstructs these dynamics in depth, mapping how clinical efficacy, reimbursement alignment, and manufacturing economics intersect to shape where value accrues.
Competitive Architecture: Specialization, Differentiation, and Clinical Credibility
The supplier landscape is defined by a focused set of manufacturers that have built commercial and clinical moats around specific compression methodologies, garment engineering, and patient-access pathways. Rather than a commoditized price war, the market rewards companies that can demonstrate differentiated pressure profiles, ease of home use, and robust supporting evidence. Our competitive analysis profiles the leading participants and examines how their product strategies align with emerging reimbursement and clinical guidelines.
- Bio Compression Systems has established a strong foothold in the sequential compression segment with its Sequential Circulator line, emphasizing non-peristaltic pumping technology and multi-chamber garments tailored for lymphedema and chronic venous insufficiency. Their positioning reflects a long-standing focus on reproducible pressure delivery and clinical familiarity.
- Mego Afek, through its Lympha-Press and Lympha-Press Optimal systems, offers pneumatic compression pumps and garments that target lymphedema, venous insufficiency, and related conditions. The company’s international footprint and modular garment design position it to serve both clinical and home-based pathways across diverse reimbursement environments.
- Tactile Medical has carved out a distinctive presence in the home care segment with its Flexitouch and Flexitouch Plus advanced intermittent pneumatic compression systems. By pairing sophisticated compression sequencing with patient-centric garment engineering, the company addresses the compliance and usability challenges that often determine long-term adherence in at-home therapy.
- Neomedic’s Powerpress Unit Sequential Circulator continues to serve as a clinically oriented option for lymphedema and edema management, with distribution and product focus aligned to providers seeking reliable, prescription-grade compression solutions.
- Huntleigh Healthcare brings a broad diagnostics and care portfolio to the space, with its LymphAssist Professional and Hydroven 12 intermittent pneumatic compression systems and multi-chamber garments. Their presence highlights the intersection of diagnostic-led clinical decision-making and therapeutic device deployment.
- EEZCare Medical, through its EzLymph and EzLymph M pneumatic compression pumps, reflects the growing geographic diversification of the supply base, expanding manufacturing and distribution capacity to serve regional demand while maintaining clinical functionality.
- Koya Medical operates at the edge of the traditional pneumatic category with its Dayspring non-pneumatic active compression device, illustrating how adjacent technologies are expanding the broader conversation around chronic edema and lymphedema management. Its differentiated modality serves as a reminder that competitive pressure in this market extends beyond direct pneumatic substitutes to alternative compression philosophies.
The report does not stop at company descriptions. It examines how these players compete on clinical documentation, service networks, DME channel partnerships, and product line extensions. Concentration metrics indicate that while incumbents hold meaningful share, the market remains sufficiently open to well-positioned entrants that can align product performance with payer expectations and provider workflows.
Worldwide Mobile Whole Body Pressure Therapy Apparatus Market
Regulatory, Reimbursement, and Clinical Evidence: The Inflection Points That Matter
The commercial trajectory of pneumatic compression devices for lymphedema is inseparable from the policy and clinical environment. In 2026, decision-makers must operate within a tightening but clarifying framework of coverage criteria, device classification, and evidence expectations. Medicare’s national coverage architecture continues to anchor much of the reimbursement landscape, with coverage pathways tied to documented therapeutic need and conservative management prerequisites. All FDA-cleared pneumatic compression devices for lymphedema are regulated as Class II devices under a defined product code, and maintaining ISO 13485 certification remains a baseline requirement for quality management across manufacturers. These structural requirements shape not only market entry but also ongoing compliance, distributor relationships, and contracting risk.
The reimbursement code framework adds further granularity to commercial planning. Coverage under the durable medical equipment benefit relies on distinct HCPCS codes differentiated by segmental and gradient characteristics. This coding structure directly influences how devices are positioned, priced, and prescribed, and it creates natural segmentation in purchasing behavior. Payers increasingly assess clinical appropriateness through prior authorization and utilization management reviews. Recent activity signals a more active oversight environment: Medicare began initiating prior-authorization reviews for pneumatic compression devices effective in mid-April 2026, a policy shift with immediate operational implications for providers, DME suppliers, and device manufacturers alike.
At the same time, clinical evidence is strengthening the long-term rationale for intermittent pneumatic compression in lower extremity lymphedema management. Updated clinical directives and community care guidance have reinforced the role of sustained compression therapy where conservative measures alone are insufficient. Major payers have also revisited their coverage criteria, with recent guideline reviews updating clinical utilization parameters for pneumatic compression pumps. Together, these developments create a dual dynamic: heightened administrative scrutiny paired with stronger clinical endorsement for appropriate patient populations.
Why This Report Matters for 2026 Decision-Making
For executives planning capacity, pricing, channel strategy, and clinical positioning, the strategic question is no longer whether the market is growing, but where the growth is most defensible and how to capture it. This research is designed to translate macro momentum into actionable intelligence. It provides a structured view of historical performance, forward projection, and the operational levers that determine commercial outcomes in a market sensitive to reimbursement rules, clinical adoption, and product differentiation.
The report is built for practical use. It examines the full revenue arc across the forecast period, identifies the structural drivers behind the projected 7 percent compound growth, and situates that growth within the interplay of segmented and non-segmented device architectures. It maps the distribution of demand across home care, hospital, and clinic settings without reducing the story to a single channel narrative, because real-world adoption is shaped by referral pathways, DME logistics, and clinical protocols that vary by setting. It also breaks down regional performance in a way that highlights where mature demand, emerging adoption, and pricing dynamics create distinct strategic opportunities.
Equally important, the analysis integrates the competitive landscape with regulatory and reimbursement realities. It shows how prior authorization requirements, DME coding structures, coverage determinations, and quality certification expectations influence purchasing behavior, channel economics, and market entry timing. For device manufacturers, this means understanding which product features are most likely to satisfy payer and provider criteria. For distributors and DME providers, it means anticipating administrative burden and aligning service models accordingly. For investors, it means separating durable expansion from short-term policy noise.
What You Will Find Inside
- A complete historical and forecast revenue trajectory with the analytical context behind the growth curve, including the forces shaping the 2026 base and the acceleration path through 2032
- A detailed segmentation review across device type, care setting, and geography, with interpretation of how each segment’s economics and adoption drivers differ
- A competitive profile of the core participants, with emphasis on product architecture, clinical positioning, distribution strategy, and differentiation relative to adjacent modalities
- A synthesized analysis of regulatory and reimbursement dynamics, including device classification, coding structure, coverage prerequisites, prior authorization developments, and clinical evidence trends
- Strategic implications for product strategy, channel design, market entry, and pricing in a market where clinical credibility and reimbursement alignment increasingly determine commercial success
The full report delivers the complete dataset, scenario analysis, and segment-level interpretation needed to move from awareness to action. It also includes the most current policy and clinical developments as they evolve, ensuring that strategy is anchored to the operational reality of 2026 rather than outdated assumptions.
Positioning for the Next Phase of Growth
The Pneumatic Compression Devices for Lymphedema Market is entering a phase where scale matters, but precision matters more. Companies and investors that understand the interplay between clinical evidence, reimbursement architecture, competitive differentiation, and care-setting economics will be better equipped to allocate resources and shape long-term positioning. The macro forecast points to a market approaching the 2 billion USD threshold by the end of the forecast window, but the strategic value lies in understanding how that total is constructed and where competitive advantage can be built within it.
This research is intended as a decision-grade resource: rigorous enough to support executive planning, detailed enough to inform product and commercial strategy, and current enough to reflect the fast-moving policy environment. For teams evaluating product portfolios, market entry, partnership structures, or investment exposure, the full market report provides the foundation required to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Pneumatic Compression Devices for Lymphedema Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


